If you have Medicare: or will become eligible soon: September is the time to pay attention. Your 2027 Medicare Advantage and Part D plan information is expected to become available before the Annual Enrollment Period begins on October 15, 2026.
That gives you a valuable planning window. You can review your Annual Notice of Change, compare alternatives, check your prescriptions and providers, and make a confident decision before the December 7, 2026 enrollment deadline.
At Super Senior Services, we help Medicare beneficiaries in Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, and New York understand their options and choose coverage that supports their health, budget, and lifestyle.
“Find the plan that works for you.” : Medicare.gov
What to expect before October 15, 2026
Your current Medicare Advantage or Part D plan should send an Annual Notice of Change (ANOC) by September 30. This document explains the changes that will take effect on January 1, 2027, including:
- Monthly premiums
- Medical and prescription deductibles
- Copayments and coinsurance
- Prescription drug formulary changes
- Provider and pharmacy network changes
- Medicare Advantage out-of-pocket maximums
- Supplemental benefit changes
A formulary is the plan’s list of covered prescription drugs. Even if your medication remains covered, it could move to a different tier, resulting in a higher or lower copayment (for example, $10 versus $47 per prescription).
CMS also expects to release the finalized 2027 Medicare Advantage and Part D plan landscape in mid-to-late September. That information should provide plan-by-plan details before the Annual Enrollment Period begins. You can monitor official updates through the CMS Medicare Part D 2027 announcement and compare available plans through Medicare.gov Plan Compare.
Consequently, do not rely on a television advertisement or a plan’s current-year brochure alone. Your ANOC and the official Medicare plan comparison tools offer the most useful starting point.
2026 Medicare costs provide useful context
The final 2027 Part B premium has not yet been included in this preview. However, the current 2026 figures can help you understand the categories of costs to watch.
For 2026:
- The standard Part B premium is $202.90 per month for most beneficiaries.
- The annual Part B deductible is $283.
- The Part D annual out-of-pocket cap is $2,100 for covered prescription drugs.
- The maximum standard Part D deductible is $615.
- The national Part D base beneficiary premium is $38.99 per month.
Your actual costs may differ. Higher-income beneficiaries may pay an Income-Related Monthly Adjustment Amount (IRMAA), which is an additional premium based on income. Your Medicare Advantage or Part D plan may also charge a different premium, deductible, or copayment.
For 2027, CMS has announced several important Part D figures:
- The national average monthly bid amount is $296.05.
- The Part D base beneficiary premium is $41.33.
- The standard Part D deductible is expected to be $700.
- The annual Part D out-of-pocket threshold is expected to be $2,400.
The Part D Premium Stabilization Demonstration also ends after 2026. This temporary program helped limit premium volatility for certain standalone prescription drug plans. Without that additional stabilization, some Part D premiums may increase more noticeably in 2027, although the amount will vary by plan.
CMS describes the 2027 changes as a return to “traditional market conditions” for standalone Part D plans. In practical terms, your plan’s exact premium matters more than a national average.
Medicare Advantage: review more than the monthly premium
Medicare Advantage, also called Medicare Part C, combines Part A and Part B coverage through a Medicare-approved private plan. Most Medicare Advantage plans also include prescription drug coverage.
A plan may advertise a $0 monthly plan premium, but that does not necessarily mean your total Medicare cost is zero. You generally still pay your Part B premium unless your plan provides a Part B premium rebate, sometimes called a “giveback.”
Analyses of CMS plan data for 2026 found that:
- Approximately 75% of Medicare Advantage enrollees pay only the Part B premium for their plan, rather than an additional plan premium.
- Approximately 32% of individual Medicare Advantage enrollees are in plans offering a Part B rebate.
- The average enrollment-weighted in-network out-of-pocket maximum is around $5,421.
- Federal Medicare Advantage limits can reach $9,250 in-network or $13,900 for combined in-network and out-of-network costs, depending on the plan structure.
These figures show why a $0 premium is only one part of the decision. A plan with no monthly premium could have higher specialist copayments, a narrower provider network, or a higher maximum out-of-pocket limit.
When reviewing your 2027 Medicare Advantage options, ask:
- Are your primary care doctor and specialists in the network?
- Are your preferred hospitals included?
- Are your prescriptions covered at reasonable tiers?
- What is the medical maximum out-of-pocket amount?
- Do referrals or prior authorizations apply?
- Are dental, vision, hearing, transportation, or over-the-counter benefits changing?
- Is a Part B rebate available, and what conditions apply?
CMS’s 2027 Medicare Advantage payment policies project an average 2.48% increase in payments to Medicare Advantage plans, or more than $13 billion overall. That does not automatically mean your premium will increase by 2.48%. Plan benefits, premiums, networks, and cost-sharing can change independently.
The practical benefit of a side-by-side review is simple: you see how the plan works when you actually use healthcare: not just how it looks in an advertisement.
Medicare Supplement plans: a different approach to cost predictability
Medicare Supplement insurance, commonly called Medigap, works with Original Medicare rather than replacing it. A Medigap plan can help pay some of the deductibles, coinsurance, and copayments that Original Medicare does not fully cover.
Medigap plans are standardized by letter. For example, a Plan G sold by one insurer generally provides the same standardized benefits as a Plan G sold by another insurer. However, premiums can vary based on:
- Your location
- Your age
- The insurance company
- The plan letter
- The pricing method used by the insurer
Unlike Medicare Advantage, Medigap generally does not use a network for Medicare-participating providers. That can offer flexibility, but you typically pair Original Medicare with a separate Part D prescription drug plan.
Your Medigap Open Enrollment Period is usually the six-month period beginning when you are at least 65 and enrolled in Part B. During this period, you generally have stronger guaranteed-issue protections, meaning an insurer cannot use your health history to deny coverage or charge you more based on medical conditions.
Outside that period, medical underwriting may apply. Medical underwriting is the process an insurer uses to review your health information when deciding whether to issue a policy or what premium to charge.
There is no universal annual Medigap enrollment window comparable to Medicare’s October 15–December 7 Annual Enrollment Period. Therefore, if you are considering a move between Medicare Advantage and Original Medicare with Medigap, review eligibility, timing, and potential underwriting before making a change.
A step-by-step Medicare enrollment guide
Step 1: Confirm your Medicare foundation
Make sure you understand whether you have:
- Original Medicare Part A and Part B
- Medicare Advantage
- A standalone Part D plan
- Medicare Supplement insurance
- Employer or retiree coverage
If you are new to Medicare and are not automatically enrolled, Social Security handles enrollment in Part A and Part B. You can begin with the Social Security Medicare enrollment information.
If you delayed Part B because you had coverage through current employment, you may qualify for a Special Enrollment Period. Keep records of your employer coverage and ask Social Security about the required forms and deadlines.
Step 2: Read your ANOC carefully
Do not file the ANOC away without reviewing it. Compare the 2026 and 2027 columns line by line, focusing on the costs you use most often.
For example, if you take five prescriptions each month, a $12 increase in one medication’s copayment could add approximately $720 per year. A specialist copayment increase from $35 to $55 could add another $240 annually if you have one visit each month.
Small changes can become large expenses.
Step 3: Make a medication and provider checklist
Write down:
- Every prescription, including dosage and frequency
- Your preferred pharmacy
- Your primary care provider
- Specialists
- Hospitals and urgent care centers
- Ongoing treatments
- Dental, vision, hearing, or transportation needs
Then compare this information with each plan’s formulary and provider directory. If a plan directory is unclear, call the plan or work with a licensed professional before enrolling.
Step 4: Compare total annual costs
Look beyond the monthly premium. Estimate:
- Annual premiums
- Deductibles
- Routine copayments
- Prescription costs
- Specialist and hospital costs
- Maximum out-of-pocket exposure
A plan costing $25 more per month may save you hundreds of dollars if it covers your prescriptions at lower tiers. Conversely, a $0-premium plan may not be the most affordable choice if your doctors are out of network.
Step 5: Enroll or make changes between October 15 and December 7
The Medicare Annual Enrollment Period runs from October 15 through December 7, 2026. Changes made during this period generally take effect on January 1, 2027, assuming the plan receives and approves your enrollment.
Use Medicare.gov Plan Compare for official comparisons, or request personalized guidance before submitting an application.
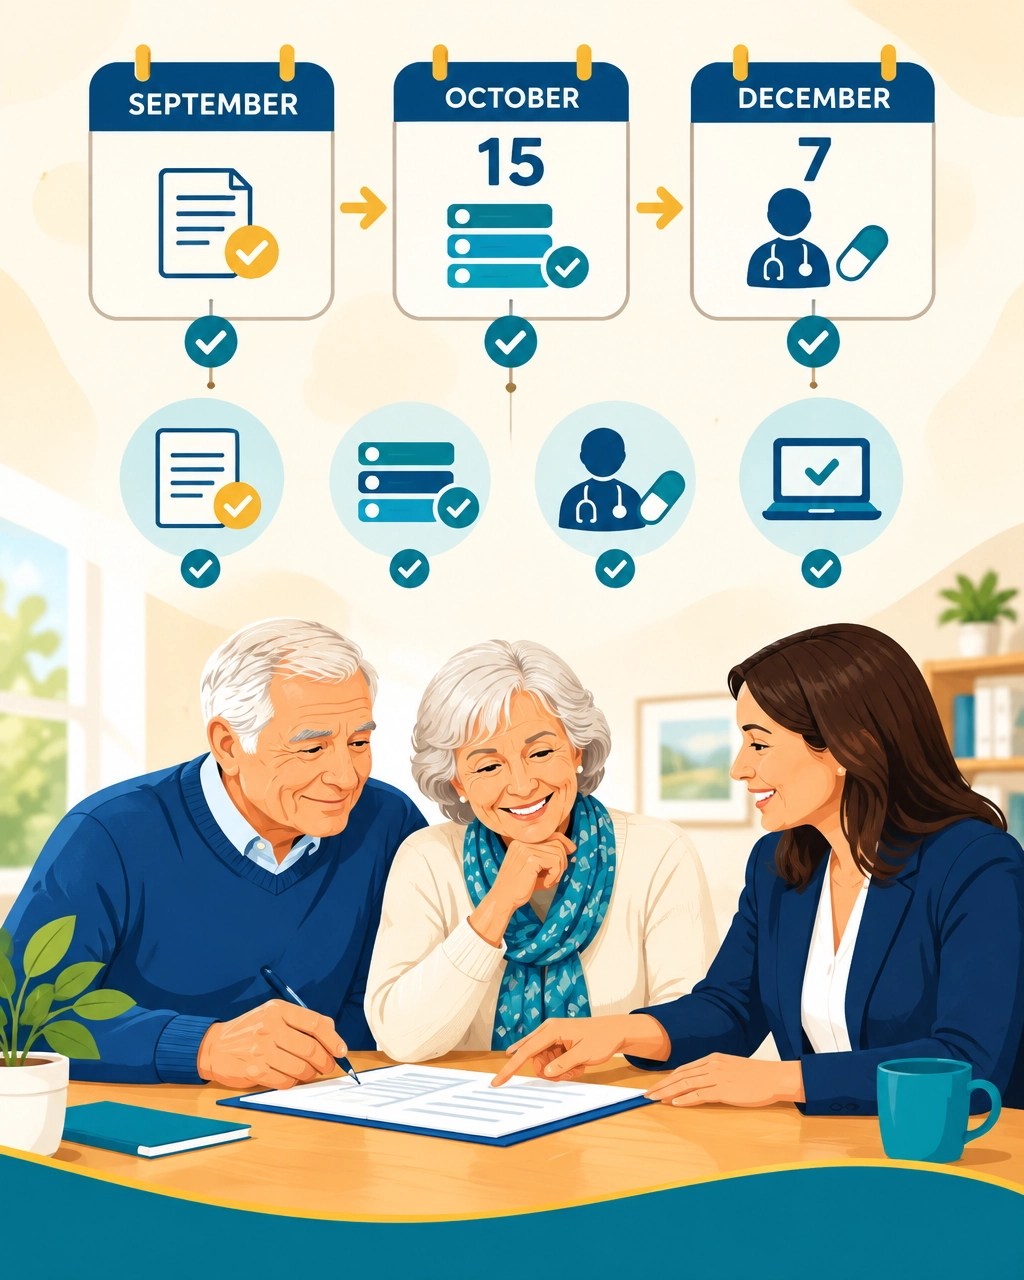
Prepare now for a more confident decision
You do not have to wait until October 15 to begin. Gather your ANOC, medication list, provider information, and recent healthcare bills now. Once the 2027 plan details are available, you will be ready to compare quickly and carefully.
Super Senior Services simplifies that process with personalized Medicare plan reviews for residents in Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, and New York. We help you compare Medicare Advantage, Part D, and Medicare Supplement options based on your healthcare priorities: not just a promotional premium.
Visit our Medicare Plans page or contact Stephen Jackson to discuss your 2027 Medicare options. With expert guidance, transparent comparisons, and a focus on affordability and financial stability, you can approach January with greater confidence and peace of mind.
Compliance note: Individual NPN: Stephen Jackson, 20707378. Corporate NPN: Super Senior Services, 21536694.
WordPress category: medicare