WordPress category: finalexpense
Planning for funeral costs may not be easy to discuss, but it can be one of the most caring financial decisions you make for your family. The right final expense coverage can help your loved ones avoid searching for thousands of dollars during an already difficult time.
For seniors living on Social Security, a pension, or another fixed monthly income, the key is not buying the largest policy available. It is choosing affordable burial insurance that fits comfortably into your budget today and remains manageable years from now.
In this guide, you will learn how final expense premiums are priced, how to select a coverage amount, and how to reduce the risk of a policy lapse.
Start With Your Monthly Budget, Not the Policy Maximum
Final expense insurance for seniors is typically a small whole life policy designed to help pay funeral, burial, cremation, medical bills, or other expenses after death. Common coverage amounts range from $5,000 to $25,000, although some insurers offer higher limits.
Your first step should be a simple income-and-expense review:
- Add your dependable monthly income, including Social Security and pension payments.
- List essential expenses such as housing, utilities, groceries, medications, and transportation.
- Identify the amount remaining after necessities.
- Choose a premium that leaves room for emergencies and rising household costs.
For example, if you receive $2,200 per month and have $2,050 in essential expenses, a $50 monthly premium may be reasonable while a $150 premium could create unnecessary pressure. Affordability matters because even an excellent policy can become a problem if the payment is difficult to maintain.
As a general illustration, a healthy 65-year-old might see premiums around $30–$80 per month for a modest policy, depending on the coverage amount, health history, tobacco use, gender, state, and insurance company. These are sample ranges, not a quote.
A personalized comparison can help you find the balance between meaningful protection and financial stability. Contact Super Senior Services for guidance based on your age, health, and budget.
Use Funeral Costs to Estimate the Coverage Amount
The National Funeral Directors Association reported median 2023 costs of approximately $8,300 for a funeral with viewing and burial and $6,280 for a funeral with viewing and cremation. You can review the NFDA’s funeral statistics for additional information.
Those figures may not include every expense. Cemetery property, a grave marker, an outer burial container, transportation, death certificates, obituary notices, and other cash-advance items can increase the final bill.
A practical starting point may look like this:
- $5,000–$8,000: May help with a basic cremation or a portion of burial expenses.
- $10,000–$15,000: May provide broader support for funeral services, transportation, cemetery costs, and small debts.
- $20,000–$25,000: May be appropriate when you expect higher burial costs, want to leave additional funds for family expenses, or have limited savings.
You do not necessarily need coverage equal to the total funeral cost. Existing savings, a prepaid cemetery plot, veterans’ benefits, or a payable-on-death account may cover part of the need. Consequently, you may be able to purchase a smaller policy and keep the premium within your fixed-income budget.
The Federal Trade Commission’s Funeral Rule can also help you compare costs. The FTC explains that, generally, “You may choose only the items you desire.” Funeral homes must provide itemized pricing and cannot require you to purchase unwanted goods or services, subject to limited exceptions. Visit the FTC’s Funeral Rule guidance before finalizing your estimate.
Understand How Final Expense Premiums Are Priced
Final expense premiums are usually level, meaning the premium is set when the policy is issued and generally does not increase simply because you get older. You must continue making payments according to the policy terms to keep coverage active.
Several factors influence the price:
- Age: Waiting until your 70s or 80s usually results in higher premiums.
- Health: Certain medical conditions may affect eligibility and rates.
- Tobacco use: Smokers often pay more than nonsmokers.
- Coverage amount: A $15,000 policy generally costs more than a $10,000 policy.
- Underwriting type: Simplified issue and guaranteed issue policies price risk differently.
- Payment schedule: Monthly, quarterly, or annual payment options may have different costs.
Buying earlier may help you lock in a lower level premium. However, affordability should remain the priority. A policy that fits your budget at age 65 is more valuable than a larger policy that becomes difficult to maintain at age 70.
Simplified Issue vs. Guaranteed Issue: The Cost Tradeoff
Understanding these two policy types is especially important when you are trying to purchase affordable burial insurance.
Simplified-issue coverage usually requires no medical exam, but you answer health questions. The insurer may also review prescription or medical information. If you qualify, you may receive a lower premium and, depending on the policy, an immediate full death benefit.
For example, a healthy applicant might qualify for $10,000 of coverage at approximately $30–$80 per month, while a higher-risk applicant could receive a different rate or be declined.
Guaranteed-issue coverage generally does not require health questions or a medical exam. Because the insurer accepts applicants without reviewing their health, the premium is usually higher for the same coverage amount. Many guaranteed-issue policies also include a graded benefit period, such as the first two years, during which a natural-death claim may return premiums plus interest rather than pay the full benefit. Accidental death provisions may be different.
Guaranteed issue can be useful when serious health conditions prevent you from qualifying elsewhere. However, if you can answer simplified-issue questions favorably, that option may provide better value and more immediate protection.
Ask these questions before selecting a policy:
- Is the premium level for life?
- Is the death benefit immediate or graded?
- What happens if death occurs during the waiting period?
- Are there exclusions or limitations?
- What happens if a premium is missed?
- Is there cash value, and how does using it affect the policy?
Super Senior Services can help simplify these comparisons so you understand both the benefits and the financial tradeoffs.
How to Avoid a Policy Lapse on a Limited Budget
A lapse means coverage ends because required premiums were not paid. For a senior living on a fixed income, preventing a lapse should be part of the purchasing decision.
Use these practical safeguards:
- Schedule the premium around your income: If Social Security arrives on the second Wednesday, ask whether the draft can occur shortly afterward.
- Use automatic payments carefully: Keep enough funds in the account and update the insurer if your bank information changes.
- Choose a sustainable amount: Reducing coverage from $15,000 to $10,000 may be wiser than selecting a premium you can barely afford.
- Review the policy annually: An annual review can confirm that your beneficiary, payment method, and coverage amount remain appropriate.
- Contact the insurer before missing a payment: Policies often include a grace period, but the length and reinstatement rules vary.
- Do not cancel an existing policy too quickly: If replacing coverage, wait until the new policy is approved, issued, and active.
- Be cautious with policy loans: Borrowing against cash value can reduce the death benefit and may affect the policy if interest accumulates.
If a premium becomes difficult, speak with a licensed professional before canceling. There may be alternatives, but they depend on the policy’s provisions and your circumstances.
State Considerations for Final Expense Coverage
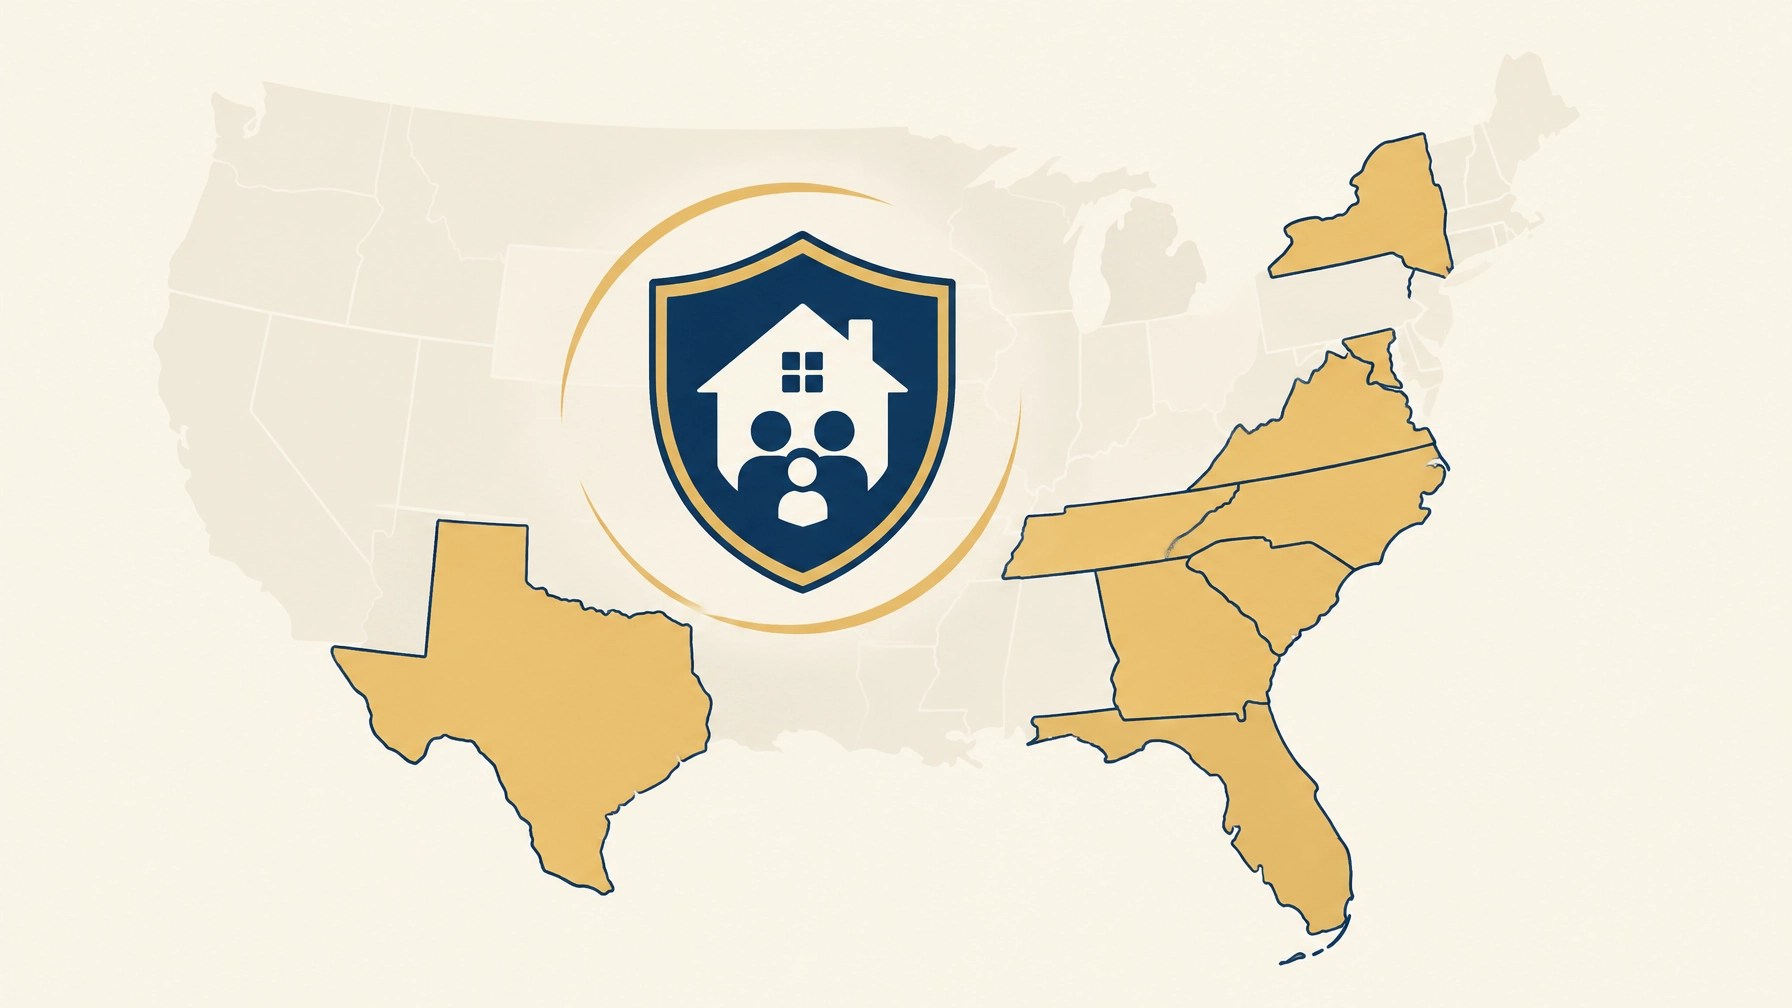
Final expense insurance can be available across the states where Super Senior Services provides Medicare and senior-services guidance. Carrier availability, underwriting rules, policy forms, and pricing can vary by state.
- Florida: When comparing final expense insurance Florida options, ask whether the policy is level-benefit or graded and review the insurer’s payment and reinstatement provisions.
- Georgia: In Georgia, compare at least several carrier options because age, tobacco use, and health answers can affect premiums substantially.
- Texas: For seniors in Texas, request an itemized comparison of coverage amount, monthly premium, waiting period, and beneficiary provisions.
- Tennessee: In Tennessee, confirm whether a simplified-issue application could qualify you for a lower premium before considering guaranteed issue.
- North Carolina: For North Carolina residents, make sure the premium fits comfortably after housing, food, utilities, and medication costs.
- South Carolina: In South Carolina, ask how the policy handles missed payments and whether a grace period applies.
- Virginia: Seniors in Virginia should review the policy’s exclusions, graded-benefit language, and financial strength information before applying.
- New York: For New York residents, compare policy forms and disclosures carefully, since state-specific requirements and carrier availability may affect the options presented.
Choose Peace of Mind Without Overstretching Your Income
The goal of final expense coverage is straightforward: help your family manage expenses without forcing them to make rushed financial decisions. You can pursue that goal with a budget-first approach:
- Estimate realistic burial or cremation costs.
- Subtract savings, prepaid arrangements, and other available resources.
- Select a coverage amount between $5,000 and $25,000 that addresses the remaining need.
- Compare simplified issue and guaranteed issue pricing.
- Confirm that the level premium fits your monthly income.
- Set up a reliable payment system to help prevent a lapse.
The right policy is not necessarily the biggest policy. It is the one that provides meaningful protection while preserving your financial stability and peace of mind.
Super Senior Services can help you review affordable burial insurance options, compare trusted carriers, and understand the differences between coverage types. Contact Stephen Jackson to discuss your goals and budget. You can also compare Medicare plans as part of your broader annual coverage review.
Individual NPN, Stephen Jackson: 20707378. Corporate NPN, Super Senior Services: 21536694.