Compliance note: Individual NPN: Stephen Jackson: 20707378 | Corporate NPN: Super Senior Services: 21536694
WordPress category: businesshealth
If you are a New York small business owner reviewing your 2027 health insurance renewal in early October 2026, you may be comparing another traditional small-group plan with an Individual Coverage Health Reimbursement Arrangement, commonly called an ICHRA.
The right answer depends on your workforce, budget, administrative capacity, and employees’ coverage needs. An ICHRA can create more flexibility and predictable employer spending, but it is not simply a group plan with a different name.
Let’s walk through how it works, where the rules become important, and how to compare it fairly with a traditional New York small-group plan before a potential January 1, 2027 effective date.
What Is an ICHRA?
An ICHRA is an employer-funded reimbursement arrangement. Your business establishes a monthly or annual allowance that eligible employees can use to reimburse premiums for qualifying individual health insurance and certain qualified medical expenses.
Employees generally purchase and maintain their own qualifying individual coverage, such as a plan available through NY State of Health or another approved individual insurance source. They then submit documentation through the ICHRA administrator to receive reimbursement up to the amount your business has established.
As HealthCare.gov explains, “CHOICE Arrangements (formerly known as the Individual Coverage Health Reimbursement Arrangements, or ICHRAs) are a way for employers to provide tax-free reimbursements to employees for qualified medical expenses up to a set annual amount.”
A traditional group plan works differently. Your company selects one group policy or a defined group-plan structure, pays part of the premium, and employees generally enroll in that employer-sponsored coverage. The group plan may offer a shared network, standardized benefits, and one carrier relationship.
An ICHRA gives employees more plan choice. A group plan gives your business and employees more uniformity.
Why a New York Employer Might Consider an ICHRA
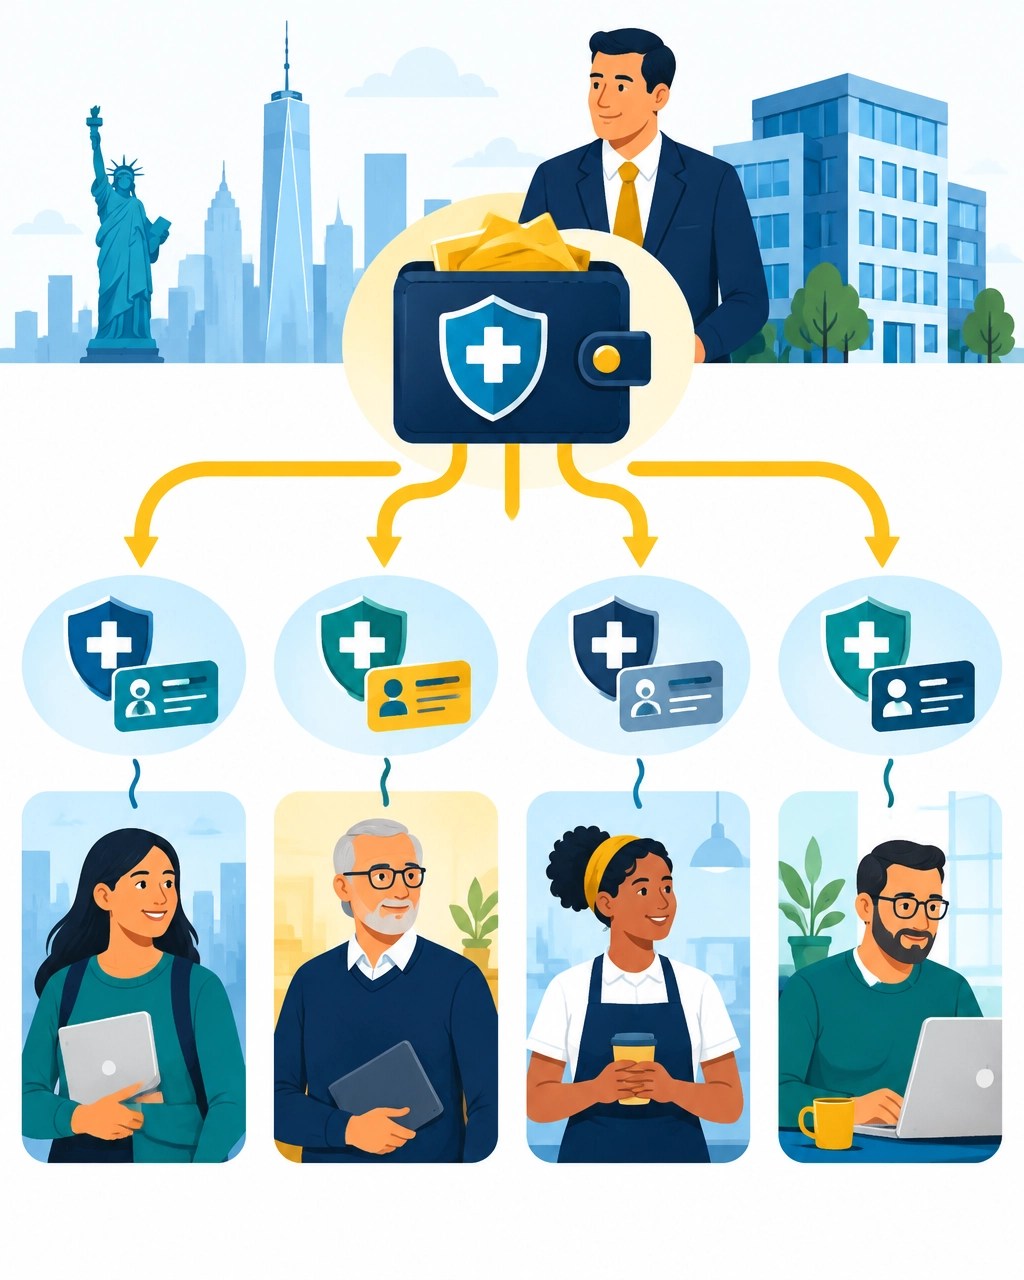
An ICHRA may be worth evaluating if your team has different schedules, locations, ages, and healthcare preferences.
Potential advantages include:
- Predictable employer spending: You choose the reimbursement amount rather than committing to a percentage of a group premium that may rise at renewal.
- Individual plan choice: Employees can compare qualifying options available in their county through NY State of Health, instead of receiving one company-wide plan.
- Workforce flexibility: An ICHRA may fit businesses with full-time, part-time, seasonal, salaried, hourly, or remote employees, provided eligible classes are structured according to federal rules.
- Different coverage needs: One employee may prioritize a lower premium, while another may prefer a broader provider network or lower deductible.
- Potentially simpler employer budgeting: A defined allowance can make monthly forecasting easier than absorbing a percentage of changing group premiums.
This flexibility can be especially useful when employees live in different New York counties, where individual premiums and available networks may vary.
However, flexibility is only valuable when employees understand their options. Your team may need assistance comparing premiums, deductibles, copayments, coinsurance, formularies, provider networks, and the effect of the ICHRA on premium tax credits.
That is where a comprehensive benefits review can protect both your budget and your employees’ peace of mind.
When a Traditional Group Plan May Still Be Better
An ICHRA is not automatically less expensive or easier than group coverage.
A traditional New York small-group plan may be a better fit when:
- Your employees value having one common plan and network.
- You want a more uniform employee experience.
- Your workforce is comfortable with established participation rules.
- You prefer the carrier to handle much of the enrollment structure.
- The group plan offers richer benefits than employees could obtain individually.
- Your business may qualify for the Small Business Health Care Tax Credit through eligible group coverage.
- Your employees would find individual plan shopping confusing or time-consuming.
Group coverage also pools the risk of enrolled employees. An individual market approach separates employees into their own plan selections, with premiums affected by age, household composition, county, plan design, and other rating factors.
Consequently, the lowest employer contribution does not always produce the lowest total cost for employees. A plan with a smaller allowance may leave some workers paying substantially more out of pocket.
The ICHRA Rules That Trip Employers Up
Before selecting an ICHRA, understand these core requirements.
1. Employee classes must be objective and documented.
You cannot create a class based on health status, claims history, or a desire to exclude employees who may need more care. Permitted criteria can include full-time or part-time status, salaried or non-salaried status, seasonal status, waiting periods, work location, and certain combinations of objective employment characteristics.
Your plan documents should clearly define who is eligible.
2. Allowances must be consistent within each class.
Employees in the same class generally must receive the ICHRA on the same terms. The reimbursement amount may vary based on age or number of dependents, but age-based differences cannot exceed the applicable 3:1 ratio.
For example, you cannot informally give one employee a larger allowance because that employee has expensive prescriptions. You must use an approved class structure and apply it consistently.
3. You must provide the required notice.
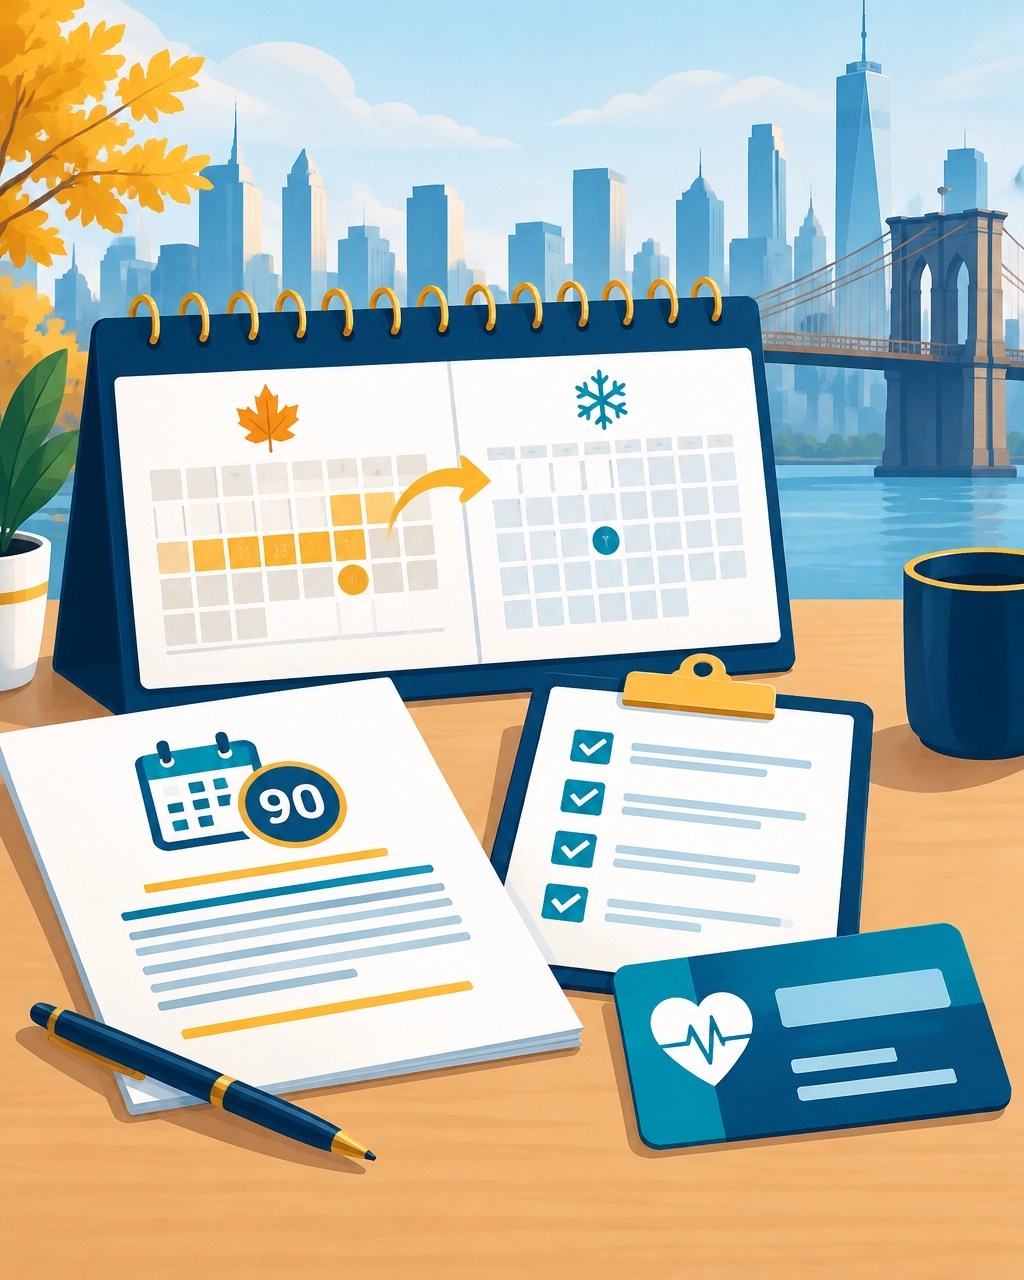
For a January 1, 2027 plan year, eligible employees generally must receive the written ICHRA notice at least 90 days before the plan year begins, around October 3, 2026. New employees generally must receive the notice by the date they become eligible.
The notice should explain the allowance, eligibility rules, how the arrangement affects Marketplace financial assistance, and how employees can use the offer when applying for coverage.
If you are finalizing your 2027 renewal now, do not delay this step.
4. Employees in the same class generally cannot choose between a group plan and an ICHRA.
You may be able to offer a traditional group plan to one permitted class and an ICHRA to another. However, employees in the same class generally cannot choose whichever arrangement they prefer during the same plan year.
Minimum class-size rules may also apply when you divide employees between group coverage and an ICHRA. For employers with fewer than 100 employees, certain split arrangements may require at least 10 employees in the ICHRA class. Larger employers may face different percentage or headcount requirements.
Because these rules can affect the legality and practical design of your benefits package, review the structure with a qualified benefits professional before communicating an offer.
Affordability, Taxes, and Premium Tax Credits
An ICHRA is employer-funded. Reimbursements may be tax-free to employees when they have qualifying individual health coverage and the arrangement is properly designed and administered.
The allowance cannot be funded through an employee’s pre-tax salary reduction. In other words, you cannot simply reduce an employee’s wages and call the amount an ICHRA contribution.
That is different from a Section 125 cafeteria plan, which may allow employees to pay their share of a traditional group-plan premium through pre-tax payroll deductions when properly established. Your tax or benefits professional can help determine whether a separate payroll arrangement is appropriate.
You also need to model how the ICHRA affects premium tax credits. Employees generally cannot receive a premium tax credit for the same months in which they use an affordable ICHRA offer.
For 2027, HealthCare.gov states that an ICHRA is considered affordable when the employee’s monthly cost for the lowest-cost Silver plan after the reimbursement is less than 10.22% of one-twelfth of household income. If the offer is affordable, the employee and household members generally cannot receive a Marketplace premium tax credit, even if the employee declines the ICHRA.
If the offer is unaffordable, the employee may generally choose between using the ICHRA or declining it and applying for a premium tax credit, if otherwise eligible. The employee cannot use both for the same coverage period.
Medicare-eligible employees require additional care. Medicare premium reimbursement and coordination with an ICHRA should be reviewed with a qualified tax or benefits professional before your company makes an offer.
A Practical Dollar Comparison
Suppose your current renewal discussion includes a traditional group premium of $650 per month for employee-only coverage, with your business contributing 50%.
Your employer cost would be:
- $650 × 50% = $325 per month
- $325 × 12 months = $3,900 per employee annually
Now compare that with an ICHRA:
- A 25-year-old employee receives a $300 monthly allowance ($3,600 annually).
- A 60-year-old employee receives a $700 monthly allowance ($8,400 annually).
At first glance, the ICHRA appears less expensive for the younger employee and more expensive for the older employee. But the employee’s individual premium matters.
For illustration only:
- If the 25-year-old’s individual premium is $360 per month, the employee may pay approximately $60 after the $300 allowance.
- If the 60-year-old’s individual premium is $950 per month, the employee may pay approximately $250 after the $700 allowance.
The employer cost is different from the employee’s final premium. You must evaluate both.
Also, the $300 and $700 allowances cannot be assigned casually by individual employee. If age-based differences are used, they must follow the applicable age-rating rules and be established within a valid employee class. The allowance must never be based on an employee’s health condition or personal claims experience.
NY State of Health Enrollment Timing Matters
For a January 1, 2027 ICHRA start, employees should begin reviewing their individual coverage during the 2027 open enrollment period of November 1, 2026, through January 31, 2027, according to the planning timeline provided for this series.
Do not wait until late December. Employees need time to:
- Review their ICHRA notice.
- Compare individual plans available in their New York county.
- Check provider networks and prescription formularies.
- Report the ICHRA offer accurately.
- Determine whether the offer affects premium tax credit eligibility.
- Select coverage effective January 1, 2027.
A special enrollment period may apply when an employee gains access to an ICHRA outside the annual enrollment period, loses other qualifying coverage, or experiences another eligible life event. Employees should confirm their specific timing directly with NY State of Health.
ICHRA vs. Traditional New York Small-Group Plan
| Consideration | ICHRA | Traditional group plan |
|---|---|---|
| Funding | Employer sets a defined reimbursement allowance | Employer generally contributes toward a group premium |
| Plan choice | Employees choose qualifying individual coverage | Employer selects the group-plan options |
| Administration | Requires notices, class design, substantiation, and employee education | One group enrollment structure, but carrier and participation rules apply |
| Tax treatment | Employer-funded reimbursements may be tax-free when properly administered | Employer premium contributions generally receive favorable tax treatment |
| Premium tax credits | Affordable offers generally affect employee eligibility for credits | Affordable, qualifying group coverage can also affect credit eligibility |
| Participation rules | Class and same-terms rules are critical | Carrier participation and contribution requirements are established |
| Employee experience | More personal choice, but more individual decision-making | More uniform benefits and simpler plan comparison |
Your 2027 Decision Checklist
Before choosing an ICHRA or renewing a group plan, ask:
- What is our total employer budget per employee and for the entire year?
- Which employees will be eligible, and can we document valid classes?
- Do we have full-time, part-time, seasonal, remote, or multi-county employees?
- Would employees value individual plan choice or one common group plan?
- How will age-rated individual premiums affect different employees?
- Could our allowance be affordable under the 2027 federal standard?
- How might the offer affect employees’ premium tax credits?
- Can we deliver the required 90-day notices on time?
- Who will administer reimbursements and verify qualifying coverage?
- Do Medicare-eligible employees require additional tax or benefits review?
- Are we comparing deductibles, coinsurance, prescription coverage, and networks, not just premiums?
- Have we considered whether eligible group coverage could provide access to a small-business tax credit?
The best answer is rarely found in a headline premium comparison. It comes from a comprehensive benefits review that considers employer affordability, employee costs, compliance, plan quality, administration, and long-term financial stability.
Super Senior Services helps New York businesses simplify these decisions through personalized plan comparisons and practical guidance. To review your 2027 options, contact Super Senior Services.