Category: finalexpense
Planning for funeral expenses may feel uncomfortable, but the numbers make the conversation worthwhile. In 2026, a traditional funeral with burial can cost thousands of dollars before a cemetery plot, headstone, or opening and closing fees are added.
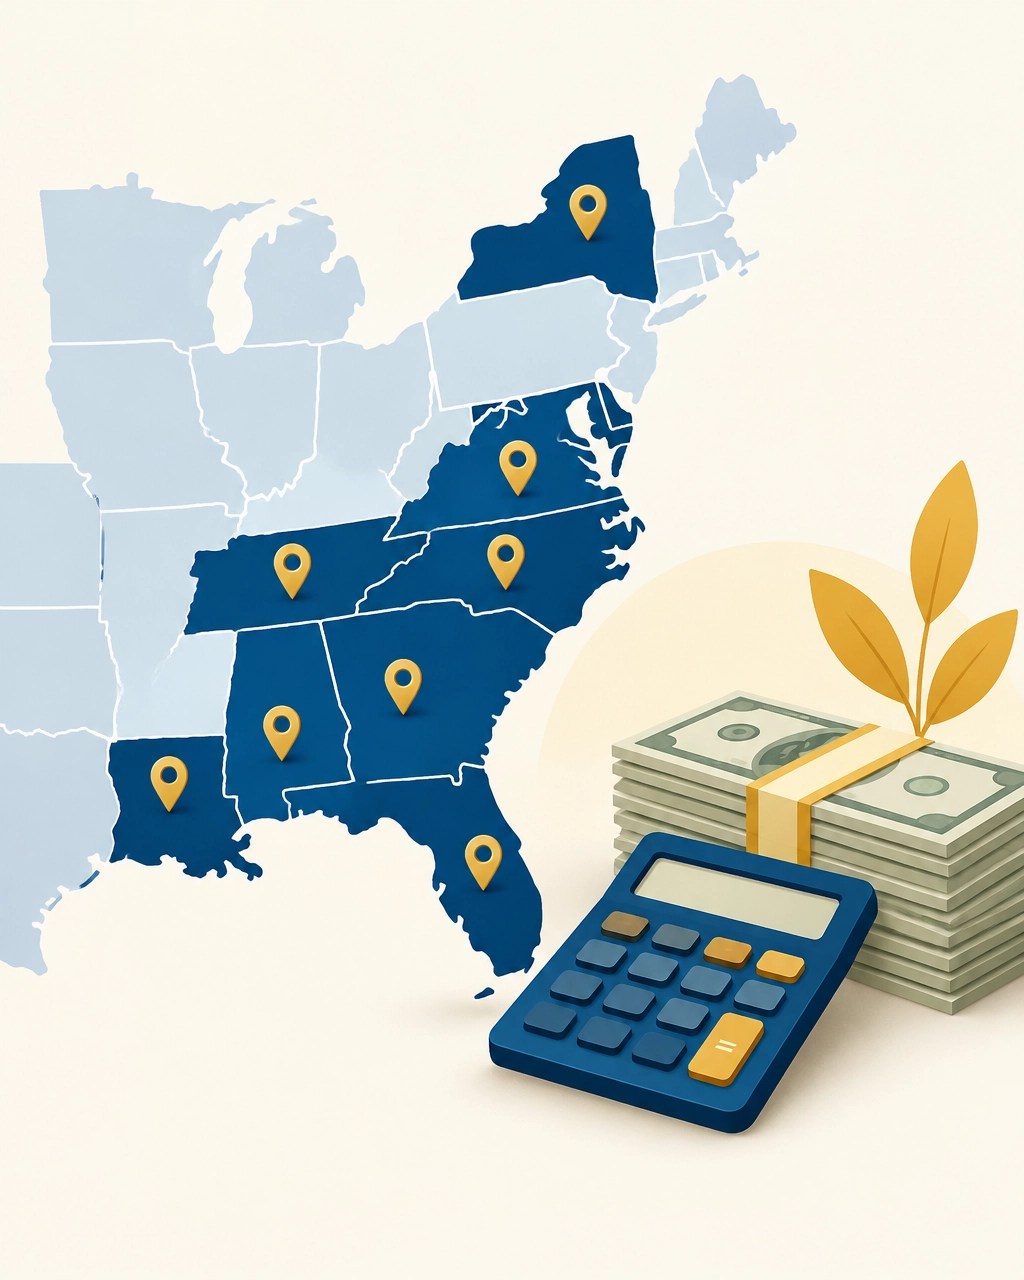
For families in Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, and New York, final expense insurance for seniors can create a dedicated source of funds. The goal is simple: help your loved ones manage funeral bills without draining savings, waiting for probate, or relying on credit cards.
“A one-time lump-sum death payment of $255 may be paid to a qualifying spouse or child.”- Social Security Administration
That payment can help, but it is far below the cost of most funerals. Medicare also does not provide a funeral benefit. A modest, carefully designed policy can provide more meaningful financial stability.
Compliance note: Individual NPN, Stephen Jackson: 20707378. Corporate NPN, Super Senior Services: 21536694.
The real 2026 funeral numbers, state by state
The following figures represent estimated average funeral-home charges for a traditional funeral with burial. The figures are based on the 2026 state cost data reported by PinnacleQuote.
| State | Average funeral with burial | Practical planning range |
|---|---|---|
| Florida | $7,702 | $8,000–$10,000 |
| Georgia | $7,416 | $8,000–$10,000 |
| Texas | $7,813 | $8,000–$10,000 |
| Tennessee | $7,701 | $8,000–$10,000 |
| North Carolina | $7,701 | $8,000–$10,000 |
| South Carolina | $7,623 | $8,000–$10,000 |
| Virginia | $8,034 | $8,000–$12,000 |
| New York | $10,824 | $10,000–$15,000 |
These are funeral-home charges only. They generally do not include a cemetery plot, vault, headstone, grave marker, opening and closing costs, obituary, flowers, transportation, or a reception. Those additional items can add several thousand dollars (for example, $2,000–$6,000 or more depending on location and choices).
Consequently, a $5,000 policy may cover only part of the bill in many areas. A $10,000 policy may be more practical for a traditional burial, while a $15,000–$25,000 policy may be appropriate when you want additional flexibility.
The right amount depends on your wishes, existing savings, veteran benefits, and what your family would realistically need. Contact Super Senior Services for a personalized review.
How final expense coverage can protect your family
Final expense insurance, also called burial insurance or simplified issue life insurance, is usually a small whole life policy with a fixed premium and a death benefit that does not decrease as you age.
Typical face amounts range from $5,000 to $25,000. Your beneficiary can generally use the money for:
- Funeral-home and cemetery charges
- Burial or cremation expenses
- Headstones and memorial services
- Medical bills, credit cards, or other final debts
- Travel and immediate household expenses
Unlike money tied up in a bank account or probate estate, life insurance proceeds are generally paid directly to the named beneficiary after the claim is approved. That can give your family access to funds when they need them most.
Medicare is health insurance, not funeral insurance. You can review official program information at Medicare.gov and CMS.gov. Social Security’s $255 payment may help eligible survivors, but it is not designed to cover a $7,000–$11,000 funeral.
A final expense policy gives your family a clear financial resource. That clarity can reduce stress during an already difficult time.
Level benefit or graded benefit: know the difference
One of the most important decisions is whether you qualify for a level benefit or a graded benefit policy.
Level benefit
A level-benefit policy generally pays the full death benefit from the beginning, subject to the policy terms. It is typically available when your health history meets the insurer’s underwriting requirements.
Many policies use simplified issue underwriting, meaning you answer health questions and may not need a medical exam. The insurer may still review prescription records, medical databases, and other information.
Graded benefit
A graded or modified-benefit policy may be available when significant health conditions make level coverage unavailable. These plans commonly include a two-year waiting period for natural-cause deaths.
During that period, the policy may pay only a return of premiums plus interest or another limited amount. Accidental death provisions vary by carrier. After the waiting period, the full benefit generally becomes available under the contract.
Graded coverage can provide access when other options are limited, but it may cost more for the same face amount. That makes a professional comparison especially valuable. You want coverage that fits your health profile, budget, and family objective, not simply the first policy you see.
What might premiums cost in 2026?
Premiums vary by age, gender, tobacco use, state, health history, carrier, face amount, and whether the policy is level or graded. The following are broad planning ranges for nonsmokers in average health, not personal quotes.
| Age | Coverage | Approximate monthly range |
|---|---|---|
| 65 | $5,000 | $25–$45 |
| 65 | $25,000 | $110–$160 |
| 75 | $5,000 | $40–$80 |
| 75 | $25,000 | $190–$320 |
Published rate comparisons from sources such as Insure.com, MoneyGeek, and Choice Mutual show why applying earlier can matter. A healthy 65-year-old may qualify for substantially lower premiums than a 75-year-old applying for the same benefit.
Before choosing $25,000 of coverage, ask a practical question: Will your family actually need that much? Overbuying can create unnecessary premiums. If your expected funeral cost is $8,000 and you have $3,000 set aside, a $10,000 policy may be more efficient than a $25,000 policy.
Super Senior Services can help compare affordable burial insurance options based on your actual needs, not a one-size-fits-all target.
The beneficiary decision: keep the benefit outside probate when appropriate
A final expense policy generally reaches your family most efficiently when you name a specific person as beneficiary.
Name a person, not “my estate.”
When you name an individual beneficiary, such as your spouse, adult child, or another trusted person, the death benefit will typically pass directly to that person outside probate. When you name “my estate,” or fail to update a beneficiary after that person dies, the proceeds may enter the probate estate.
That distinction matters because Medicaid estate recovery generally involves a claim against the deceased person’s estate for certain Medicaid-paid services. Federal guidance from Medicaid.gov explains that states must maintain estate recovery programs, particularly for certain long-term services and supports received after age 55.
For many families in Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, and Virginia, estate recovery is pursued through the probate process, and a policy payable to a named person typically does not become a probate asset. However, state rules differ.
New York requires special care. New York uses an expanded definition of “estate” that can include certain non-probate assets. Review the New York Medicaid estate recovery guidance and consider professional estate-planning guidance before relying on a beneficiary designation for a specific Medicaid-planning outcome.
You can also review the official state resources for:
- Florida Medicaid Estate Recovery
- Georgia Medicaid Estate Recovery Fact Sheet
- Texas Medicaid Estate Recovery information
- Tennessee TennCare Estate Recovery
- North Carolina Medicaid Estate Recovery
- South Carolina Estate Recovery
- Virginia Medicaid Estate Recovery Fact Sheet
- New York Medicaid Estate Recovery
Beneficiary designations should be reviewed whenever there is a marriage, divorce, death, family conflict, or major change in your financial situation.
How to fit a premium into a fixed Social Security budget
A premium should support your peace of mind without disrupting essentials such as housing, food, prescriptions, utilities, and transportation.
Try this simple process:
- Start with the funeral goal. Choose a realistic amount (for example, $8,000, $10,000, or $15,000).
- Subtract existing resources. Include savings earmarked specifically for final expenses, but do not count money needed for everyday living.
- Compare level and graded options. A lower premium is not always better if the policy has a waiting period or insufficient benefit.
- Set the premium beside your monthly budget. A $35 monthly premium equals about $1.17 per day; a $75 premium equals about $2.50 per day.
- Avoid replacing essential spending. If the premium would cause missed prescriptions or unpaid bills, reduce the face amount and review other options.
Schedule a free annual policy review
Your needs can change. Funeral costs rise, beneficiaries move, health circumstances change, and your savings may grow or shrink. A free annual policy review helps confirm that:
- Your beneficiary information is current
- Your coverage still matches your final expense goal
- Your premium remains affordable
- Your policy is still appropriate compared with available options
- Your family knows where to find the policy documents
Final expense insurance for seniors should be understandable, affordable, and aligned with your wishes. Whether you are exploring final expense insurance in Florida, Texas, New York, Georgia, North Carolina, South Carolina, Tennessee, or Virginia, Super Senior Services can simplify the comparison and guide you through the enrollment process.
Contact Stephen Jackson and request your personalized final expense review.