Running a small business in New York is an exhilarating challenge. Between navigating the fast-paced market of the Empire State and managing your daily operations, you also face the critical task of attracting and retaining the best talent. In today’s competitive landscape, offering a quality health insurance package isn't just a "nice-to-have": it is often the deciding factor for a top-tier candidate choosing between you and a larger competitor.
However, as a NY business owner, you’re likely all too familiar with the rising costs of premiums. You want to take care of your team, but you also need to keep your overhead manageable. The good news is that New York offers several unique pathways to affordable coverage that many owners overlook.
At Super Senior Services, we specialize in helping New York businesses navigate these complex waters. Whether you are a startup in Brooklyn or an established firm in Albany, this guide will walk you through five practical steps to secure affordable employee health coverage while keeping your business financially stable.
"Providing health insurance is an investment in your company’s most valuable asset: its people. When your team feels secure, your business thrives." : Stephen Jackson, Owner of Super Senior Services.
Step 1: Analyze Your Workforce and Define Your Budget
Before you dive into plan designs or carrier networks, you need a clear picture of your "Full-Time Equivalent" (FTE) count and your team's specific needs. In New York, the rules change depending on your size.
Determine Your FTE Count
Under the Affordable Care Act (ACA), if you have 50 or more FTEs, you are generally required to offer affordable, minimum essential coverage. However, if you have fewer than 50 FTEs, you are not legally mandated to provide health insurance. That said, most NY owners choose to offer it to stay competitive. Knowing your exact count is the first step because it determines which "buckets" of insurance you qualify for: such as the Small Business Marketplace (SHOP) or specific tax credits.
Understand Employee Priorities
Are your employees mostly young and healthy, or do they have families that require robust pediatric and specialist coverage?
- HMOs (Health Maintenance Organizations): Usually offer lower premiums but require staying within a specific network.
- PPOs (Preferred Provider Organizations): Offer more flexibility to see out-of-network doctors but come with higher monthly costs.
- HDHPs (High-Deductible Health Plans): Lower premiums paired with Health Savings Accounts (HSAs) can be a win-win for budget-conscious employers and employees looking for tax advantages.
By defining what you can realistically contribute (e.g., $400–$600 per employee per month), you can filter out plans that simply don't fit your bottom line.
Step 2: Leverage the NY State of Health (SHOP) and Federal Tax Credits
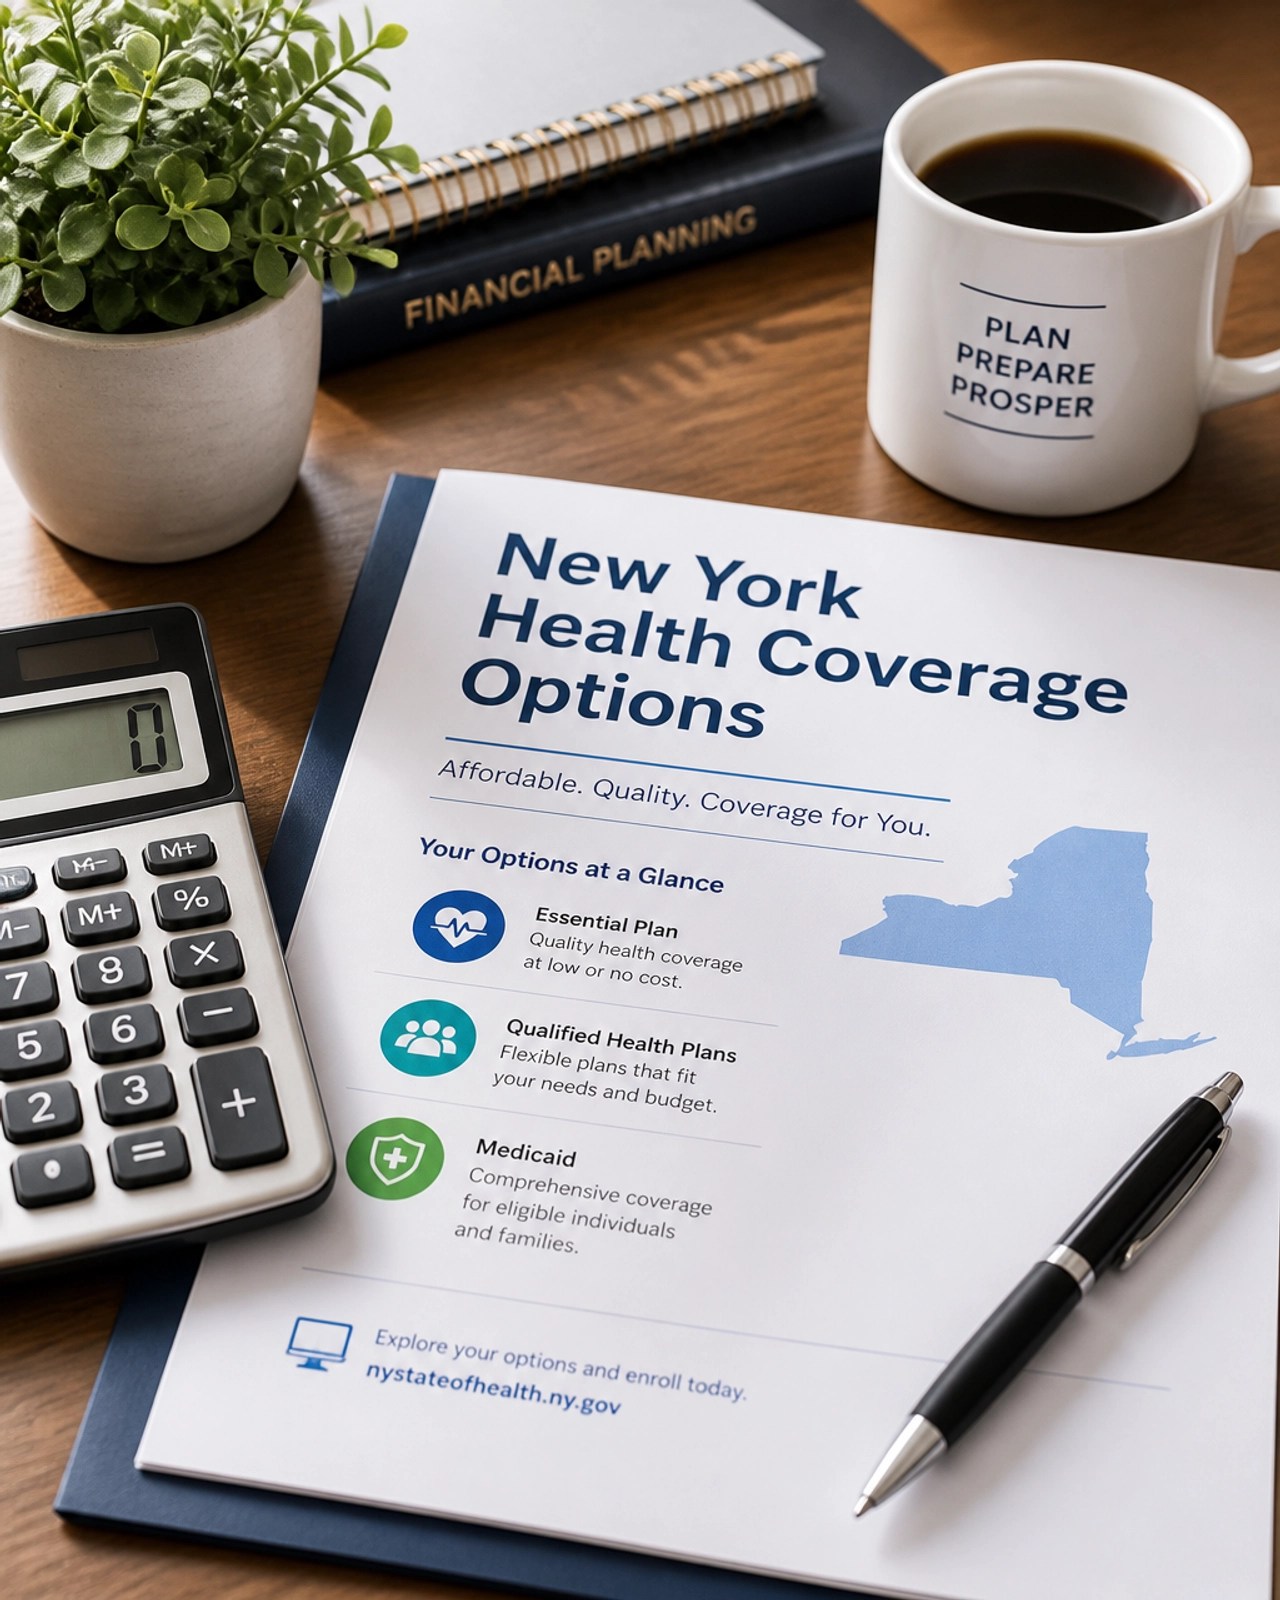
One of the most powerful tools for New York small business owners is the NY State of Health Small Business Marketplace (SHOP). This platform is specifically designed for employers with 1 to 100 employees.
The Federal Small Business Health Care Tax Credit (IRC §45R)
The single biggest reason to use the SHOP marketplace is the Small Business Health Care Tax Credit. If you qualify, this credit can refund up to 50% of your premium contributions (35% for tax-exempt organizations).
To be eligible for this credit in 2026, your business generally must:
- Have fewer than 25 full-time equivalent employees.
- Pay an average annual wage below a certain threshold (For 2025, this was approximately $67,000; the 2026 threshold is adjusted for inflation and can be confirmed via IRS.gov).
- Pay at least 50% of the premium cost for employee-only coverage.
- Purchase your coverage through a SHOP-certified plan.
Claiming this credit involves filing IRS Form 8941 with your taxes. It is a significant financial boost that can make "expensive" plans suddenly very affordable. You can learn more about the benefits of using the NY State of Health Marketplace for employers on our detailed resource page.
Step 3: Investigate Healthy NY for Subsidized Options
If your business has a lower-wage workforce and you haven't offered health insurance in the past 12 months, you might qualify for Healthy NY. This is a state-sponsored program designed to make insurance more accessible for small businesses.
Healthy NY Eligibility for 2026:
- Business Size: 1 to 50 FTEs.
- Wage Threshold: At least 30% of your eligible employees must earn $55,260 or less annually (based on 2026 projections).
- Participation: At least 50% of your eligible employees must enroll.
- Contribution: You must contribute at least 50% of the premium.
Healthy NY plans are standardized, meaning the benefits are consistent across different carriers, making it easier to compare prices. This program is an excellent "entry point" for businesses that want to start offering benefits without breaking the bank. For more details, the New York Department of Financial Services (DFS) provides updated annual guidelines on Healthy NY.
Step 4: Maximize Flexibility with Defined Contributions or HRAs
Traditional "group" plans aren't the only way to provide benefits. Many NY business owners are moving toward a Defined Contribution model. Instead of picking a specific plan for everyone, you give each employee a set dollar amount (a "stipend") to use toward a plan of their choice.
ICHRA and QSEHRA
- ICHRA (Individual Coverage Health Reimbursement Arrangement): This allows you to reimburse employees tax-free for their own individual health insurance premiums. This is fantastic because it caps your costs: you decide exactly how much you can afford to spend, and the employee chooses the plan that fits their life.
- QSEHRA (Qualified Small Employer Health Reimbursement Arrangement): Specifically for businesses with fewer than 50 employees, this offers similar tax-free reimbursement benefits with specific annual limits set by the IRS.
Using these arrangements can simplify your administration and eliminate the "participation requirements" that often plague traditional small-group plans. If you are unsure whether a group plan or an HRA is right for you, check out our guide on when to avoid the NY State of Health Marketplace to see if a private or HRA-based solution fits better.
Step 5: Partner with a Knowledgeable NY Expert
The landscape of New York health insurance changes every year. From updated wage thresholds for tax credits to new "mini-COBRA" rules (which require NY employers with 2–19 employees to offer up to 36 months of continuation coverage), there is a lot to track.
Trying to DIY your employee benefits can lead to missed tax credits or, worse, non-compliance with state regulations. A dedicated broker acts as your guide, helping you compare group rates through the NY State of Health against private market options like Oxford, EmblemHealth, or Anthem.
At Super Senior Services, we don't just hand you a brochure. We perform a comprehensive benefit review to ensure the plan you choose today will continue to serve your business as it grows. Our goal is to provide the transparency and trust you need to make an informed decision for your NY-based team.
Conclusion: Take Control of Your Employee Benefits
Offering affordable health insurance in New York is entirely possible when you have the right strategy. By evaluating your workforce, leveraging SHOP tax credits, exploring Healthy NY, and considering flexible HRA options, you can build a benefits package that makes your company a "magnet" for top talent while protecting your financial stability.
Don't navigate this alone. Whether you need a quick quote or a deep dive into the Small Business Health Care Tax Credit, we are here to help.
Ready to find the perfect plan for your New York business?
Contact Stephen Jackson at Super Senior Services today to schedule your personalized benefit review.
Super Senior Services (Individual NPN: 20707378 | Corporate NPN: 21536694) provides expert health insurance guidance exclusively for New York residents and businesses in the Business Health and Individual Health sectors.
{“name”:”How to Offer Affordable Employee Health Coverage in NY”,”step”:[{“name”:”Analyze Your Workforce”,”text”:”Determine your Full-Time Equivalent (FTE) count and assess the specific healthcare needs of your employees.”,”@type”:”HowToStep”},{“name”:”Leverage SHOP and Tax Credits”,”text”:”Use the NY State of Health Small Business Marketplace to access the Federal Small Business Health Care Tax Credit, which can cover up to 50% of premiums.”,”@type”:”HowToStep”},{“name”:”Investigate Healthy NY”,”text”:”Check eligibility for the state-subsidized Healthy NY program, specifically designed for lower-wage workforces.”,”@type”:”HowToStep”},{“name”:”Consider HRAs for Budget Control”,”text”:”Explore ICHRA or QSEHRA options to reimburse employees for individual plans with a fixed, defined contribution.”,”@type”:”HowToStep”},{“name”:”Partner with a NY Expert”,”text”:”Work with a licensed New York broker like Super Senior Services to navigate regulations and compare all available market options.”,”@type”:”HowToStep”}],”@type”:”HowTo”,”supply”:[{“name”:”Employee Census”,”@type”:”HowToSupply”},{“name”:”Business Tax Records”,”@type”:”HowToSupply”}],”@context”:”https://schema.org”,”totalTime”:”P1D”,”description”:”A 5-step guide for New York small business owners to find and implement affordable group health insurance while staying competitive.”,”estimatedCost”:{“@type”:”MonetaryAmount”,”value”:”Varies by plan”,”currency”:”USD”}}