As a New York small business owner, you wear a dozen hats every single day. From managing payroll and client relations to keeping your office or storefront running smoothly, you are the heartbeat of your enterprise. But when it comes to attracting and retaining top-tier talent in the Empire State, nothing speaks louder than a robust, comprehensive health insurance package.
Yet, looking at group health insurance quotes can often feel like sticker shock. You might find yourself wondering: How can I provide meaningful health coverage for my hardworking team without putting my company's financial stability at risk?
You are not alone in asking this. Navigating New York's insurance landscape requires strategy, knowledge of state-specific programs, and an understanding of how to maximize tax incentives. At Super Senior Services, we believe that exceptional employee benefits should be accessible to businesses of all sizes. Let’s dive into how you can secure affordable employee coverage in New York without breaking the bank.
1. Understanding New York's Small Group Landscape
Before choosing a plan, it helps to understand how New York defines a small business and what options are available to you. In New York, small group health insurance generally applies to employers with up to 100 employees.
When shopping for group coverage in NY, you essentially have two main avenues:
- The NY State of Health Small Business Marketplace (SBM): New York’s official marketplace allows small employers to compare plans, offer multiple options to employees, and: most importantly: unlock federal tax savings.
- Direct Carriers and Private Markets: You can also purchase group policies directly through major New York carriers like Empire BlueCross BlueShield, Oxford/UnitedHealthcare, CDPHP, and MVP Health Care, or through local chambers of commerce.
"Providing health benefits isn't just an expense; it's an investment in the people who build your business every single day. With the right guidance, NY business owners can find plans that fit both their employees' needs and their bottom line." : Stephen Jackson, Founder
2. Unlocking Savings with the Federal Small Business Health Care Tax Credit
One of the biggest pain points for employers is the cost of premiums. Fortunately, the federal government offers a powerful incentive: the Small Business Health Care Tax Credit.
To qualify for this credit through the NY State of Health Small Business Marketplace, your business generally must meet three key criteria:
- Have fewer than 25 full-time equivalent (FTE) employees.
- Pay average annual wages below a specific threshold (adjusted annually for inflation).
- Pay at least 50% of the premium cost for your employees' single coverage.
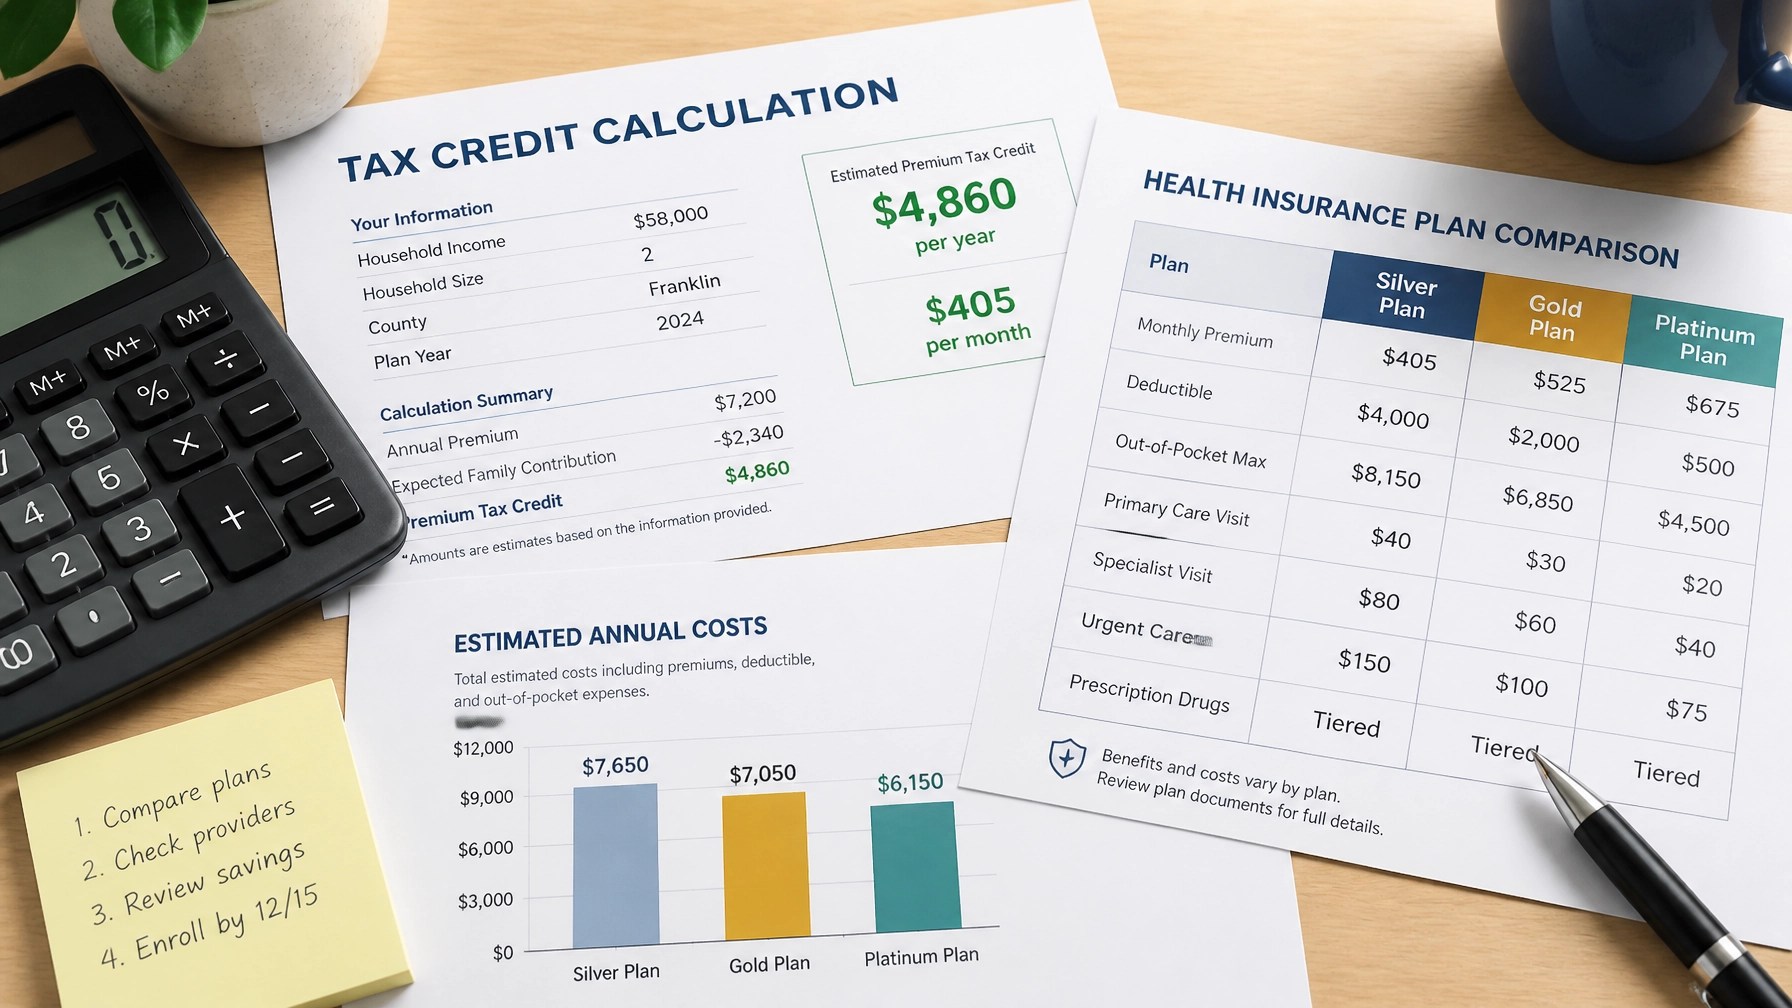
For qualifying small businesses, this credit can cover up to 50% of your premium contributions (up to 35% for tax-exempt organizations). Concurrently, this tax relief drastically lowers your net out-of-pocket expenses, making comprehensive coverage far more attainable.
3. Exploring the Healthy NY Program for Lower-Wage Workforces
If a significant portion of your workforce earns modest wages, you should look closely at the Healthy NY program. Supervised by the New York Department of Financial Services (DFS), Healthy NY is designed specifically to provide reduced-cost, comprehensive health insurance to small businesses.
Key highlights of Healthy NY include:
- Wage Thresholds: For small employers, at least 30% of eligible employees must earn wages at or below the 2026 threshold (e.g., $55,260 annually).
- Comprehensive Benefits: Essential health benefits: including inpatient and outpatient hospital care, physician services, preventive care, mental health services, and prescription drugs: are fully included.
- Carrier Participation: Healthy NY is delivered through partnering carriers across New York counties, providing structured affordability for businesses with tight margins.
By pairing Healthy NY options with expert benefit reviews, you can offer reliable safety nets for your staff while maintaining strict control over your monthly operational budget.
4. Smart Strategies to Control Costs Without Sacrificing Quality
You don't have to offer the most expensive platinum-tier plan on the market to keep your employees happy and healthy. Implementing strategic plan designs can significantly reduce monthly premiums while still providing robust protection:
- Offer High-Deductible Health Plans (HDHPs) with HSAs: Pairing an HDHP (such as single coverage premiums averaging $550–$850 per month) with a Health Savings Account allows employees to pay for routine medical expenses with pre-tax dollars.
- Choose Managed Care Networks wisely: HMO and EPO plans often feature lower monthly premiums than traditional PPO networks while maintaining access to top-tier hospital systems across New York.
- Establish a Defined Contribution Model: Instead of paying a fixed percentage of any plan an employee chooses, you can set a defined monthly contribution amount and let employees select the tier that best matches their personal health needs and budget.
5. Navigating Carrier Participation and Contribution Requirements
In New York, insurance carriers typically require a minimum employer contribution (often at least 50% of the single employee premium) and a minimum employee participation rate (usually around 75% of eligible, non-waiving employees) to issue small group coverage.
Meeting these rules can feel like a puzzle, especially if some of your workers are already covered under a spouse's plan or individual insurance. This is where expert guidance becomes invaluable. Working with knowledgeable professionals ensures your group application is structured correctly from day one, avoiding delays in coverage activation.
Partner with Super Senior Services for Your Business Coverage
Finding the right balance between affordability and comprehensive employee benefits doesn't have to be a solo journey. At Super Senior Services, we specialize in simplifying complex health insurance decisions for New York business owners. We help you compare trusted providers, evaluate tax credit eligibility, and craft tailored benefit solutions that protect your workforce and your bottom line.
Ready to find the ideal group health plan for your business? Visit our MedPlans and Consultation Page to schedule your personalized benefit review today!

Compliance and Licensing Information:
Individual NPN (Stephen Jackson): 20707378
Corporate NPN (Super Senior Services): 21536694
Super Senior Services provides specialized insurance services across New York.
{“@type”:”Article”,”author”:{“name”:”Stephen Jackson”,”@type”:”Person”},”@context”:”https://schema.org”,”headline”:”The NY Business Owner’s Guide to Affordable Employee Coverage Without Breaking the Bank”,”keywords”:”NY small business health insurance, group health coverage New York, Healthy NY, small business tax credit, Super Senior Services”,”publisher”:{“url”:”https://superseniorservices.com”,”name”:”Super Senior Services”,”@type”:”Organization”},”description”:”A comprehensive guide for New York small business owners on securing affordable group health insurance, utilizing tax credits, and navigating state-specific options.”,”mainEntityOfPage”:{“@id”:”https://superseniorservices.com/businesshealth/the-ny-business-owners-guide-to-affordable-employee-coverage”,”@type”:”WebPage”}}