If you were enrolled in New York’s Essential Plan with household income between 200% and 250% of the federal poverty level (FPL), July 1, 2026 marked an important change: that coverage category ended.
You are not alone. Approximately 450,000 New Yorkers are affected by this transition. The good news is that you still have options, including Qualified Health Plans (QHPs) through the New York State of Health Marketplace.
The key is taking action quickly. Your Essential Plan coverage may have ended on July 1, but New York created a Special Enrollment Period connected to this loss of coverage. State guidance says affected residents can enroll in new coverage before September 1, 2026.
Super Senior Services helps New York residents understand their choices, compare plans, and move forward with confidence.
What Changed on July 1?
New York’s Essential Plan has traditionally offered exceptionally affordable coverage, including:
- $0 monthly premiums
- No deductible
- Low copays for covered services
- Affordable prescription coverage
- Access to essential health benefits
However, beginning July 1, 2026, New York lowered the income eligibility limit for the Essential Plan from 250% FPL to 200% FPL. That means individuals and families above 200% FPL may no longer qualify for the same coverage.
The affected income ranges identified in New York guidance include:
- One-person household: approximately $31,920–$39,900
- Two-person household: approximately $43,280–$54,100
- Three-person household: approximately $54,640–$68,300
- Four-person household: approximately $66,000–$82,500
These figures apply to the 200%–250% FPL bracket and depend on household size and reported income.
If your income is now at or below 200% FPL, you may still qualify for the remaining Essential Plan coverage. You may also qualify for Medicaid or another public program if your circumstances have changed.
Your first step is to update your household and income information through New York State of Health. Super Senior Services can help you review the information and understand what it means for your coverage.
Understanding the “Coverage Cliff”
The phrase “coverage cliff” describes the sudden financial difference between the Essential Plan and a Qualified Health Plan.
Under the former Essential Plan category, you might have paid nothing each month and had very small copays. A QHP, by comparison, may include:
- A monthly premium (the amount you pay to keep coverage active)
- A deductible before the plan begins paying for many services
- Copays for doctor visits, urgent care, or prescriptions
- Coinsurance, meaning you pay a percentage of the cost after meeting the deductible
- An annual out-of-pocket maximum
For example, a QHP might have a premium of $50–$300 per month after financial assistance, a deductible of several thousand dollars, and prescription copays ranging from $10–$75 depending on the drug and formulary tier.
That can feel like a major jump. It is.
Still, the lowest monthly premium is not always the lowest overall cost. A plan with a $50 premium but a $7,000 deductible may cost more than a plan with a $150 premium and a lower deductible if you regularly see doctors, take prescriptions, or need ongoing treatment.
New York Attorney General Letitia James summarized the situation clearly:
“Losing health insurance can be stressful and confusing, and New Yorkers deserve clear, reliable information as they make decisions about their care.”
The right comparison looks at the entire cost structure: not just the premium. Super Senior Services simplifies that review so you can protect both your health and your financial stability.
Your Main Option: A Qualified Health Plan
A Qualified Health Plan is an Affordable Care Act Marketplace plan that meets federal requirements for essential health benefits and cost-sharing limits. As HealthCare.gov explains, QHPs cover important services such as doctor visits, hospital care, prescription drugs, preventive care, and emergency services.
You can shop for QHP coverage through NY State of Health. Losing your Essential Plan eligibility is considered a qualifying life event, which gives you a Special Enrollment Period.
According to New York guidance, affected residents can enroll before September 1, 2026. If you enroll during this window, you may also be able to receive coverage retroactive to July 1, depending on your eligibility and enrollment details.
Do not wait until the final days. Enrollment can require income information, household details, identity verification, and plan selection. Taking action now gives you more time to resolve questions and avoid an extended gap.
Super Senior Services can help you compare QHPs based on the factors that matter most to you:
- Your preferred doctors and hospitals
- Prescription medications
- Monthly budget
- Deductible and out-of-pocket maximum
- Copays and coinsurance
- HMO, PPO, EPO, or POS network structure
- Eligibility for premium tax credits and cost-sharing reductions
Contact Stephen Jackson for personalized help reviewing your next step.
Check for Financial Assistance Before Choosing a Plan
Many New Yorkers affected by the Essential Plan change may qualify for federal financial assistance through NY State of Health.
The Premium Tax Credit (PTC) can reduce your monthly premium. If applied in advance, it is called an Advanced Premium Tax Credit (APTC) and is sent directly to the insurance company to lower your monthly bill.
For example, if a plan costs $450 per month and you qualify for a $275 monthly tax credit, your estimated premium may fall to $175 per month.
You may also qualify for cost-sharing reductions (CSRs). These can lower deductibles, copays, and coinsurance when you enroll in an eligible Silver-level plan.
This is why it is important to compare plans through the Marketplace rather than assuming every QHP will cost the same. Your assistance amount depends on factors such as:
- Modified Adjusted Gross Income (MAGI)
- Household size
- Age
- County of residence
- Available plans in your area
- Whether you have access to affordable employer-sponsored coverage
You can learn more about premium assistance in Super Senior Services’ guide to the Premium Tax Credit.
A careful review may reduce your monthly premium substantially. It may also help you find a plan with more manageable out-of-pocket expenses.
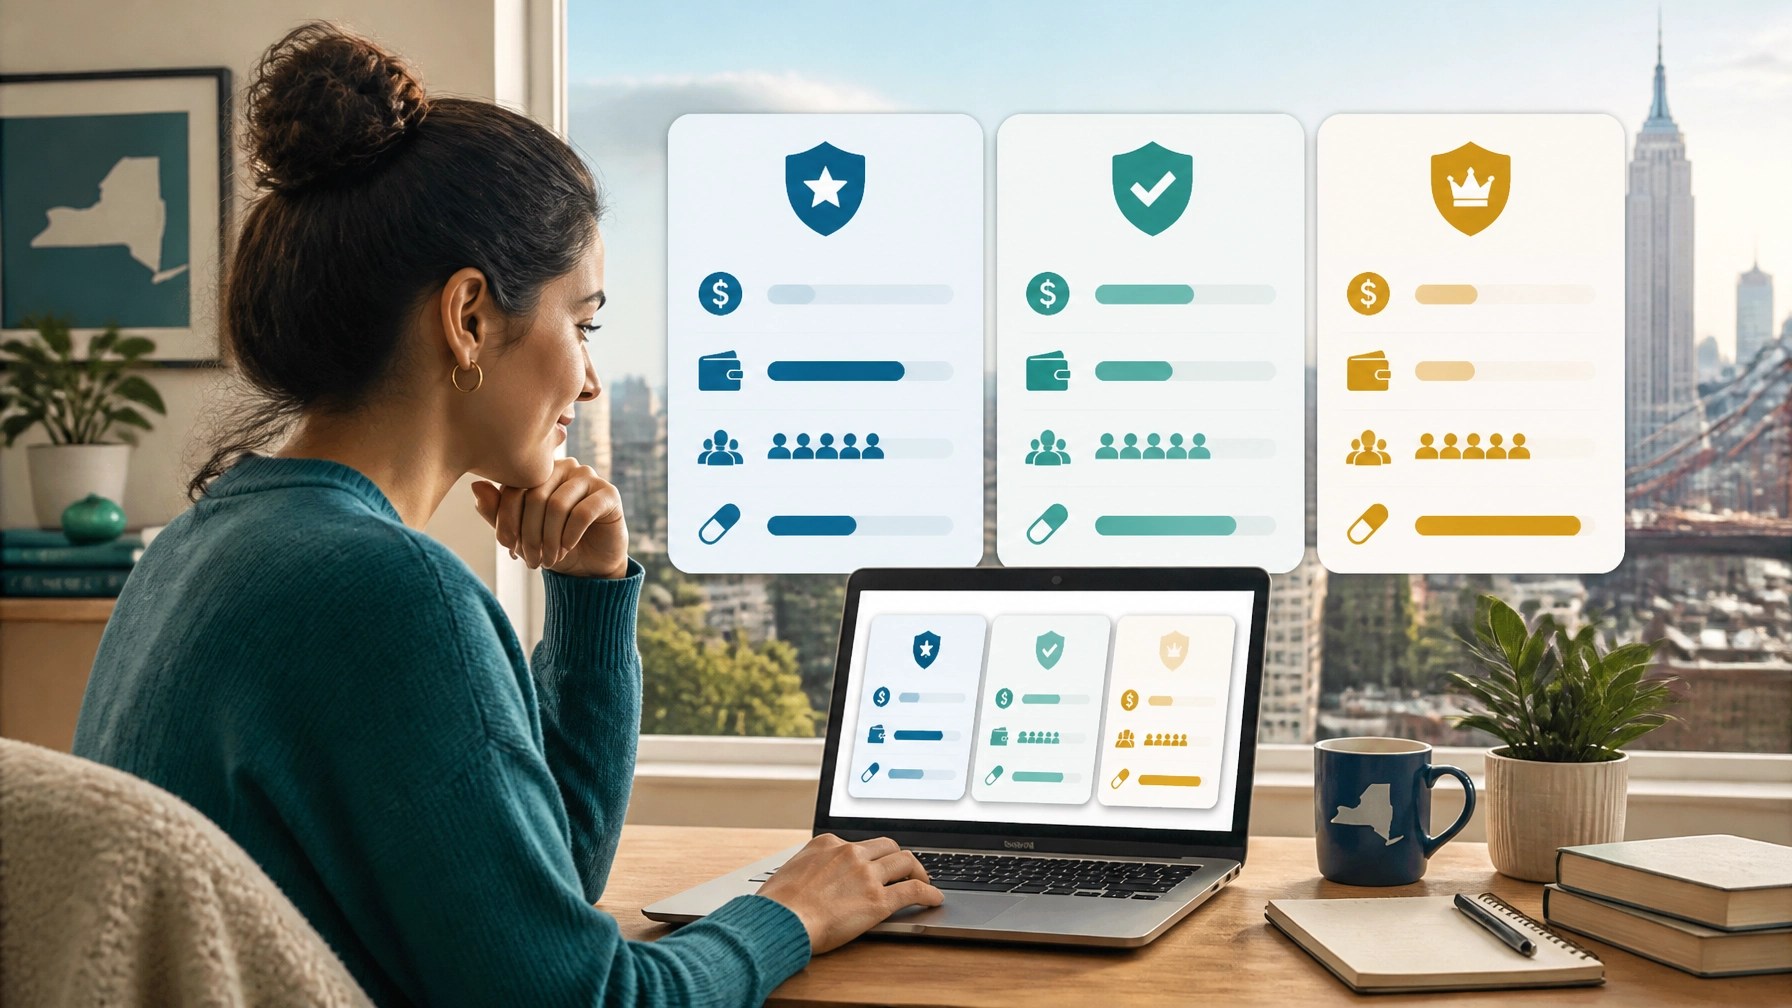
How to Compare QHPs Without Feeling Overwhelmed
A plan’s name or monthly premium does not tell the whole story. Before enrolling, review these five areas.
1. Provider network
Confirm that your primary care doctor, specialists, preferred hospitals, and urgent care centers participate in the plan’s network. An out-of-network visit may cost considerably more: or may not be covered for non-emergency care.
2. Prescription formulary
A formulary is the plan’s list of covered medications. Check whether your prescriptions are included and which tier they occupy. A generic drug may cost $10, while a specialty medication could involve much higher coinsurance.
3. Deductible
The deductible is what you pay for covered services before the plan begins sharing many costs. A $2,000 deductible and a $7,000 deductible can produce very different financial outcomes.
4. Copays and coinsurance
A copay is usually a fixed amount, such as $30 for a primary care visit. Coinsurance is a percentage, such as 20% of an outpatient procedure. Look at both.
5. Out-of-pocket maximum
This is the most you generally pay for covered in-network services during the plan year. Once you reach the limit, the plan pays 100% of covered in-network expenses for the remainder of that year.
Super Senior Services helps you connect these details to your real life. The goal is not simply to find a plan that looks affordable online. The goal is to find coverage that supports your doctors, prescriptions, budget, and peace of mind.
What to Do Now If Your Essential Plan Ended
As of August 15, 2026, the most important steps are straightforward:
-
Read every notice from NY State of Health.
Your notice should explain the change and may identify next steps for enrollment. -
Update your household and income information.
A lower income could make you eligible for the remaining Essential Plan category or Medicaid. -
Check your Special Enrollment Period.
The loss of Essential Plan coverage is a qualifying event, with enrollment available before September 1, 2026, according to New York guidance. -
Compare QHPs carefully.
Review premiums, deductibles, networks, formularies, copays, coinsurance, and out-of-pocket maximums. -
Ask about financial assistance.
Premium tax credits and cost-sharing reductions may make a QHP more affordable than you expect. -
Enroll as soon as possible.
Early action can help reduce the risk of a coverage gap and may support retroactive coverage back to July 1 when applicable.
You Have Options: and You Do Not Have to Navigate Them Alone
The Essential Plan change is significant, but it does not mean you are without choices. You may qualify for a different Essential Plan category, Medicaid, a subsidized QHP, or another form of individual health coverage available through New York State of Health.
The challenge is identifying which option offers the best balance of affordability, access, and protection.
Super Senior Services provides personalized guidance for New York residents affected by the July 1 transition. We simplify the comparison process, explain unfamiliar insurance terms, review your household circumstances, and help you evaluate coverage with confidence.
Your next plan should support your health today and your financial stability tomorrow.
Connect with Stephen Jackson to review your New York coverage options, or visit Super Senior Services to get started.
Compliance information: Individual NPN: Stephen Jackson : 20707378. Corporate NPN: Super Senior Services : 21536694.
Category: Individual Health Insurance
Category slug: individualhealth