Choosing Medicare coverage is an important decision: but it does not have to feel overwhelming. In 2026, you can choose between Medicare Advantage and Original Medicare paired with a Medicare Supplement Insurance policy, commonly called Medigap.
Both approaches can provide valuable protection. The right choice depends on your doctors, prescriptions, travel habits, budget, preferred way of receiving care, and comfort with copayments or monthly premiums.
This guide explains the major differences, highlights important 2026 updates, and walks you through the enrollment timeline so you can move forward with confidence.
Medicare coverage is available through Super Senior Services for residents of Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, and New York State.
Medicare Advantage vs. Medigap: The basic difference
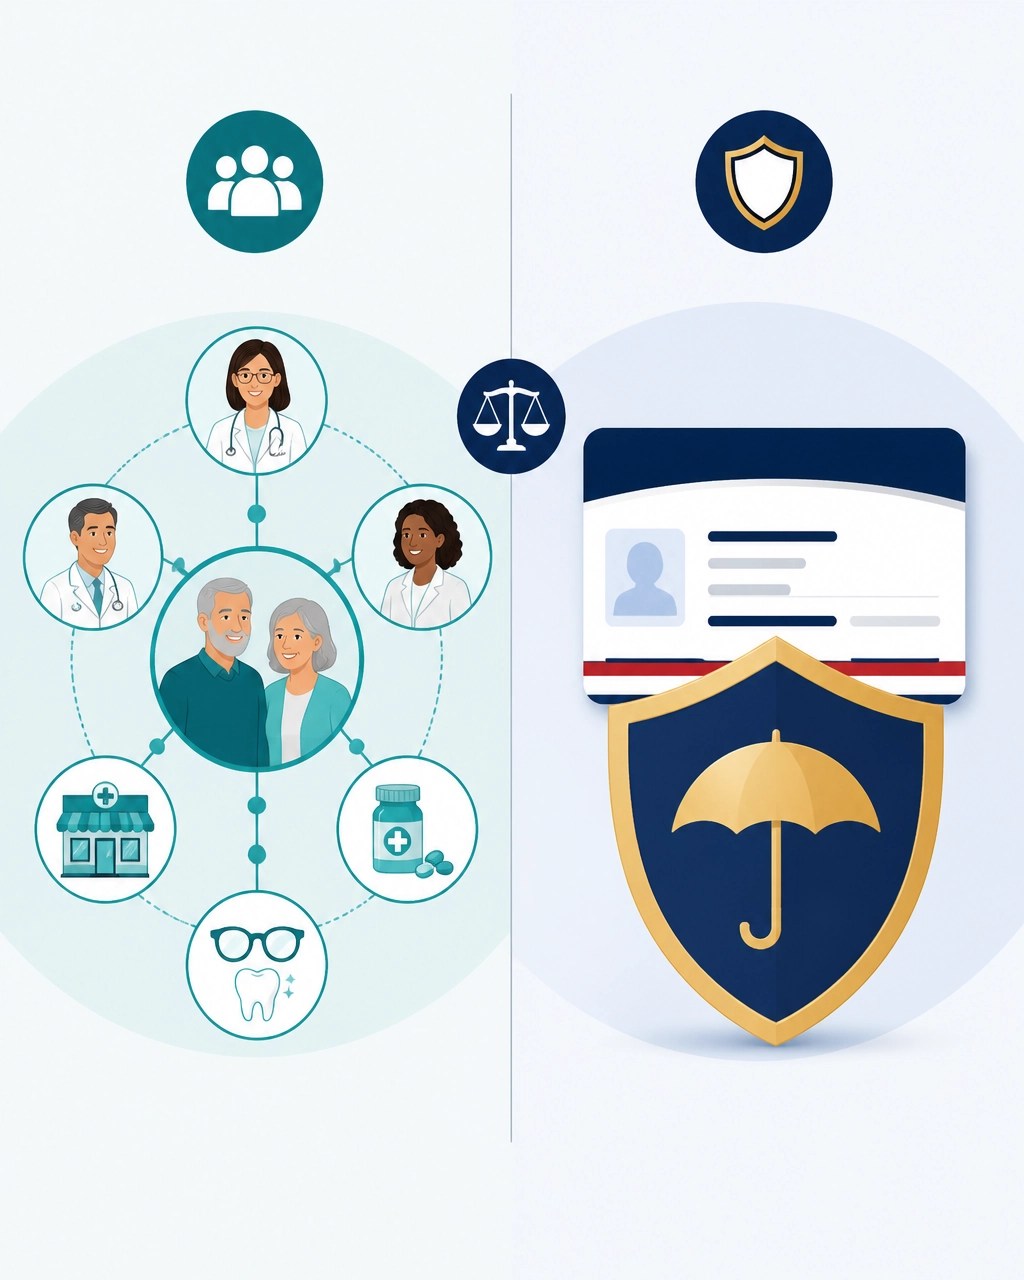
Medicare Advantage, also called Part C, is an alternative way to receive your Medicare Part A and Part B benefits through a private insurance company approved by Medicare. Most Medicare Advantage plans also include Part D prescription drug coverage.
Medigap works differently. You keep Original Medicare, use any Medicare-participating provider in most cases, and purchase a private Medicare Supplement policy to help pay certain deductibles, coinsurance, and copayments.
Here is the simplest way to think about the options:
- Medicare Advantage: A bundled plan with a provider network, defined copayments, prescription coverage in most plans, and a yearly out-of-pocket limit.
- Original Medicare plus Medigap: Broad provider access through Original Medicare, a separate supplement premium, and help with many Part A and Part B cost-sharing expenses.
- Part D: Prescription drug coverage must be included through a Medicare Advantage plan or purchased separately when you have Original Medicare and Medigap.
The best option is not necessarily the plan with the lowest premium. It is the plan that fits your healthcare needs and protects your financial stability.
What is changing for Medicare Advantage in 2026?
Medicare Advantage continues to offer predictable cost-sharing and additional benefits, but plan details vary significantly by county and provider network. The Centers for Medicare & Medicaid Services (CMS) and Medicare.gov provide official plan and cost information.
Several 2026 figures are especially important:
- The average Medicare Advantage plan premium is approximately $14 per month. Many plans have a $0 plan premium, but you generally must continue paying your Medicare Part B premium.
- About 32% of individual Medicare Advantage plans offer a Part B premium reduction, averaging approximately $31 per month. These “giveback” benefits are plan-specific and may reduce the amount deducted from your Social Security benefit.
- The average in-network out-of-pocket limit is approximately $5,421 for covered Part A and Part B services. A plan may have a lower or higher limit, so you should review the plan’s Evidence of Coverage.
- The 2026 Part D out-of-pocket cap is $2,100 for covered prescription drugs. Once you reach that limit, you generally pay no additional copayments or coinsurance for covered Part D drugs for the rest of the calendar year.
- The standard Part B premium is $202.90 per month in 2026, although income-related adjustments may cause some beneficiaries to pay more.
These figures show why comparing only the monthly premium can be misleading. A $0-premium plan may still have copayments, coinsurance, prior authorization requirements, and network restrictions. Conversely, a plan with a monthly premium may offer lower costs for your doctors, hospitals, or prescriptions.
Check your providers and medications first. A plan’s formulary: the list of covered prescription drugs: can affect your annual spending by hundreds or thousands of dollars (for example, a drug may cost $10 at one tier and $50 or more at another).
Medicare Advantage: When a coordinated plan may fit
Medicare Advantage plans may be a good fit if you prefer bundled coverage and want additional benefits beyond Original Medicare. Many plans include dental, vision, hearing, fitness, transportation, or over-the-counter benefits, although limits and eligibility rules apply.
You may also appreciate:
- A yearly maximum on covered Part A and Part B out-of-pocket costs
- Copayments that are easier to estimate for office visits and services
- Prescription coverage included in most plans
- Potential Part B premium reductions (up to the plan’s stated amount)
- Care coordination through a primary care provider
However, Medicare Advantage plans generally use provider networks. Health Maintenance Organization (HMO) plans may require you to use in-network providers except for emergencies, urgent care, or other approved situations. Preferred Provider Organization (PPO) plans may cover out-of-network care at a higher cost.
Some services and prescriptions may also require prior authorization, which means the plan must approve the service before coverage applies.
Before enrolling, confirm:
- Your primary care doctor and specialists participate.
- Your preferred hospitals and pharmacies are in network.
- Your prescriptions appear on the plan’s formulary.
- Your copayments and coinsurance fit your expected healthcare use.
- The plan’s in-network out-of-pocket limit is manageable.
Super Senior Services can simplify this comparison by reviewing your doctors, medications, budget, and preferred benefits together: not separately.
Medigap: When flexibility and predictable cost-sharing matter
Medigap policies help pay certain costs left by Original Medicare, such as Part A coinsurance, Part B coinsurance, and: in some plans: deductibles.
Medigap policies are standardized by letter. In most states, available plan letters include A, B, C, D, F, G, K, L, M, and N. A Plan G from one insurance company generally provides the same standardized benefits as a Plan G from another company, although premiums, pricing methods, customer service, and underwriting rules can differ.
Medigap plans do not generally include prescription drug coverage. If you choose Original Medicare and Medigap, you will usually need a separate Part D plan.
Plan availability has important rules:
- Plans C and F generally are not available to people who became newly eligible for Medicare on or after January 1, 2020 because newer beneficiaries cannot purchase coverage for the Part B deductible.
- Plan G is often considered by people who want broad cost-sharing protection but understand that they must pay the Part B deductible themselves.
- Plan N may have a lower premium but can include copayments for certain office or emergency room visits and may not cover Part B excess charges.
- Medigap premiums vary based on the plan letter, where you live, age, pricing method, and other factors.
Your six-month Medigap Open Enrollment Period
Your strongest federal Medigap protection usually begins when you are 65 or older and enrolled in Medicare Part B. From that date, you have a one-time six-month Medigap Open Enrollment Period.
During this period, you generally have a guaranteed right to buy any Medigap policy sold in your state. Insurers generally cannot deny coverage or charge more because of health problems.
This window is personal to you. It is not the same as Annual Enrollment in the fall, and it does not automatically repeat every year.
You may also have guaranteed-issue rights in certain circumstances, such as losing qualifying coverage, moving out of a plan’s service area, or using a Medicare Advantage trial right. State rules can provide additional protections. Because switching from Medicare Advantage to Medigap later may involve medical underwriting, review your options carefully before dropping an existing supplement policy.
Read the official Medicare Medigap guidance before making a change.
“The best time to buy a Medigap policy is during your Medigap Open Enrollment Period.” : Medicare & You 2026
Your 2026 Medicare enrollment checklist
Understanding the dates helps you avoid gaps in coverage and late-enrollment penalties.
1. Initial Enrollment Period
Your Initial Enrollment Period is generally a seven-month window:
- Three months before the month you turn 65
- Your birthday month
- Three months after your birthday month
If you are already receiving Social Security or Railroad Retirement Board benefits, you may be automatically enrolled in Part A and Part B. If not, apply through Social Security.
This is also the time to evaluate Medicare Advantage, Medigap, and Part D options. Starting early gives you time to verify doctors, pharmacies, formularies, premiums, and effective dates.
2. General Enrollment Period
The General Enrollment Period runs from January 1 through March 31 each year. It is generally available to people who did not enroll in Part A or Part B when first eligible and do not qualify for a Special Enrollment Period.
Coverage typically starts the month after you enroll. Delaying Part B may also lead to a late-enrollment penalty: often 10% for each full 12-month period you could have had Part B but did not enroll.
3. Medicare Advantage Open Enrollment Period
The Medicare Advantage Open Enrollment Period runs from January 1 through March 31.
If you are already enrolled in Medicare Advantage, you can:
- Switch to another Medicare Advantage plan, or
- Return to Original Medicare and join a separate Part D plan
You can generally make one change during this period. This period does not allow someone in Original Medicare to enroll in Medicare Advantage for the first time.
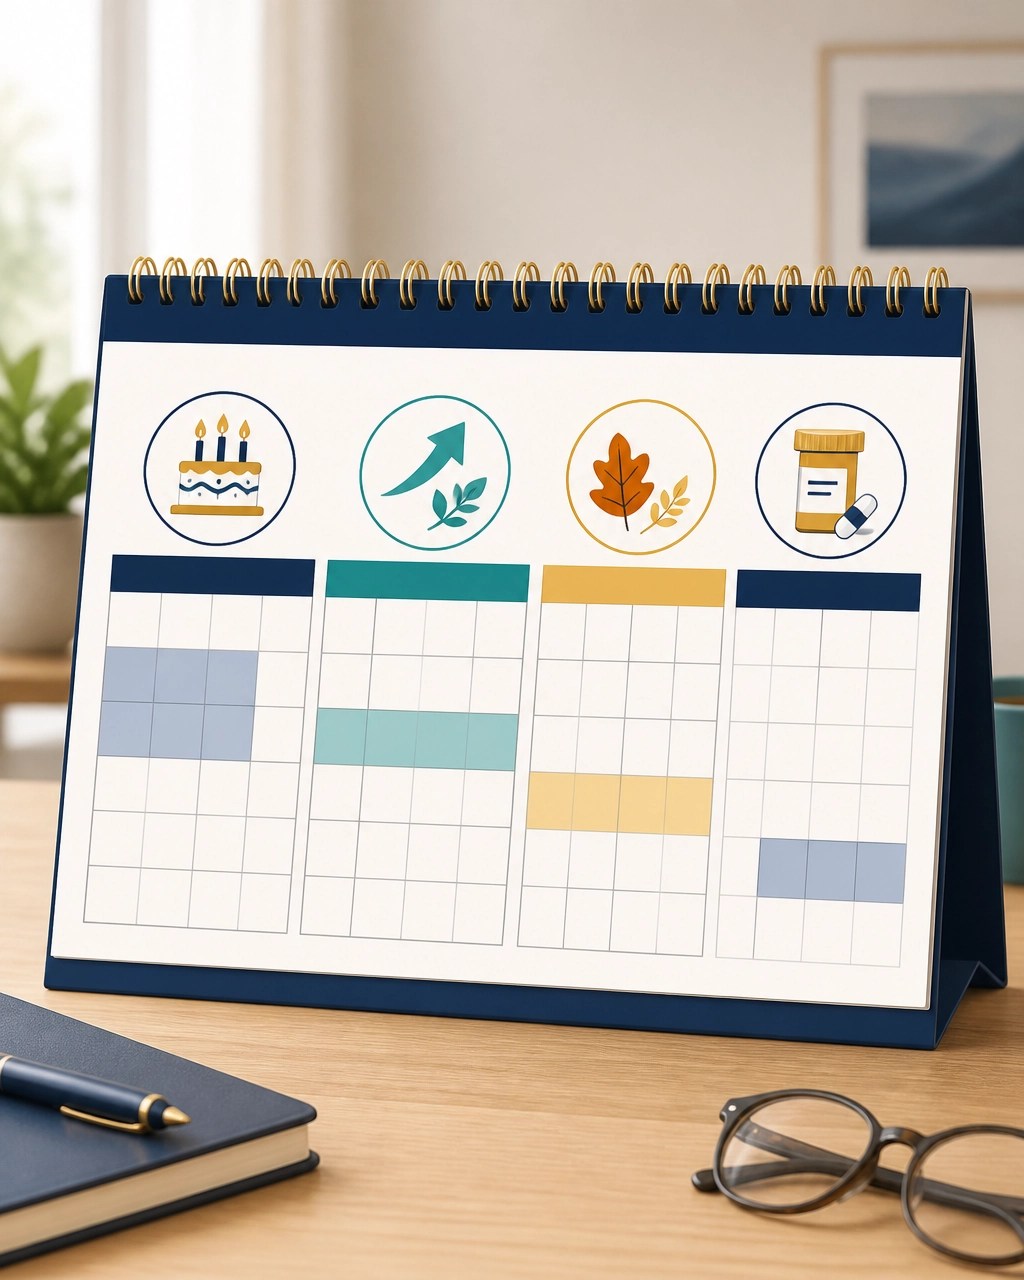
4. Annual Enrollment Period
The Annual Enrollment Period is October 15 through December 7 each year. During this time, you can:
- Join, change, or drop a Medicare Advantage plan
- Join, change, or drop a Part D plan
- Switch from Medicare Advantage to Original Medicare
- Switch from Original Medicare to Medicare Advantage
Changes generally take effect January 1 of the following year.
Review your plan’s Annual Notice of Change and Evidence of Coverage before deciding. Benefits, premiums, provider networks, formularies, and cost-sharing can change from one year to the next.
5. Watch for the Part D late-enrollment penalty
If you go 63 days or longer without Part D or other creditable prescription drug coverage after becoming eligible, you may owe a permanent late-enrollment penalty when you join later.
Creditable coverage means prescription coverage expected to pay, on average, at least as much as standard Medicare drug coverage. Employer or union coverage, TRICARE, Veterans Affairs coverage, and certain other coverage may qualify.
In 2026, the Part D late-enrollment penalty is calculated using 1% of the national base beneficiary premium of $38.99 for each full uncovered month. For example, 12 uncovered months could produce a penalty of about $4.70 per month, added to your Part D premium and generally continuing as long as you have drug coverage.
Keep notices showing whether your existing prescription coverage is creditable.
How to enroll with confidence
A confident Medicare decision starts with a complete review, not a rushed selection. Gather your Medicare card, medication list, preferred doctors, pharmacy information, estimated healthcare expenses, and travel plans.
Then compare:
- Monthly premiums, including Part B and any plan premium
- Deductibles, copayments, and coinsurance
- Provider and hospital networks
- Prescription formularies and pharmacy tiers
- Prior authorization and referral rules
- Dental, vision, hearing, and other supplemental benefits
- Annual out-of-pocket limits
- Medigap Open Enrollment or guaranteed-issue eligibility
Medicare.gov’s Plan Compare tool is an excellent starting point. You can also review official costs through Medicare.gov, enrollment information through SSA.gov, and Medicare Advantage policy information through CMS.gov.
Super Senior Services adds the personal guidance many people need. We help Medicare beneficiaries compare trusted providers in their area, identify affordable options, review formularies, and understand how a plan may affect both health and household finances. We also offer annual reviews so your coverage can keep pace with changing prescriptions, providers, benefits, and priorities.
“Review your health and drug coverage each year. Make sure it still meets your needs.” : Medicare & You 2026
Get personalized Medicare guidance
Whether you are approaching 65, comparing Medicare Advantage and Medigap, or reviewing your current plan for 2026, you do not have to navigate the process alone.
Super Senior Services provides Medicare guidance for residents of Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, and New York State. Our approach is personal, transparent, and focused on affordability, excellence, financial stability, and peace of mind.
Compare Medicare plans and get started
You can also contact Stephen Jackson and the Super Senior Services team for help reviewing your options.
WordPress category: medicare
Publishing compliance record
- Individual NPN : Stephen Jackson: 20707378
- Corporate NPN : Super Senior Services: 21536694