If you live in New York and your household income sits between 200% and 250% of the Federal Poverty Level (FPL), the ground beneath your health coverage shifted dramatically on July 1, 2026.
The expiration of New York’s federal Section 1332 waiver triggered what policy experts and advocates call the Essential Plan cliff. According to recent reports from silive.com, this sudden change has impacted nearly 500,000 New Yorkers who previously enjoyed $0-premium, $0-deductible coverage. Now, transitioning away from the Essential Plan means facing unfamiliar health insurance choices, potential gaps in coverage, and unexpected out-of-pocket costs: including reports of promised deductible reductions falling through for everyday residents (such as recent local news coverage by 13WHAM highlighting a Bloomfield woman's frustrating struggle with unfulfilled deductible adjustments).
Navigating this transition alone can feel overwhelming. But you don't have to guess your way through it. At Super Senior Services, we specialize in guiding New York individuals through complex healthcare shifts, helping you secure affordable coverage, avoid costly pitfalls, and protect your hard-earned savings.
Here is everything you need to know about the Essential Plan cliff, the three Qualified Health Plan (QHP) options available to you, and why acting before the August 30 special enrollment deadline is critical.
What Is the Essential Plan Cliff and Who Does It Affect?
For the past couple of years, New York’s Essential Plan welcomed individuals earning up to 250% FPL: providing peace of mind with zero monthly premiums and zero deductibles.
However, as of July 1, 2026, eligibility rolled back strictly to those under 200% FPL (roughly $31,920 a year for an individual, or $43,280 for a two-person household). If your income falls in the 200% to 250% FPL band (e.g., roughly $31,920 to $39,900 for a single filer), your Essential Plan coverage officially ended on June 30, 2026.
The Hidden Financial Shock: Deductibles and Broken Promises
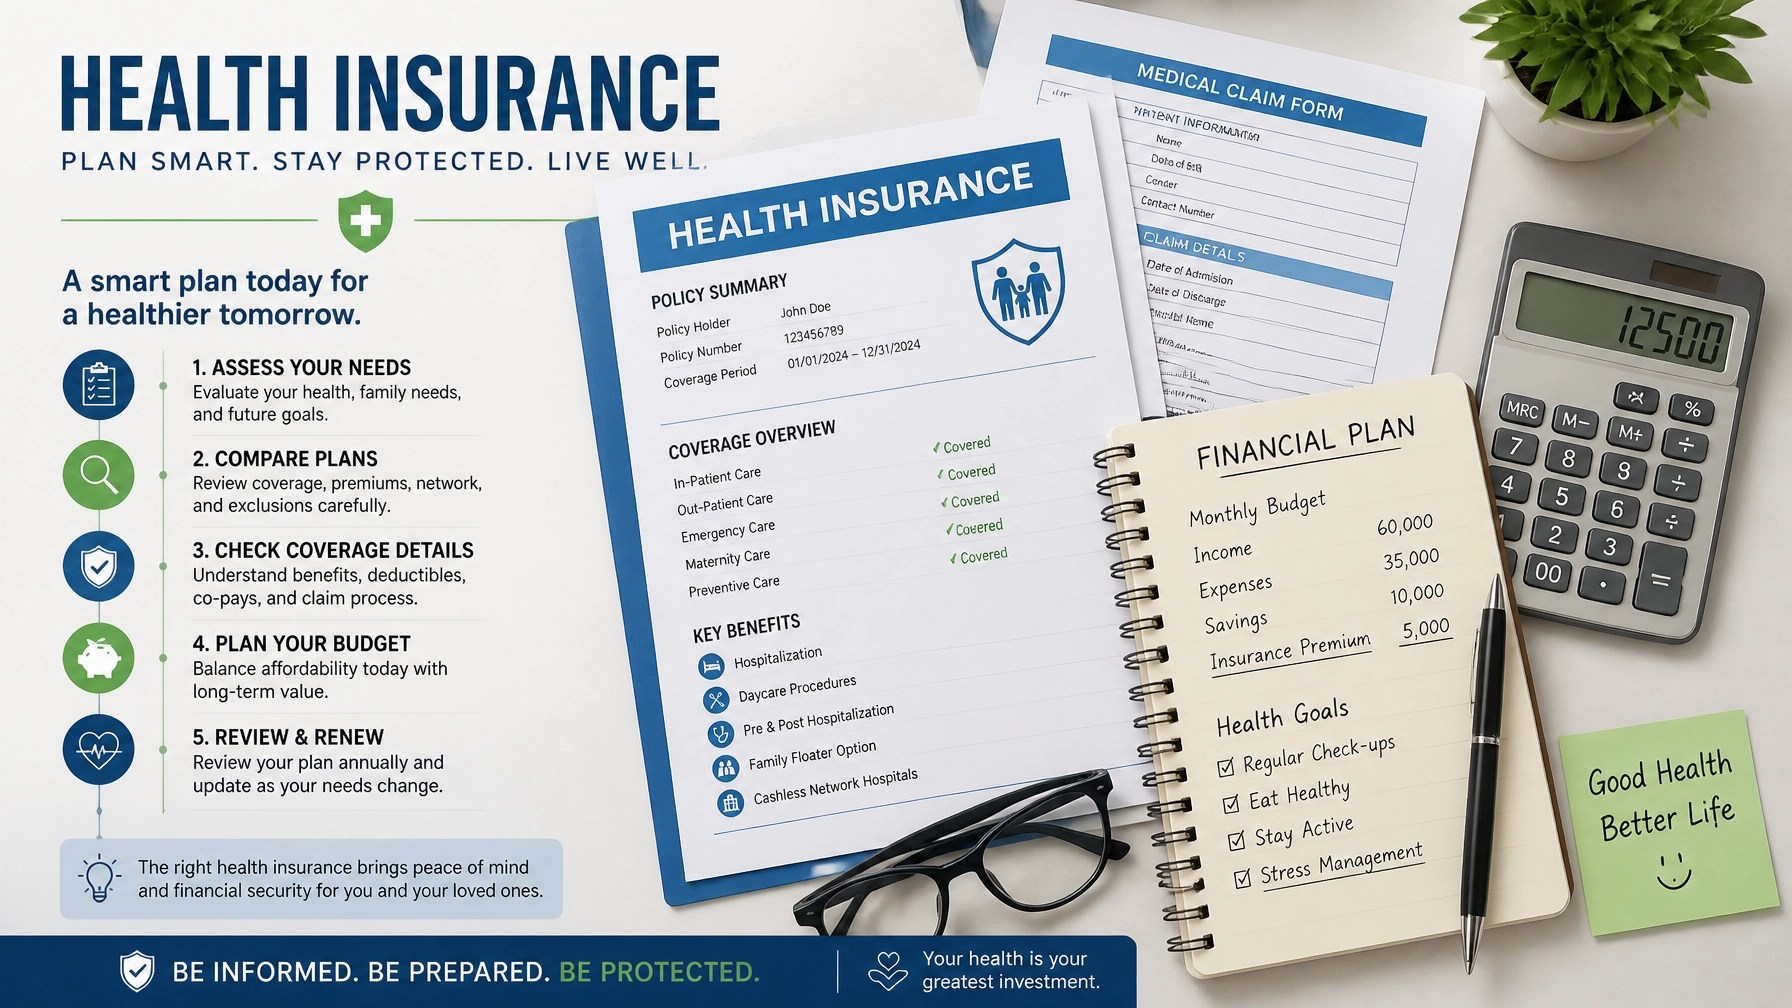
When moving from the Essential Plan to an ACA Marketplace Qualified Health Plan (QHP), the biggest shock isn't just the monthly premium: it's the deductible. While the Essential Plan had a $0 deductible, standard Marketplace Silver plans often come with deductibles around $2,500 before insurance begins sharing major medical costs [3].
Compounding the anxiety, recent investigative reports (such as the July 27, 2026 report by 13WHAM featuring a Bloomfield resident) have exposed frustrating instances where promised state or carrier deductible-reduction credits weren't honored seamlessly at enrollment. Without expert advocacy, policyholders risk being billed for thousands in out-of-pocket medical expenses they never anticipated.
The 3 Qualified Health Plan (QHP) Options for NY Residents
When you step off the Essential Plan cliff, the New York State of Health Marketplace offers three primary metal tiers of Qualified Health Plans (QHPs) backed by federal tax credits to lower your monthly costs. Understanding how each tier works financially is essential to safeguarding your budget.
1. Bronze Plans: The Low-Premium, High-Deductible Choice
- Monthly Premiums: Typically the lowest available, often $0 to modest monthly amounts after subsidies.
- Deductibles & Out-of-Pocket Costs: High: often ranging from $6,000 to over $9,000 before comprehensive coverage kicks in.
- Best For: Healthy individuals who rarely visit the doctor, take zero regular prescription drugs, and primarily want catastrophic financial protection in case of an emergency or severe accident.
- The Catch: If you need routine medical care, specialist visits, or diagnostic tests, you will pay out-of-pocket until your high deductible is met.
2. Silver Plans: The Balanced, Subsidized Option (Most Popular)
- Monthly Premiums: Moderate, heavily offset by advanced premium tax credits for those transitioning off the Essential Plan.
- Deductibles & Out-of-Pocket Costs: Moderate (frequently averaging around $2,500 for those in the 200-250% FPL bracket, though Cost-Sharing Reductions (CSRs) can significantly lower copays and deductibles if selected correctly) [3].
- Best For: Most individuals and families who see doctors regularly, manage chronic conditions, or rely on routine prescriptions.
- The Value: Silver plans are the only tier eligible for Cost-Sharing Reductions (CSRs), which directly lower your copaxes, coinsurance, and deductibles if your income qualifies.
3. Gold Plans: The Comprehensive, Low-Deductible Coverage
- Monthly Premiums: Higher monthly costs, as fewer subsidies apply to the higher premium base.
- Deductibles & Out-of-Pocket Costs: Very low: often $500 to $1,500, with immediate copays (e.g., $10–$30 per doctor visit) before meeting a deductible.
- Best For: Individuals with predictable, high-volume medical needs, expensive prescription drugs, or upcoming scheduled surgeries.
- The Value: You pay more upfront every month, but your out-of-pocket exposure during medical events is drastically reduced.
Why Acting Before August 30 Matters
Time is of the essence. New York State has established a critical Special Enrollment Period (SEP) deadline of August 30, 2026 for residents affected by the Essential Plan cliff.
Acting by August 30 ensures that:
- Retroactive Coverage: Your new QHP coverage can bridge the gap back to July 1, preventing dangerous uninsured periods.
- Avoid Penalties & Gaps: You secure financial stability and avoid unexpected medical bills from July and August doctor visits.
- Correct Subsidy Application: You lock in the exact tax credits and Cost-Sharing Reductions you are legally entitled to.
How Super Senior Services Guides You Through the Maze
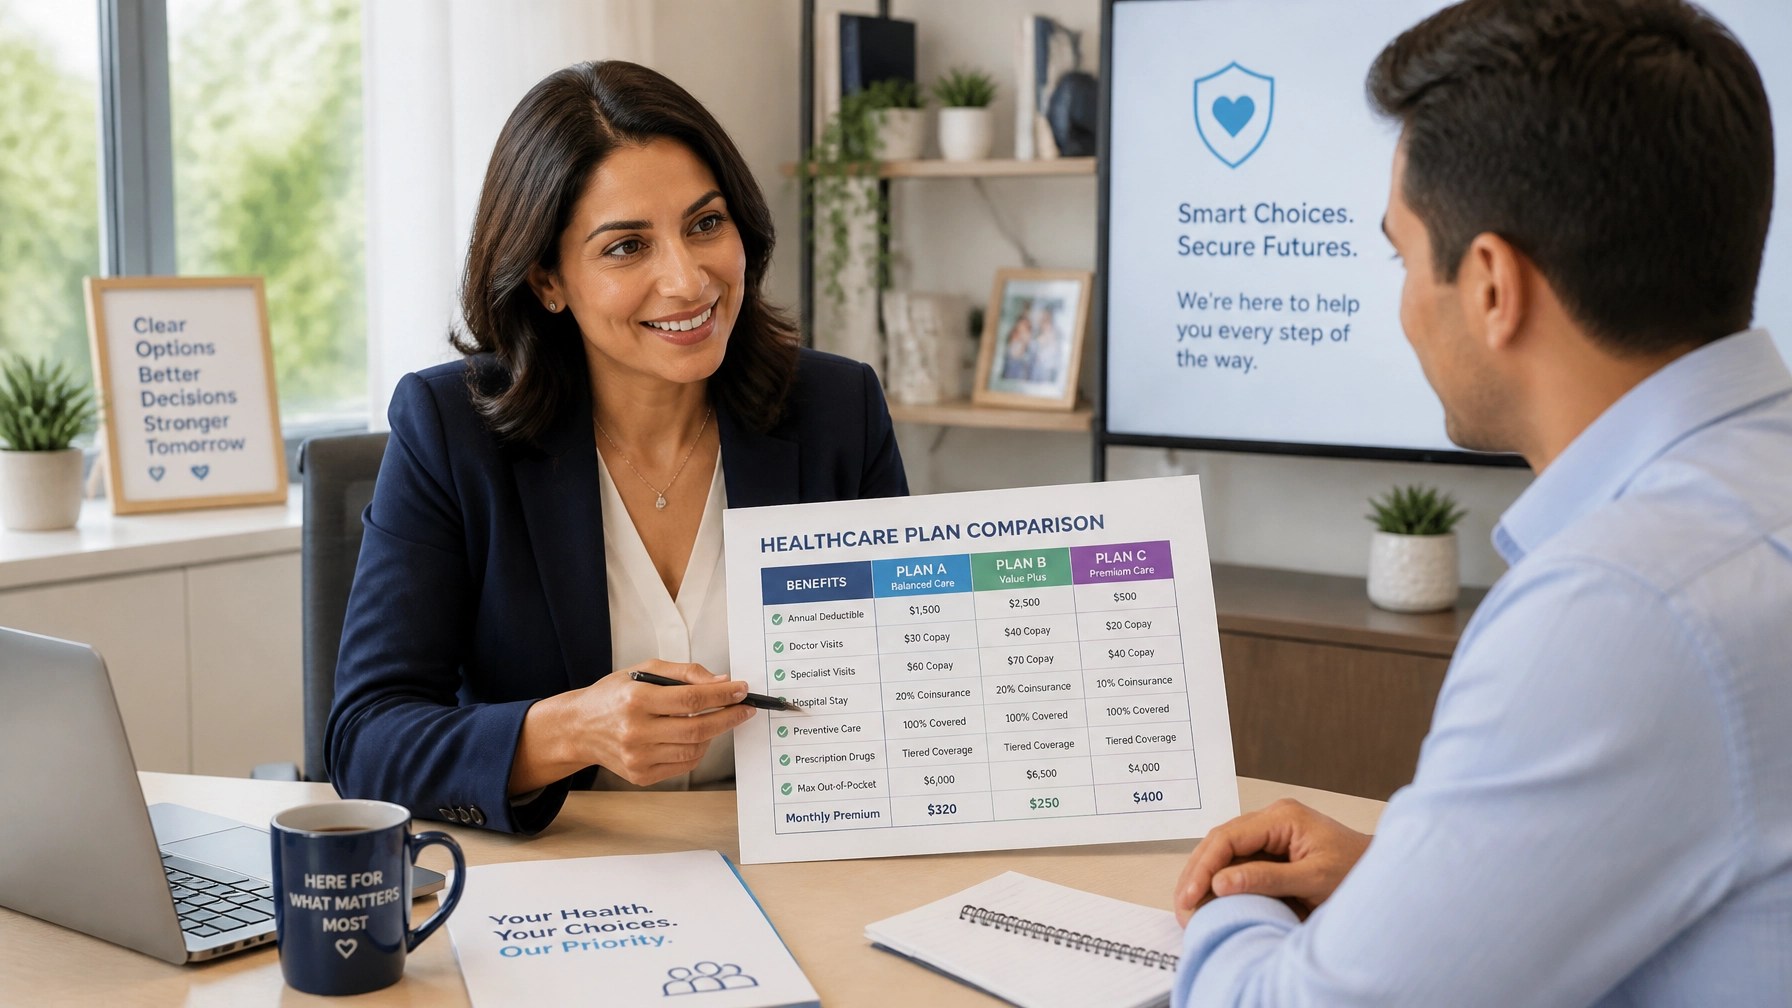
Navigating insurance jargon like "formularies," "coinsurance," and "CSRs" shouldn't feel like a second job. That is where Super Senior Services steps in as your trusted partner.
We pride ourselves on offering:
- Personalized Plan Reviews: We analyze your specific doctors, prescription medications, and health history to match you with the right QHP metal tier.
- Transparent Guidance: No hidden surprises or unhonored promises: we verify every deductible and subsidy detail directly with trusted carriers in your local New York area.
- Dedicated Ongoing Support: As your healthcare needs evolve year after year, we ensure your coverage adapts right along with you.
"Excellence and peace of mind are at the core of everything we do. We turn complex healthcare transitions into clear, actionable savings for your family."
Secure Your New York Health Coverage Today
The Essential Plan cliff doesn't have to mean breaking your budget or risking your health coverage. With expert guidance and a clear strategy, you can find a Qualified Health Plan that balances affordable premiums with manageable deductibles.
Don't wait until the August 30 deadline sneaks up on you. Let our licensed experts review your options and secure your peace of mind today.
👉 Click here to explore your NY health plan options with Super Senior Services today!
{“@type”:”Article”,”author”:{“name”:”Penny”,”@type”:”Person”},”@context”:”https://schema.org”,”headline”:”Essential Plan Cliff: 3 Qualified Health Plan Options for NY Residents (Save Thousands Before August 30)”,”publisher”:{“url”:”https://superseniorservices.com”,”name”:”Super Senior Services”,”@type”:”Organization”},”description”:”Learn how the July 1, 2026 New York Essential Plan cliff impacts residents earning 200-250% FPL. Explore Bronze, Silver, and Gold QHP options and enroll before August 30.”,”mainEntityOfPage”:”https://superseniorservices.com/individualhealth/essential-plan-cliff-3-qualified-health-plan-options-ny-residents”}