WordPress category: finalexpense
Planning for end-of-life expenses can feel uncomfortable, but understanding your options does not have to be complicated. Final expense insurance for seniors is designed to help your family manage funeral, burial, cremation, cemetery, transportation, and other final bills without relying entirely on savings.
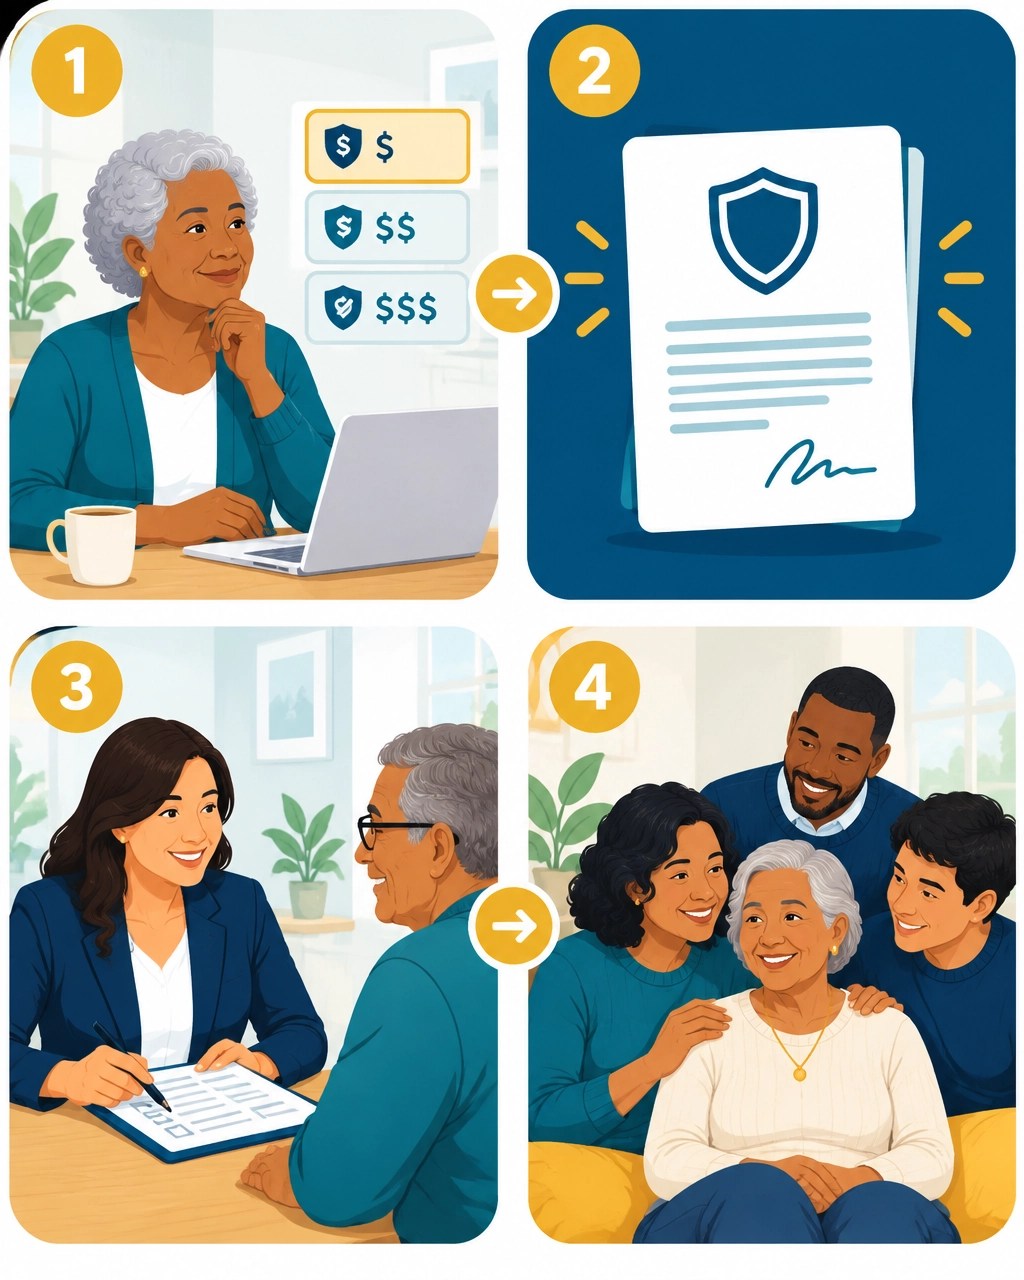
The process is easier when you break it into steps. You choose an appropriate coverage amount, compare premium options, apply through a simplified process, and make sure your beneficiary knows what to do when the time comes.
That is the goal of this guide: simple answers, practical examples, and more peace of mind for you and your family.
What Is Final Expense Insurance?
Final expense insurance is usually a small whole life insurance policy intended to provide a death benefit when you pass away. Many policies offer coverage amounts from approximately $5,000 to $25,000, although available amounts vary by carrier, age, health, and state.
Your beneficiary can generally use the benefit for eligible expenses such as:
- Funeral home services and professional fees
- Burial or cremation expenses
- Cemetery plots, opening and closing fees, or grave liners
- Headstones, urns, or memorial services
- Transportation of remains, including long-distance transportation
- Outstanding medical bills, household expenses, or other final obligations
Unlike a prepaid funeral contract, the insurance benefit is typically paid to your named beneficiary, who can use the money according to the policy terms and your family’s needs. That flexibility can be valuable when costs change or several bills arrive at once.
The National Funeral Directors Association reports a 2023 national median of $8,300 for an adult funeral with viewing and burial, excluding the burial vault and cemetery charges. With a median burial vault cost of $1,695, the combined median reaches approximately $9,995. NFDA explains that a median is the amount “at which half of the figures fall below and half are above.” See the NFDA Cremation and Burial Report.
Final expense coverage 2026 can help your family address these costs without immediately liquidating savings or asking relatives to contribute.
Step 1: Decide What You Want the Policy to Cover
Start with a practical estimate rather than choosing a random amount. Ask yourself:
- Do you prefer burial, cremation, or another arrangement?
- Do you already own a cemetery plot or niche?
- Will family members need to travel?
- Are there unpaid medical, credit, or household bills?
- Do you want to leave a small additional amount for your beneficiary?
For example, a family planning a modest cremation may need $5,000 to $10,000, while a traditional burial with cemetery charges may require $10,000 to $15,000 or more. You do not necessarily need to cover every possible expense. The purpose is to create a realistic financial cushion.
The Federal Trade Commission’s funeral pricing checklist explains that you have the right to request itemized pricing. The FTC states: “You have the right to choose only the goods and services you want.” Asking for a funeral home’s General Price List can help you avoid paying for services your family does not need.
Super Senior Services can help you organize these decisions into a coverage target that supports affordability without leaving your family with an unnecessary shortfall.
Step 2: Understand How Premiums Stay Affordable
Final expense insurance is often more affordable than larger life insurance policies because the coverage amount is modest. Premiums are influenced by several factors:
- Your age when you apply
- Your health history
- The amount of coverage you choose
- Whether the policy asks health questions
- The payment schedule, such as monthly or annual premiums
- The carrier’s underwriting rules and available state products
Many whole life final expense policies offer level premiums, meaning the scheduled premium generally does not increase simply because you get older, as long as you keep the policy active. That predictability can make budgeting easier on a fixed retirement income.
There is an important tradeoff. A policy with health questions may offer more coverage for the premium than a guaranteed-issue policy. A guaranteed-issue plan may not ask health questions, but it can have higher premiums, lower coverage amounts, or a graded benefit during the first one or two years.
The NAIC Life Insurance Buyer’s Guide recommends comparing the policy’s benefits, premiums, and requirements before applying. In practical terms, affordable burial insurance is not simply the policy with the lowest monthly payment. It is the policy that provides useful protection, fits your budget, and has terms your family understands.
Step 3: Apply Without a Medical Exam
Many final expense policies use simplified underwriting, which means you may not need a medical exam, blood test, or paramedical appointment. Instead, the application may include a short series of health questions.
The carrier may also review information such as prescription history or other insurance databases. That is why answering every question accurately matters. An incorrect answer can create complications later during a claim review.
Some applicants may qualify for coverage with an immediate full death benefit. Others may be offered a graded or modified benefit, particularly if they select guaranteed-issue coverage. The policy documents should explain:
- Whether the policy has a waiting or graded period
- What happens if death occurs from natural causes during that period
- Whether accidental death is treated differently
- When the full benefit becomes available
- What happens if premiums are not paid
A no-exam application is convenient, but it does not mean every policy is identical. Before you sign, ask someone to explain the benefit schedule in plain English.
With personalized guidance, applying for final expense insurance can be a short, organized process rather than an overwhelming medical review.
Step 4: Keep the Policy Easy for Your Family to Use
Once approved, place your policy information somewhere secure. Tell your beneficiary:
- The insurance company’s name
- Your policy number
- Where the policy documents are stored
- Who helped you enroll
- How to contact the agent or agency
- Whether you have a preferred funeral home
You should also review your beneficiary designation after major life events, such as marriage, divorce, or the death of a listed beneficiary. Keeping this information current can reduce delays and confusion.
This simple organization is one of the most valuable parts of final expense planning. Your family should not have to search through paperwork while making difficult arrangements.
State-Specific Considerations for 2026
Final expense needs differ by location, funeral provider, cemetery, and family preferences. These practical considerations may help you start planning:
- Final expense insurance Florida: Seasonal residents, coastal travel, and cemetery availability can affect transportation and scheduling costs. Ask whether cemetery charges are separate from the funeral home estimate.
- Final expense insurance Texas: Long distances between cities and rural communities may increase transportation expenses. A policy should account for mileage or interstate transportation if family members live far apart.
- Final expense insurance New York: Metropolitan areas, particularly New York City and Long Island, may have higher funeral, cemetery, and facility costs. Families should request itemized estimates before selecting a coverage amount.
- Final expense insurance Georgia: Cemetery charges, grave opening and closing fees, and memorial markers may be billed separately. Confirm which expenses are included in a funeral package.
- Final expense insurance North Carolina: Costs can differ between larger cities, coastal communities, and rural areas. Compare burial and cremation estimates based on your preferred location.
- Final expense insurance South Carolina: Seasonal communities and travel between inland and coastal areas may affect transportation needs. Ask about local transfer fees.
- Final expense insurance Tennessee: Funeral pricing can vary between metropolitan areas and smaller communities. A written price list can make comparisons easier.
- Final expense insurance Virginia: Northern Virginia and other metropolitan regions may have higher facility and cemetery costs than rural areas. Include cemetery expenses when estimating coverage.
These are planning considerations, not fixed price quotes. The FTC Funeral Rule and local funeral providers can help you obtain current, itemized prices.
How the Claim Process Works for Your Family
When the insured person passes away, the beneficiary generally contacts the insurance company or the assisting agent and submits a claim. The insurer may request:
- A completed claim form
- A certified death certificate
- The policy number or policy documents
- Identification and beneficiary information
- Additional records if the policy is within a waiting or contestability period
The carrier reviews the claim according to the policy terms. Once approved, the death benefit is paid according to the insurer’s procedures, and the beneficiary can use the funds for funeral costs, cemetery charges, medical bills, or other permitted needs.
Keeping the policy information organized helps the process move more smoothly. It also gives your family a clear person to call for guidance.
Make Final Expense Planning Feel Simple
The right final expense policy is not about predicting every future cost. It is about creating a practical financial plan your family can understand and use.
Whether you are comparing final expense insurance for seniors in Florida, Texas, New York, Georgia, North Carolina, South Carolina, Tennessee, or Virginia, Super Senior Services can help you review coverage amounts, premiums, underwriting requirements, and beneficiary details with clarity.
Contact Stephen Jackson to discuss affordable final expense insurance options and take the next step toward greater family peace of mind.
Compliance note: Individual NPN: Stephen Jackson 20707378 | Corporate NPN: Super Senior Services 21536694.