Planning for final expenses may feel uncomfortable, but it can also be one of the most caring financial decisions you make for your family. Final expense insurance is designed to provide a modest, dependable death benefit that your beneficiary can use for funeral costs, cemetery expenses, transportation, medical bills, and other obligations.
The key is understanding what the policy does, and does not, do before you choose a coverage amount.
What Is Final Expense Insurance?
Final expense insurance, sometimes called burial insurance, is usually a small whole-life policy intended to remain in force for your lifetime as long as you pay the premiums. Coverage amounts are often in the range of $5,000 to $25,000, although some insurers may offer more or less depending on your age, health, state, and underwriting.
Unlike term life insurance, a final expense policy is not designed to replace years of income or pay off a large mortgage. Its purpose is more focused: to create a dedicated source of funds when your family may need cash quickly.
The National Association of Insurance Commissioners explains that life insurance policies are generally designed to pay money to your “named beneficiaries” when you die. Your beneficiary, not necessarily the funeral home, typically receives the death benefit and can use it according to your wishes and the policy terms.
That flexibility matters. Your family may use the funds for a traditional funeral, cremation, cemetery expenses, unpaid medical bills, or other final obligations.
What a Final Expense Policy Usually Covers
A final expense policy generally provides a cash death benefit. The proceeds can often be used for:
- Funeral home services and professional fees
- Burial or cremation expenses
- Caskets, urns, grave markers, or memorial items
- Cemetery plots, opening and closing fees, or burial vaults
- Transportation of the deceased or family members
- Final medical, hospital, hospice, or prescription bills
- Small credit card balances, utility bills, or personal debts
- Legal, probate, or estate-settlement expenses
- Travel, lodging, flowers, obituary notices, or a memorial gathering
The policy usually does not require your family to spend every dollar on one specific funeral item. That gives your beneficiary room to prioritize what matters most.
For example, if your funeral arrangements cost less than the policy benefit, the remaining funds may help with unpaid bills or travel costs. Conversely, if the arrangements cost more than the benefit, your family may need to pay the difference.
What Final Expense Insurance Does Not Cover
Final expense insurance can be helpful, but it is not an all-purpose financial plan. Understanding its limits helps you avoid buying too little, or expecting too much.
It does not usually cover living expenses while you are alive. A standard policy pays a death benefit after the insured person dies. It generally does not pay for assisted living, nursing home care, routine medical treatment, or monthly household expenses unless the policy includes a qualifying rider or living benefit.
It does not automatically lock in today’s funeral prices. A life insurance benefit is typically a fixed dollar amount. Funeral homes, cemeteries, crematories, and transportation providers may raise their prices over time. A $10,000 policy purchased today may not cover the same services several years from now.
It may not cover every cemetery or transportation charge. Cemetery fees, grave opening and closing, vaults, permits, long-distance transportation, and out-of-area services can be separate expenses. The Federal Trade Commission’s Funeral Rule guidance explains that funeral providers must provide accurate, itemized price information and allow consumers to select only the goods and services they want, subject to limited exceptions.
As the FTC states, “You may choose only the items you desire.” That right can help you compare arrangements and build a more realistic coverage target.
It may have a waiting period. Simplified-issue policies may provide the full death benefit from the first day if you qualify for a level-benefit plan. Guaranteed-issue policies, however, commonly include a graded benefit during the first two or three policy years. If death occurs from natural causes during that period, the beneficiary may receive premiums paid plus interest instead of the full face amount. The exact schedule varies by policy.
It is not intended to replace income. If your family depends on your income, has significant debt, or needs funds for education or long-term support, a larger life insurance policy may be more appropriate. Final expense coverage should solve a defined problem, not carry responsibilities it was never designed to handle.
Simplified Issue, No Medical Exam, and Guaranteed Issue
Many seniors appreciate that final expense insurance can be more accessible than traditional life insurance.
Simplified-issue coverage usually requires health questions but no medical exam. The insurer may review your answers, prescription history, or other information. If you qualify, you may receive a level death benefit with level premiums.
This option can be a good value for someone with manageable health conditions who wants to avoid blood tests or an in-person examination. Controlled diabetes, high blood pressure, or other chronic conditions may be acceptable with some carriers, although approval is never automatic.
Guaranteed-issue coverage generally requires no health questions and no medical exam. It may be available to applicants who cannot qualify for simplified issue because of serious health conditions. The tradeoff is often a higher premium for the same amount of coverage and a graded benefit during the early policy years.
Before applying, ask:
- Is this simplified issue or guaranteed issue?
- Is the death benefit level from day one?
- What does the beneficiary receive during the first two or three years?
- Are premiums guaranteed to remain level?
- What happens if a premium is missed?
- Can a policy loan reduce the death benefit?
- What exclusions and contestability provisions apply?
A licensed professional can help you compare the underwriting path that provides the best balance of accessibility, affordability, and protection.
How to Choose an Affordable Coverage Amount
Start with actual planning, not a random round number. Request an itemized price list from a funeral provider and consider the following formula:
Funeral or cremation services + cemetery expenses + transportation + final bills + family travel − existing savings or other coverage = estimated need
The NFDA’s latest published national figures, based on 2023 General Price List data, reported median costs of $8,300 for a funeral with viewing and burial and $6,280 for a funeral with viewing and cremation. The burial figure did not include a burial vault, and these medians did not include every cemetery, monument, or cash-advance expense.
That means a policy of $10,000, $15,000, or another amount could be appropriate for some families, but the right number depends on your arrangements, location, savings, and preferences. These are planning examples, not quotes or guaranteed costs.
Most importantly, choose a premium that fits comfortably within your monthly budget. A lower benefit that stays active may provide more protection than a larger policy that becomes difficult to maintain. Level premiums can make budgeting easier, particularly when you live on Social Security, a pension, or other fixed income.
State Planning Considerations in 2026
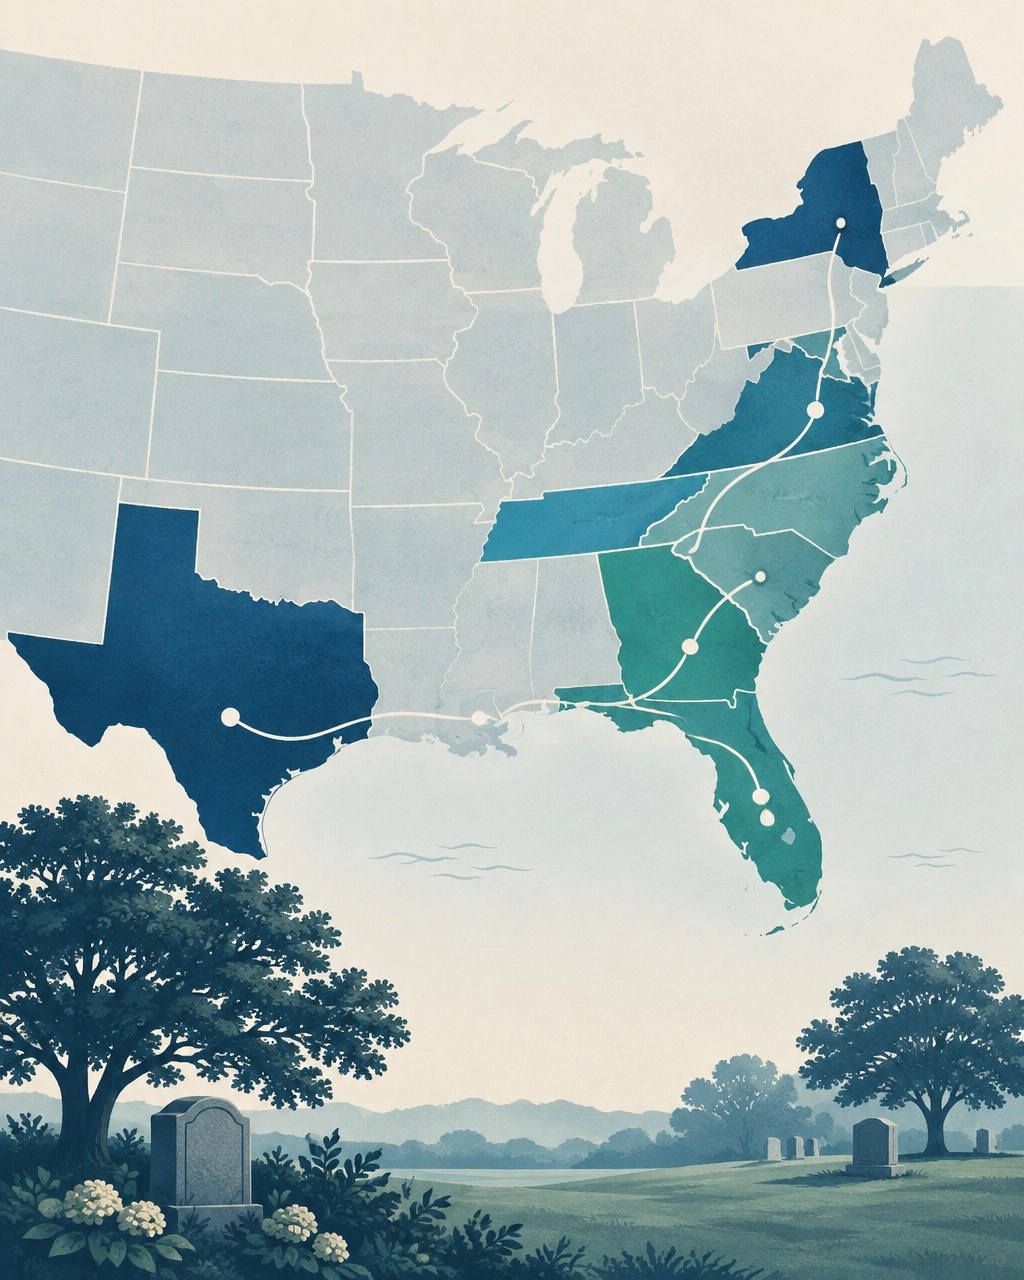
Funeral and cemetery expenses vary by location. The following considerations are not price quotes; they are reminders to investigate the costs your family is most likely to face.
- Florida: Coastal and metropolitan areas may have different funeral-home and cemetery pricing than smaller inland communities. If family members live in another part of the state, include transportation and travel in your planning.
- Georgia: Costs can vary between the Atlanta metropolitan area and rural communities. Ask whether cemetery opening and closing, grave liners, or transportation are included separately.
- Texas: Because distances can be substantial, transportation between cities or rural areas may be an important expense. Compare urban funeral-home pricing with the costs available near your preferred cemetery.
- Tennessee: Mountainous and rural geography may affect transportation, service availability, and travel time. A family choosing a cemetery away from the funeral home should plan for that additional coordination.
- North Carolina: Growing urban areas may have different pricing from smaller towns. Consider cemetery availability, crematory access, and whether relatives will travel from another region.
- South Carolina: Coastal communities, larger cities, and rural areas can differ in funeral and cemetery costs. Seasonal travel and family relocation may also affect how transportation is handled.
- Virginia: Northern Virginia and other major urban areas may have higher facility and cemetery expenses than rural communities. Families should also consider interstate travel if relatives live nearby in another state.
- New York: New York City, Long Island, and upstate communities can have significantly different funeral, cemetery, and transportation considerations. If you are planning in New York State, ask for itemized local pricing and consider whether remains or family members will need to travel.
A local, personalized review helps ensure your coverage amount reflects your actual wishes, not a generic national average.
A Simple Final Expense Review Checklist
Before choosing a policy, confirm these five details:
- Purpose: Is the policy focused on funeral and final bills, or do you need broader life insurance?
- Amount: Have you included cemetery, transportation, medical, and family travel expenses?
- Accessibility: Do you qualify for simplified issue, or would guaranteed issue provide a more realistic path?
- Premiums: Are the payments level and manageable for your long-term budget?
- Benefit timing: Is the full death benefit available immediately, or does a graded period apply?
You should also review your beneficiary designation regularly. A policy can only provide peace of mind if the beneficiary information is current and your family knows where the policy documents are located.
If you are also reviewing Medicare coverage in Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, or New York State, you can explore our Medicare plan resource for help comparing available options.
Get Personalized Help Choosing Affordable Coverage
Final expense insurance is about more than paying a funeral bill. It is about protecting your family’s financial stability during an emotional time, preserving your choices, and reducing the risk that loved ones must make urgent decisions without enough money available.
Super Senior Services can help you compare accessible options, including simplified-issue and guaranteed-issue paths, review level-premium structures, and choose an amount that fits your goals and budget. We simplify the details so you can move forward with greater confidence and peace of mind.
Contact Stephen Jackson to discuss your final expense options.
Compliance note: Individual NPN, Stephen Jackson: 20707378. Corporate NPN, Super Senior Services: 21536694.