Planning ahead can be one of the most caring financial decisions you make for your family. Final expense insurance for seniors can help pay for funeral services, burial or cremation, cemetery expenses, medical bills, and other costs that may arise after your death.
But how much coverage is enough?
The right amount depends on where you live, whether you prefer burial or cremation, the type of service you want, and whether you want to leave a small financial cushion for your family. In 2026, many seniors may consider $10,000–$25,000 of final expense coverage, while families planning a traditional burial in higher-cost areas may need $25,000–$30,000 or more.
The goal is not to buy the largest policy. It is to choose affordable coverage that matches your wishes and protects your family from an unexpected bill.
WordPress category: finalexpense
Compliance note: Individual NPN : Stephen Jackson: 20707378. Corporate NPN : Super Senior Services: 21536694.
Why funeral costs can be higher than expected
A funeral bill usually includes more than the funeral home’s basic service charge. Your family may also need to pay for:
- Transportation and preparation of the deceased
- Embalming or other preparation
- A viewing, ceremony, or graveside service
- A casket or cremation container
- A burial vault or grave liner
- Cemetery space or a mausoleum niche
- Opening and closing the grave
- A marker, monument, or headstone
- Flowers, clergy, musicians, obituaries, and transportation for family members
The National Funeral Directors Association’s latest published national benchmark reports a median cost of $8,300 for a funeral with viewing and burial, excluding a vault. Adding the median vault cost of $1,695 brings the funeral-home total to approximately $9,995: before cemetery plot, marker, and other cash-advance expenses.
As the NFDA explains, “The cost does not take into account cemetery, monument or marker costs or miscellaneous cash-advance charges.” You can review the NFDA funeral cost statistics for additional detail.
That is why a policy that appears large enough at first glance may not cover the complete cost. A personalized review helps you plan with greater accuracy and peace of mind.
A simple formula for choosing final expense coverage
Start with the expenses your family is most likely to face:
Funeral or cremation costs + cemetery expenses + unpaid bills + family cushion − existing savings or insurance = estimated coverage need
For example:
- Funeral and burial: $14,000
- Cemetery and marker: $4,000
- Medical bills and small debts: $2,000
- Family cushion: $2,000
- Existing savings: -$2,000
Estimated need: $20,000
You do not need to predict every future expense perfectly. Instead, request an itemized price list from local funeral providers and compare the options that matter most to you.
The Federal Trade Commission’s funeral pricing checklist can help. The FTC states, “The funeral provider must give you an itemized statement of the total cost of the funeral goods and services you have selected.”
That itemized information can help you avoid overinsuring, underinsuring, or paying for services you do not want.
2026 state-by-state final expense planning ranges
The figures below are practical planning ranges: not guaranteed prices or official state averages. Funeral costs can vary significantly between metropolitan and rural areas, funeral homes, cemeteries, faith traditions, and service choices.
| State | Traditional burial planning range | Cremation or simpler service range |
|---|---|---|
| Florida | $15,000–$20,000 | $6,000–$12,000 |
| Georgia | $14,000–$20,000 | $6,000–$12,000 |
| Texas | $13,000–$20,000 | $5,000–$12,000 |
| Tennessee | $13,000–$18,000 | $5,000–$10,000 |
| North Carolina | $13,000–$18,000 | $5,000–$10,000 |
| South Carolina | $13,000–$19,000 | $5,000–$11,000 |
| Virginia | $16,000–$25,000 | $6,000–$13,000 |
| New York | $20,000–$30,000 | $8,000–$15,000 |
Florida final expense insurance for seniors
In Florida, burial costs may increase when cemetery property, vaults, grave opening and closing, or memorial services are added to the funeral-home bill. A $15,000–$20,000 policy may be a reasonable starting point for a traditional burial, while $8,000–$12,000 may fit a cremation with a memorial service.
Georgia final expense insurance for seniors
Georgia families may choose anything from a simple cremation to a full traditional burial. If you want a viewing, ceremony, cemetery space, and marker, consider reviewing coverage in the $14,000–$20,000 range. Affordable burial insurance can be adjusted to your budget after your preferred services are identified.
Texas final expense insurance for seniors
Texas is a large state with wide cost differences between communities. Cemetery prices, transportation, and the distance between the funeral home and burial location may affect the final bill. Many families planning a traditional burial may begin by comparing $15,000, $20,000, and $25,000 policy options.
Tennessee final expense insurance for seniors
Tennessee seniors may find that a traditional service falls in the low-to-mid five figures once cemetery costs are included. A policy between $13,000 and $18,000 may provide a useful starting point, while a simpler cremation plan may require less.
North Carolina final expense insurance for seniors
North Carolina offers many service choices, from direct cremation to a full church, funeral-home, and cemetery arrangement. For a traditional burial, consider a target of $13,000–$18,000, then add a buffer if you want to cover unpaid bills or travel costs for family members.
South Carolina final expense insurance for seniors
In South Carolina, the funeral-home charge may not include cemetery property, a vault, or a headstone. A $13,000–$19,000 benefit can help account for those additional items. Requesting a written price list can make affordable burial insurance easier to match to your plans.
Virginia final expense insurance for seniors
Virginia families may face higher costs in certain communities, particularly when cemetery property and a formal service are included. A traditional burial may justify reviewing $16,000–$25,000 of coverage. A personalized comparison can help you avoid paying for more insurance than your family needs.
New York final expense insurance for seniors
New York is often one of the more expensive states for funeral and cemetery arrangements. Costs can rise quickly in and around major metropolitan areas, and cemetery expenses may be substantial. Many families planning a traditional burial may want to consider $20,000–$30,000 of coverage, while cremation planning may fit within $8,000–$15,000.
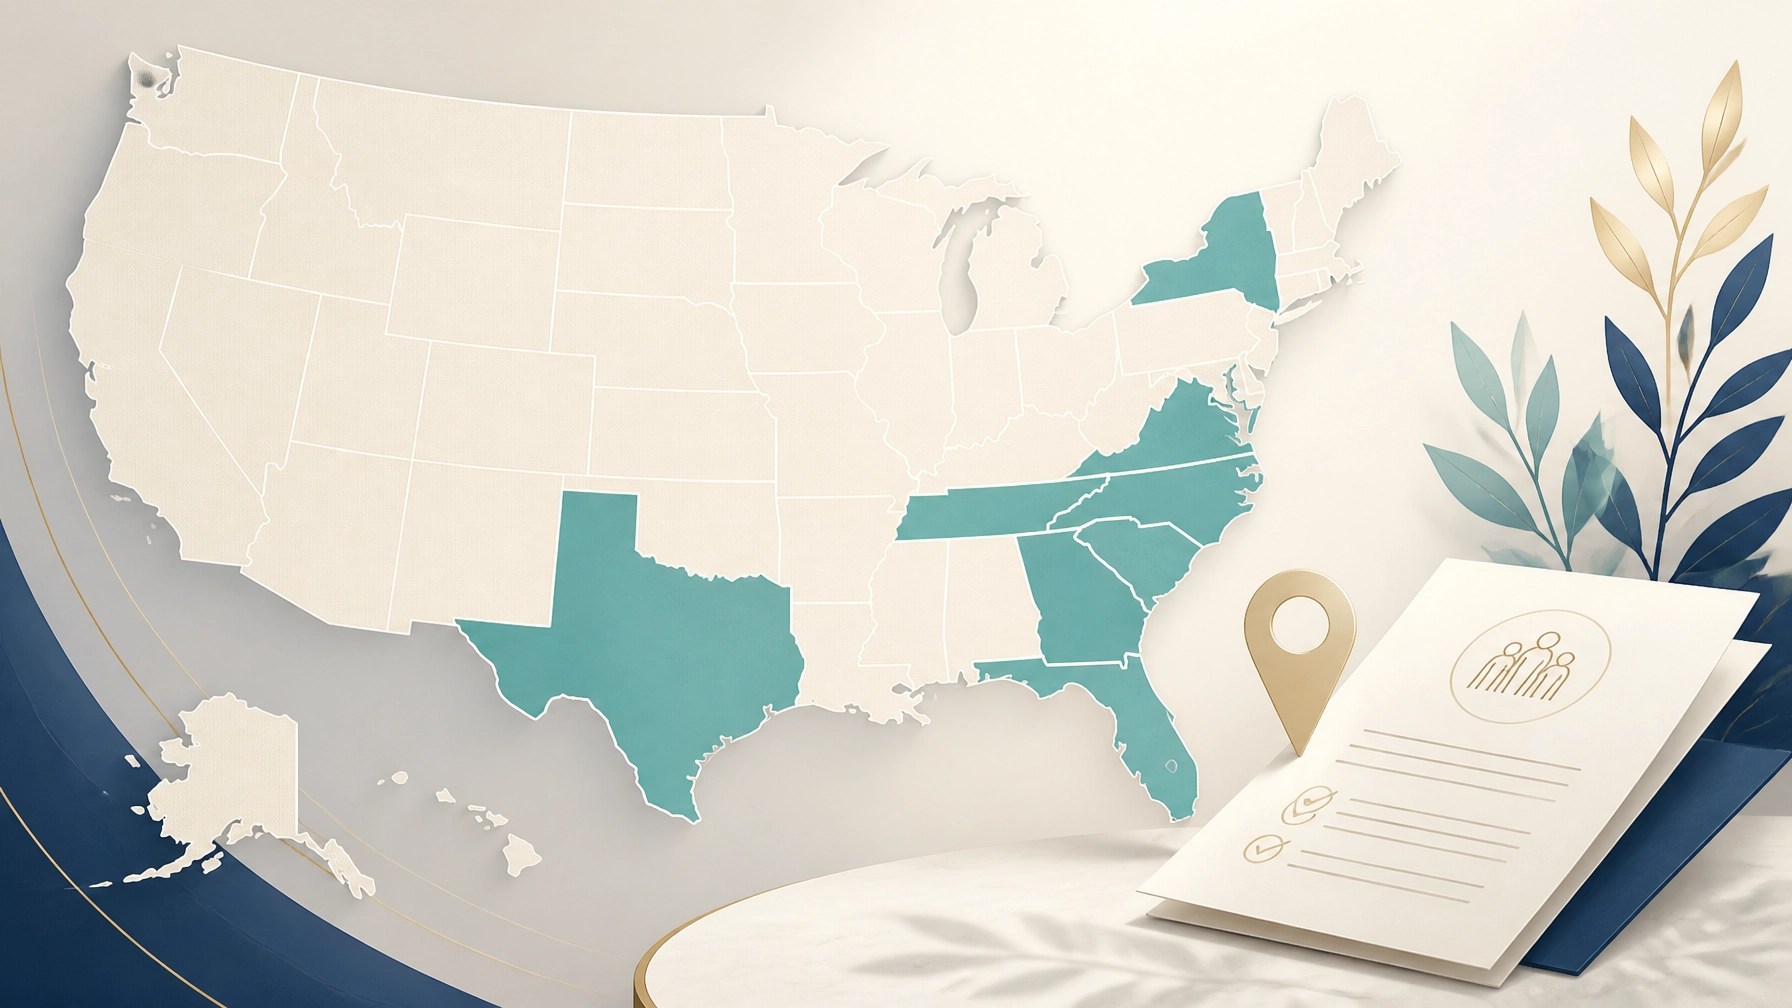
Local prices matter. Super Senior Services can help you review your goals and compare coverage options available in Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, and New York.
No-medical-exam and simplified issue options
Many seniors search for no medical exam life insurance because they want a straightforward application process. With a simplified issue policy, you typically answer health questions, but you do not complete a physical exam.
The insurer may still review information such as:
- Prescription history
- Medical records
- Previous insurance applications
- Diagnosed conditions
- Recent hospitalizations or treatments
Approval may be faster than traditional fully underwritten life insurance. However, no-medical-exam coverage is not automatically guaranteed, and serious health conditions may affect eligibility, premiums, or the benefit structure.
Some applicants may qualify for simplified issue life insurance with immediate full benefits. Others may be offered guaranteed issue coverage or a graded benefit, which may limit the payout for natural death during the first two or three policy years. Always ask:
- Are premiums level for life?
- Is the death benefit fully guaranteed from the first day?
- Is there a waiting period?
- What happens if the policy lapses?
- Are there exclusions or reduced benefits?
- How much will my beneficiary receive after any policy loan?
The NAIC life insurance consumer guide recommends understanding how premiums, benefits, guarantees, and policy values work before you buy. You can also find your state insurance department through the NAIC state insurance department directory.
How to keep final expense insurance affordable
Affordable burial insurance begins with realistic planning. You can often control costs by:
- Comparing several funeral homes using itemized price lists.
- Deciding whether you prefer burial, direct cremation, or cremation with a service.
- Confirming whether you already own cemetery property.
- Adding only the coverage your family actually needs.
- Choosing a premium that fits comfortably within your monthly budget.
- Reviewing existing life insurance before purchasing a new policy.
- Naming a trusted beneficiary and explaining your wishes.
A smaller policy that remains active is more helpful than a larger policy that becomes unaffordable. Your coverage should support long-term financial stability: not create new stress.
Get personalized help choosing coverage
The right amount of final expense coverage in 2026 depends on your state, your funeral preferences, your health, and your budget. A family planning a simple cremation may need $5,000–$10,000. A family planning a traditional burial with cemetery property may need $15,000–$30,000 or more.
You do not have to sort through policy types, health questions, waiting periods, and benefit amounts alone. Super Senior Services simplifies the process, compares available options, and helps you choose coverage designed around your needs.
Contact Super Senior Services to discuss final expense insurance for seniors. A thoughtful plan today can bring your family greater affordability, financial security, and peace of mind tomorrow.
{“@type”:”FAQPage”,”@context”:”https://schema.org”,”mainEntity”:[{“name”:”How much final expense insurance do seniors need in 2026?”,”@type”:”Question”,”acceptedAnswer”:{“text”:”Many seniors may consider $10,000 to $25,000 of final expense insurance. Traditional burial plans in higher-cost areas, including parts of New York and Virginia, may require $25,000 to $30,000 or more.”,”@type”:”Answer”}},{“name”:”What is burial insurance for seniors?”,”@type”:”Question”,”acceptedAnswer”:{“text”:”Burial insurance for seniors is generally a smaller permanent life insurance policy intended to help pay funeral, burial, cremation, cemetery, medical, and other final expenses.”,”@type”:”Answer”}},{“name”:”Can seniors get no-medical-exam life insurance?”,”@type”:”Question”,”acceptedAnswer”:{“text”:”Many seniors may qualify for no-medical-exam life insurance. Simplified issue policies commonly require health questions and may include prescription or medical-record reviews, while eligibility and benefit terms vary by insurer.”,”@type”:”Answer”}},{“name”:”Is simplified issue life insurance always available to seniors?”,”@type”:”Question”,”acceptedAnswer”:{“text”:”Availability depends on age, health history, state, insurer guidelines, and the requested benefit amount. Some applicants may qualify for simplified issue coverage, while others may be offered guaranteed issue or graded-benefit coverage.”,”@type”:”Answer”}}]}