Category: businesshealth
Open enrollment is more than a paperwork exercise. It is your opportunity to help employees understand an important part of their compensation, and to show that you respect their time, questions, and financial priorities.
Health insurance language can feel confusing even when the plan itself is valuable. Terms such as deductible, coinsurance, provider network, and formulary may sound familiar, but employees often need practical examples before they can make confident decisions.
As a New York small-business owner, you do not need to become an insurance expert to lead a productive conversation. You need a clear communication plan, consistent information, and a willingness to explain how the coverage affects your employees’ everyday lives and budgets.
Super Senior Services helps New York businesses simplify plan comparisons, prepare for employee questions, and make benefit discussions more approachable.
Compliance note: Individual NPN: Stephen Jackson, 20707378. Corporate NPN: Super Senior Services, 21536694.
Start with the “why” behind the benefit
Before reviewing plan details, explain why your business offers health insurance and what employees should gain from it.
You might say:
“Our goal is to offer coverage that supports your health while helping you plan for medical expenses with greater confidence.”
This opening matters. Employees are more likely to pay attention when they understand that the benefit is connected to preventive care, access to doctors, prescription coverage, and financial stability, not simply another payroll deduction.
Explain the basics clearly:
- Who is eligible for coverage
- Whether dependents may be included
- What the company contributes
- What employees contribute
- When coverage becomes effective
- Where employees complete their elections
- Who can answer questions privately
If your business offers more than one plan, explain the decision in terms employees can use: lower paycheck costs, more predictable office-visit expenses, broader provider access, or greater protection from a large medical bill.
The goal is not to steer everyone toward one option. It is to help each employee identify the coverage that best fits their household.
Explain the cost terms with real examples
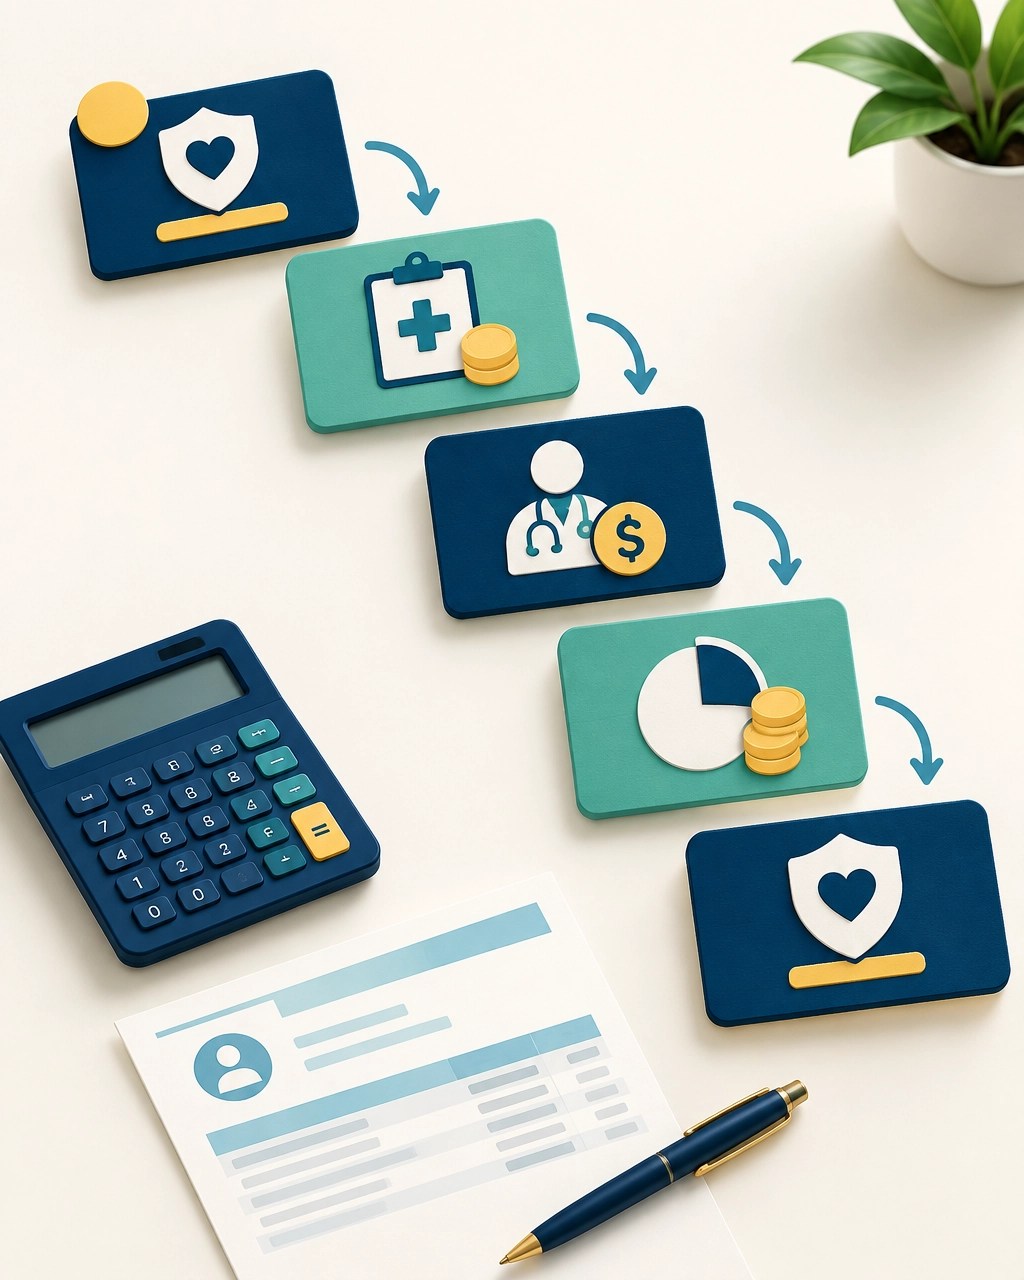
A side-by-side chart is useful, but employees also need a plain-language explanation of how the numbers work together.
Premium
The premium is the amount paid to keep the health plan active. Your business may pay all or part of the employee’s premium, while the employee pays the remaining share through payroll deductions.
For example, if the employee share is $120 per paycheck and payroll runs twice monthly, the employee’s contribution is approximately $240 per month.
Tell employees exactly what they will pay, not just the total plan premium. Show the employer contribution and employee contribution separately.
Suggested talking point:
“The total monthly premium is $___ per employee. The company pays $, and your payroll deduction is approximately $ per pay period.”
Deductible
The deductible is the amount an employee generally pays for certain covered services before the plan begins paying a larger share. Some services, such as preventive care, may be covered before the deductible under the plan’s rules.
For example, with a $1,500 deductible, an employee may pay covered expenses that apply to the deductible until reaching $1,500. The deductible may not apply to every service, so employees should review the plan summary.
Connect the number to the employee’s budget:
“The deductible is the amount you may need to plan for before certain services receive fuller plan coverage. A lower deductible may come with a higher premium, while a higher deductible may reduce the paycheck cost.”
Copay
A copay is a fixed dollar amount paid for a covered service, such as $25 for a primary-care visit or $50 for an urgent-care visit.
Employees appreciate seeing common costs together:
- Primary-care visit: $___
- Specialist visit: $___
- Urgent care: $___
- Emergency room: $___
- Generic prescription: $___
Remind employees that a copay does not always replace the deductible or other cost-sharing. The plan documents determine which rules apply.
Coinsurance
Coinsurance is the percentage of an allowed charge an employee pays after meeting any applicable deductible. If the plan has 20% coinsurance, the plan may pay 80% of the covered allowed amount while the employee pays 20%.
For an illustrative $2,000 allowed charge, 20% coinsurance would equal $400 before considering other plan rules.
A helpful explanation is:
“A copay is usually a set dollar amount. Coinsurance is usually a percentage. The difference matters most when the underlying service is expensive.”
Out-of-pocket maximum
The out-of-pocket maximum is the plan’s annual limit on what an employee pays for covered, in-network services through deductibles, copays, and coinsurance. Once the limit is reached, the plan generally pays 100% of covered in-network services for the rest of the plan year, subject to the policy’s terms.
This is an important financial safety feature. Make the number easy to find and explain what it does, and does not, include.
Make provider networks practical
A provider network is the group of doctors, hospitals, laboratories, and other healthcare professionals contracted with a plan.
Employees should understand that choosing an in-network provider usually results in lower costs. Some HMO and EPO plans may not cover non-emergency out-of-network care, while PPO plans may provide out-of-network coverage at a higher cost.
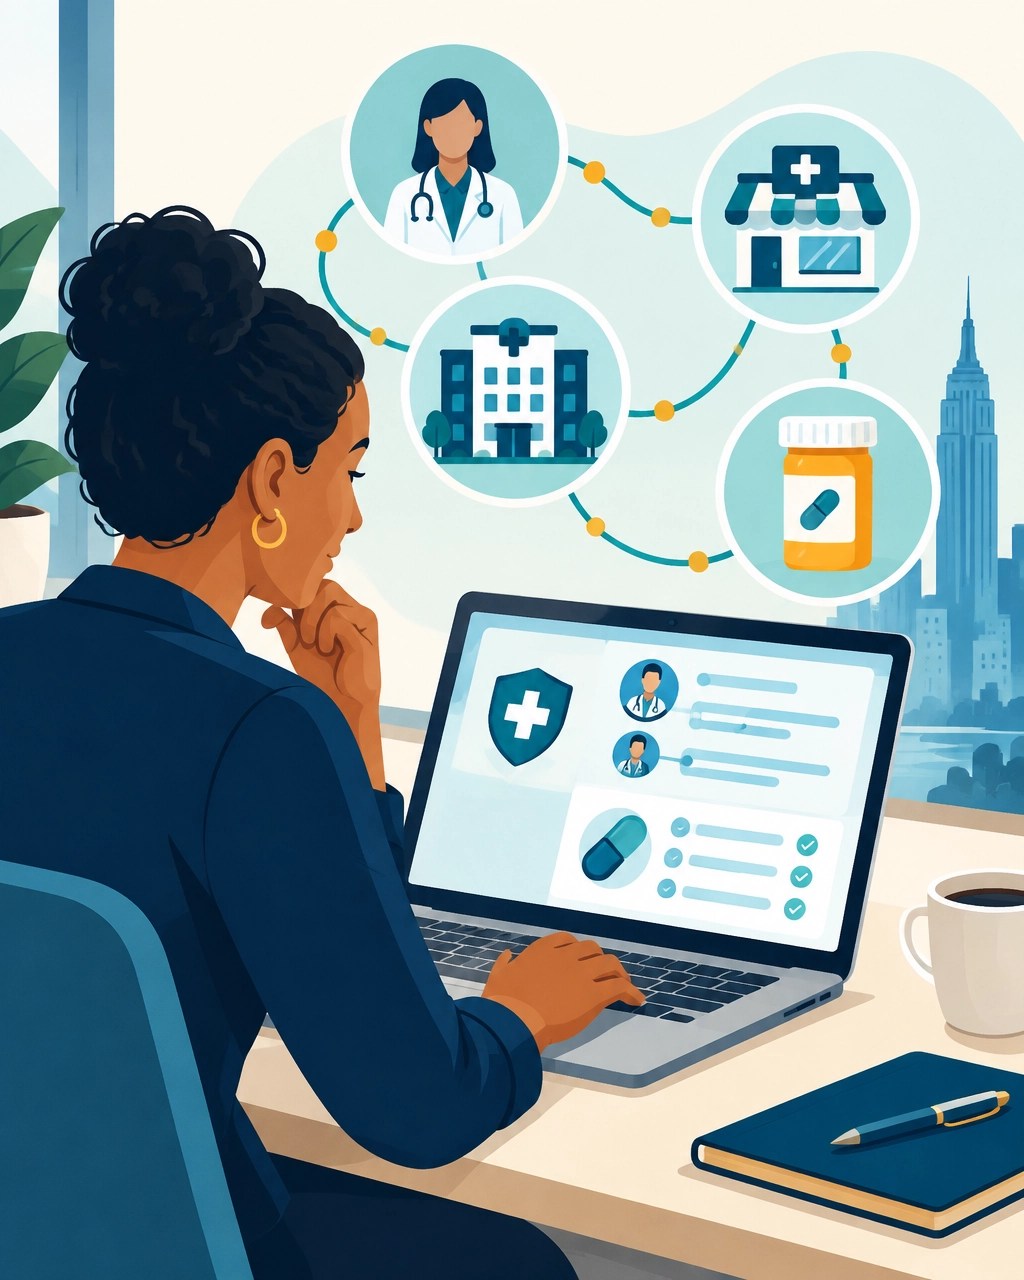
Encourage employees to verify:
- Their primary-care provider
- Important specialists
- Preferred hospitals
- Nearby urgent-care locations
- Pediatric or behavioral-health providers, when relevant
- Whether their preferred laboratory is in-network
Do not rely only on an employee’s assumption that a doctor “takes the insurance.” Provider participation can vary by plan network, so employees should use the carrier’s online directory or customer service number.
You can say:
“Before selecting a plan, please check your most important doctors and facilities in the specific network: not only the insurance company’s name.”
For plain-language definitions of network types and other insurance terms, direct employees to the Healthcare.gov glossary.
Discuss formularies and prescription costs
A formulary is the plan’s list of covered prescription medications. Drugs are often grouped into tiers, such as:
- Generic medications
- Preferred brand-name medications
- Non-preferred brand-name medications
- Specialty medications
Each tier may have a different copay or coinsurance amount. Some prescriptions may also require prior authorization, step therapy, or use of a preferred pharmacy.
Employees who take ongoing medications should review the formulary before making an election. Encourage them to check the exact medication name, dosage, and tier rather than assuming that a similar drug will have the same cost.
A useful talking point is:
“If you take regular medications, compare the formulary and pharmacy rules as carefully as the premium. A plan with a lower paycheck deduction may not be the most affordable choice if your prescriptions cost more.”
Provide the formulary link, carrier phone number, and instructions for finding pharmacy information. This small step can prevent unpleasant surprises.
Handle questions about cost and coverage changes honestly
Employees may ask why their payroll deduction changed, why a copay is different, or whether their current doctor will remain available.
Avoid vague answers. Prepare a one-page summary that shows:
- What changed
- What stayed the same
- The employee’s new contribution
- Changes to deductibles, copays, or coinsurance
- Network updates
- Formulary or pharmacy changes
- Any changes to dependent coverage
- Where to find complete plan documents
If you do not know an answer, say so and commit to finding it. A trustworthy response is:
“I want to give you an accurate answer rather than guess. I’ll confirm that with our benefits professional and follow up.”
Super Senior Services can help you compare plan features and translate carrier information into a communication employees can actually use. Our New York group health insurance information can also help you prepare for the broader benefits conversation.
Explain waivers without pressure
Some employees may decline coverage because they have coverage through a spouse, another employer, or another qualifying source. Others may decide that the employee contribution does not fit their budget.
Explain that waiving coverage is an election that should be made carefully. Employees should understand:
- Whether they must provide information about other coverage
- Whether they need to complete a waiver form
- Whether they can change their election later
- What events may allow a midyear change
- When they will receive confirmation of their election
Protect privacy during this conversation. Employees should not be asked to disclose personal medical details in a group meeting. Direct individual questions to HR, the carrier, or your licensed benefits professional.
A respectful phrase is:
“You are welcome to ask questions privately. Our goal is to help you make an informed decision, not to pressure you into a particular election.”
Use a simple employee meeting structure
A 30-minute meeting can be enough when it is organized:
- Opening: Explain the purpose of the benefit and the employee’s role in reviewing options.
- Plan overview: Compare the available choices using premiums, deductibles, copays, coinsurance, and out-of-pocket maximums.
- Access: Explain networks, provider searches, formularies, and prescription rules.
- Employee cost: Show paycheck deductions and dependent costs.
- Action steps: Demonstrate how to enroll, change coverage, or submit a waiver.
- Questions: Answer general questions publicly and move personal situations to a private conversation.
After the meeting, send a written recap. Include the plan comparison, Summary of Benefits and Coverage, carrier links, contact information, and a short list of frequently asked questions.
Clear communication improves participation because employees know what they are choosing and why. It also increases appreciation for the benefit because they can see the employer’s contribution and the protection the plan provides.
Give your employees clarity: and give yourself support
Health insurance communication does not have to be intimidating. When you replace jargon with examples, show the real employee cost, and make networks and formularies easy to check, you create a more confident enrollment experience.
You also demonstrate something important about your business: your employees’ health and financial well-being matter.
Super Senior Services helps New York small-business owners simplify plan comparisons, prepare understandable employee materials, and guide the benefits process with transparency and care. Contact us to discuss how we can support your next employee benefits conversation.