Medicare decisions can feel complicated, especially when plan benefits, prescription costs, enrollment windows, and state rules all come into play. The good news is that you do not have to figure everything out alone.
This guide explains the most important 2026 Medicare updates, how Medigap plans help fill Original Medicare gaps, and when you can enroll or change coverage. Super Senior Services provides personalized Medicare guidance for residents of Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, and New York, including New York State.
“Medigap policies are health insurance policies sold by private insurance companies to fill gaps in Original Medicare.” : Medicare.gov
Publication compliance note: Individual NPN : Stephen Jackson: 20707378. Corporate NPN : Super Senior Services: 21536694.
If you want help comparing your options, visit Super Senior Services’ Medicare plan page or contact Stephen’s team.
Medicare Advantage 2026 Updates: New Protections and Prescription Savings
Medicare Advantage, also called Medicare Part C, combines Part A and Part B coverage through a Medicare-approved private plan. Most Medicare Advantage plans also include Part D prescription drug coverage, and many offer additional benefits such as dental, vision, hearing, or transportation services.
For 2026, the Centers for Medicare & Medicaid Services introduced several important guardrails.
Approved inpatient hospital stays receive stronger protection
If a Medicare Advantage plan approves an inpatient hospital admission, the plan generally cannot later reverse that approval because of new medical information that was not available when the decision was made. Exceptions include fraud or an obvious administrative or clinical error.
This matters because an unexpected downgrade from inpatient status to observation can affect your hospital bill and your eligibility for post-hospital services. CMS also clarified that coverage decisions made before, during, or after care are organization determinations, giving you notice and appeal rights.
If a plan makes an adverse decision or fails to provide timely notice, you may have the right to appeal. Consequently, keep approval letters, notices, and hospital records in one place.
Supplemental benefits must remain health-related
CMS also tightened rules for Special Supplemental Benefits for the Chronically Ill and other supplemental benefits. Items such as alcohol and tobacco are not allowable benefits. Plans must keep these offerings connected to health, prevention, daily functioning, or evidence-supported care.
The practical benefit is greater clarity. Instead of assuming that every advertised extra is available or medically appropriate, you can review whether a benefit directly supports your health needs and whether you meet the plan’s eligibility requirements.
Plan choices remain available, but your county matters
Medicare Advantage availability continues in 2026, but premiums, provider networks, formularies, and benefits can vary by county. A plan that looks attractive in one ZIP code may not be available — or may have different costs — in another.
That is why annual plan reviews matter. Check whether your doctors remain in-network, whether your prescriptions are on the formulary, and whether your preferred pharmacy still offers the lowest copays.
Part D has a $2,100 annual out-of-pocket cap
For 2026, Medicare Part D includes a $2,100 annual out-of-pocket cap for covered prescription drugs. Once you reach that amount, you generally pay no additional cost-sharing for covered Part D prescriptions for the rest of the calendar year, although your plan premium still applies.
Additionally, the first 10 Medicare-negotiated drug prices take effect on January 1, 2026. Your personal savings will depend on whether one of those drugs is prescribed to you and how your plan applies the negotiated price.
The Medicare Prescription Payment Plan also receives an important update. If you elected the program, which spreads prescription costs across monthly payments, your election may automatically renew for the following year. Your plan must send a renewal notice, and you can review the terms or opt out through the required process.
For some people, this creates valuable budget predictability. For others, paying at the pharmacy may be simpler. Super Senior Services can help you compare your formulary, pharmacy costs, and payment options at superseniorservices.com/medplans.
Medigap Plans: How Medicare Supplement Coverage Helps
Original Medicare gives you broad access to providers, but it does not cover every cost. In 2026, most beneficiaries pay a standard Part B premium of $202.90 per month, a Part B deductible of $283, and a Part A inpatient hospital deductible of $1,736 per benefit period.
After meeting the Part B deductible, you generally pay 20% coinsurance for covered Part B services. Original Medicare also does not have a yearly out-of-pocket maximum for Part A and Part B services.
A Medigap policy helps pay some of these gaps. Depending on the plan letter, it may cover Part A and Part B coinsurance, hospital deductibles, skilled nursing coinsurance, and other approved costs. Medigap plans generally do not include prescription drug coverage, so you may need a separate Part D plan.
Your six-month Medigap Open Enrollment Period
Your federal Medigap Open Enrollment Period begins when you are at least 65 and enrolled in Medicare Part B. It lasts six months.
During this one-time window, insurance companies generally must sell you any Medigap plan they offer in your area, regardless of your health history. They cannot use medical underwriting to deny you or charge more because of a pre-existing condition.
This period is valuable because buying later may involve health questions, higher premiums, or a denial, depending on federal and state rules. Compare plans early, even if you feel healthy today.
Medicare Advantage trial rights
If you enroll in Medicare Advantage when you are first eligible for Medicare, you generally have a 12-month trial right to return to Original Medicare and buy a Medigap plan with guaranteed-issue protections.
You may also have a 12-month trial right if you previously had Medigap, switched to Medicare Advantage for the first time, and decide to return. Timing is critical. In many situations, you must apply within 63 days after your Medicare Advantage coverage ends.
New York’s continuous Medigap enrollment
New York State has especially strong Medigap protections. New York generally allows continuous, year-round Medigap open enrollment, meaning eligible residents can apply to change Medigap plans or carriers without waiting for a birthday window.
New York does not use a traditional Medigap birthday rule. Other states may have birthday or anniversary rules that allow certain policyholders to switch plans during a limited period, usually to equal or lesser benefits. The exact rules depend on the state, plan, and reason for the change.
Because switching rules can affect your premiums and eligibility, review your situation before canceling an existing policy. Super Senior Services can help you compare Medigap choices across Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, and New York. Start at our Medicare plan page.
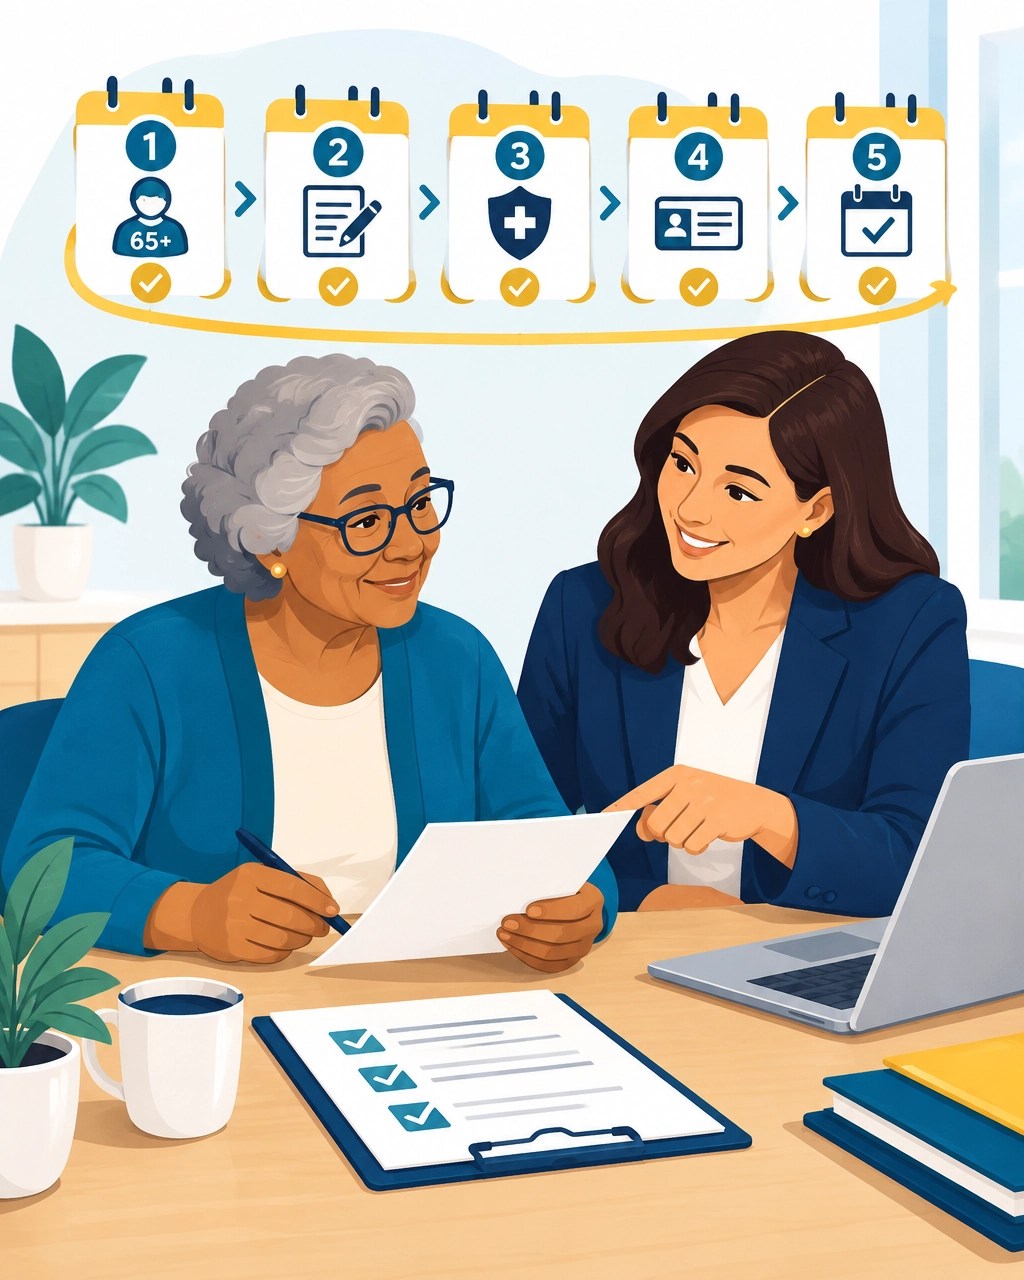
Your Step-by-Step Medicare Enrollment Guide
Step 1: Identify your Initial Enrollment Period
Your Initial Enrollment Period is a seven-month window. It begins three months before the month you turn 65, includes your birthday month, and ends three months afterward.
During this period, you can enroll in Medicare Part A and Part B and review Medicare Advantage or Part D options. If you are already receiving Social Security benefits, enrollment may happen automatically. If not, review the process through Social Security’s Medicare information.
Enroll early when possible. If you sign up before your birthday month, coverage may begin sooner, helping you avoid gaps.
Step 2: Check whether employer coverage changes your timing
If you or your spouse continue working and you have active employer group coverage, you may be able to delay Part B without a late enrollment penalty. When employment or employer coverage ends, you may qualify for an eight-month Special Enrollment Period for Part B.
Ask whether your employer coverage is creditable coverage, meaning it is expected to pay at least as much as Medicare’s standard prescription coverage. If you delay Part D without creditable drug coverage, a late enrollment penalty may apply later.
Step 3: Use the General Enrollment Period if needed
If you missed your Initial Enrollment Period and do not qualify for a Special Enrollment Period, the General Enrollment Period runs from January 1 through March 31 each year.
Coverage generally begins the month after you enroll, and late enrollment penalties may apply. You can learn more through Medicare’s official enrollment guidance.
Step 4: Review plans during Annual Enrollment
The Medicare Annual Enrollment Period runs from October 15 through December 7. During this period, you can join, switch, or drop a Medicare Advantage plan or Part D plan.
Your new coverage generally begins January 1. Review your Annual Notice of Change, drug formulary, provider directory, premiums, deductibles, and maximum out-of-pocket amount before making a decision.
Step 5: Know the Medicare Advantage Open Enrollment Period
If you are already enrolled in Medicare Advantage, the Medicare Advantage Open Enrollment Period runs from January 1 through March 31.
During this period, you can switch to another Medicare Advantage plan or return to Original Medicare and generally add a standalone Part D plan. You usually can make only one change during this window.
Step 6: Watch for Special Enrollment Periods
Special Enrollment Periods may apply after certain life events, including moving outside your plan’s service area, losing employer or union coverage, gaining or losing Medicaid eligibility, or being affected by a declared emergency.
The timing and available choices vary. Document the qualifying event and act promptly so you do not miss the enrollment deadline.
For one-on-one assistance reviewing your dates, coverage, prescriptions, doctors, and budget, visit superseniorservices.com/medplans or contact Super Senior Services.
Make Your 2026 Medicare Decision With Confidence
Medicare Advantage may offer coordinated care, an annual medical out-of-pocket limit, and additional benefits. Medigap may provide more predictable cost-sharing alongside Original Medicare. Neither option is automatically right for everyone.
Your doctors, prescriptions, travel habits, preferred hospitals, health needs, and budget should guide the decision. The 2026 changes create meaningful protections and savings opportunities, but the best results come from comparing the details — not simply choosing the plan with the lowest premium.
Super Senior Services simplifies that comparison with personalized benefit reviews, trusted plan options, and ongoing support across Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, and New York. For clarity, affordability, and peace of mind, start your Medicare plan review today or reach out directly to Stephen’s team.