If you were enrolled in New York’s Essential Plan and your household income fell between 200% and 250% of the federal poverty level, July 1, 2026 may have changed your health coverage overnight.
Approximately 450,000 New Yorkers were affected by the Essential Plan cliff. The special enrollment window created for this transition has now passed its August 30, 2026 practical deadline.
That can feel stressful, especially if you were used to $0 premiums, no deductible, and very low copays. But you still have steps you can take today: and a clear path toward the next NY State of Health open enrollment period.
Let’s walk through what happened, what your options may be, and how to prepare for 2027.
What Was the New York Essential Plan Cliff?
New York’s Essential Plan is a low-cost health insurance program available through the NY State of Health Marketplace. Before July 2026, eligibility extended to New Yorkers with household incomes up to 250% of the federal poverty level.
Beginning July 1, 2026, that upper limit dropped to 200% of the federal poverty level. As a result, people between 200% and 250% FPL were no longer eligible for that Essential Plan coverage.
This is called a “coverage cliff” because a relatively modest income difference could move someone from a $0-premium plan into a Qualified Health Plan (QHP) with premiums, deductibles, coinsurance, and other out-of-pocket costs.
The New York Attorney General’s Office described the change this way:
“Losing health insurance can be stressful and confusing, and New Yorkers deserve clear, reliable information as they make decisions about their care.” : Attorney General Letitia James
If your income is at or below 200% FPL, you may still qualify for the Essential Plan. If your income is above that threshold, your next coverage option may be a QHP through NY State of Health.
Why July 1 Mattered
Your Essential Plan coverage generally ended on June 30, 2026, unless your household was still eligible under the revised income rules. July 1 was the first day the new eligibility limit took effect.
That date mattered for two reasons:
- You may have lost access to your previous Essential Plan benefits.
- The loss of coverage created a limited Special Enrollment Period for a replacement QHP.
The transition period was designed to give affected New Yorkers time to compare plans and apply financial assistance. However, coverage was not automatically continued. You had to complete a new enrollment process through NY State of Health.
The practical deadline to use that transition Special Enrollment Period was August 30, 2026. Some state guidance described the qualifying event window as lasting through September 1, but because August 30 was the key marketplace deadline communicated for enrollment, it was the date to treat as the firm cutoff.
Now that the date has passed, do not assume you have no options. Check your NY State of Health account, review any notices you received, and contact NY State of Health at 1-855-355-5777 to ask whether an exception, correction, or other Special Enrollment Period may apply to your situation.
Which Income Range Was Affected?
The following figures show approximate annual household income ranges for people in the discontinued 200%–250% FPL Essential Plan category:
| Household size | Approximate annual income range |
|---|---|
| One person | $31,920–$39,900 |
| Two people | $43,280–$54,100 |
| Three people | $54,640–$68,300 |
| Four people | $66,000–$82,500 |
These numbers are useful for understanding the coverage cliff, but your eligibility is based on factors such as household size, expected annual income, tax filing status, and current program rules.
Your income estimate should reflect the year you are seeking coverage: not simply last year’s tax return. Wages, self-employment income, unemployment benefits, investment income, and other sources may affect your Modified Adjusted Gross Income, commonly called MAGI.
What Are Qualified Health Plans?
A Qualified Health Plan is an ACA-compliant health insurance plan sold through the Marketplace. QHPs cover essential health benefits, including doctor visits, hospital care, emergency services, prescription drugs, mental health treatment, laboratory services, and preventive care.
Unlike the Essential Plan, QHPs usually have a monthly premium. They may also include:
- An annual deductible, which you pay before the plan begins sharing many costs.
- Copayments, such as $25 for a primary care visit.
- Coinsurance, which is your percentage of a covered service after meeting the deductible.
- An out-of-pocket maximum, which limits your covered in-network spending during the plan year.
- Provider networks and prescription formularies, which determine where you can receive care and which medications are covered.
You can generally choose among Bronze, Silver, Gold, and Platinum plans. Bronze plans often have lower premiums but higher deductibles. Gold and Platinum plans typically cost more each month but may reduce what you pay when you use medical services.
The “cheapest” plan is not always the most affordable plan overall. A plan with a $75 monthly premium may cost more than a $150 plan if the first option has a much higher deductible and expensive specialist visits.
That is why comparing the full cost: not just the premium: is so important.
How Premium Tax Credits Can Lower Your Monthly Premium
A premium tax credit is financial assistance that reduces your monthly QHP premium. You apply for it through NY State of Health, and if approved, the credit can be sent directly to your insurance company as an advance premium tax credit.
For example, if a plan costs $400 per month and you qualify for a $250 monthly credit, your estimated premium could be $150 per month.
Your actual amount depends on your household income, household size, available plans in your area, and other eligibility factors. Access to affordable employer-sponsored coverage can also affect whether you qualify.
You can learn more about how this assistance works in Super Senior Services’ guide to premium tax credits.
Remember to update your Marketplace application if your income changes. If your income is higher than estimated, you may receive too much advance credit and have to reconcile the difference when filing your federal tax return. If your income is lower, you may qualify for additional help.
Accurate information protects both your coverage and your financial stability.
How Cost-Sharing Reductions Can Reduce Out-of-Pocket Costs
Premium tax credits lower the monthly bill. Cost-sharing reductions (CSRs) can lower what you pay when you receive care.
According to Healthcare.gov, CSRs may reduce:
- Deductibles
- Copayments
- Coinsurance
- Annual out-of-pocket maximums
To receive these extra savings, you generally must select a Silver QHP and qualify based on your household income.
This distinction matters. A Bronze plan may have a lower premium, but a Silver plan with CSR could provide a much lower deductible and more manageable office-visit costs. If you expect regular prescriptions, specialist visits, lab work, or ongoing treatment, those differences may save you more throughout the year.
When comparing QHPs, check all four of these areas:
- Monthly premium: What will you pay every month?
- Deductible: How much must you spend before the plan pays for many services?
- Provider network: Are your doctors, hospitals, and specialists included?
- Prescription formulary: Are your medications covered, and at what tier?
The right plan balances affordability with access to the care you actually use.
What to Do After the August 30 Deadline
If you missed the transition deadline, take these steps:
1. Log in to NY State of Health.
Review your eligibility notice, account messages, and current application. Your income or household information may have changed, and you may still qualify for the Essential Plan or another program.
2. Ask about another Special Enrollment Period.
A separate qualifying event: such as marriage, moving, having a baby, adoption, or losing other qualifying coverage: may create a new enrollment opportunity. NY State of Health can explain whether your circumstances qualify.
3. Confirm whether your Essential Plan termination was handled correctly.
If you believe your income, household size, or renewal information was incorrect, ask NY State of Health about correction or appeal procedures.
4. Prepare for a possible coverage gap.
Ask your doctors about self-pay rates, check whether your prescriptions have manufacturer or pharmacy assistance programs, and request financial assistance information from hospitals before receiving planned care. These steps do not replace insurance, but they may help reduce immediate expenses.
5. Start preparing for 2027 now.
Gather recent pay stubs, tax information, Social Security numbers, immigration documents if applicable, prescription lists, and provider information. Preparation makes enrollment faster and reduces the risk of choosing a plan based only on its monthly premium.
The Next Major Milestone: 2027 Open Enrollment
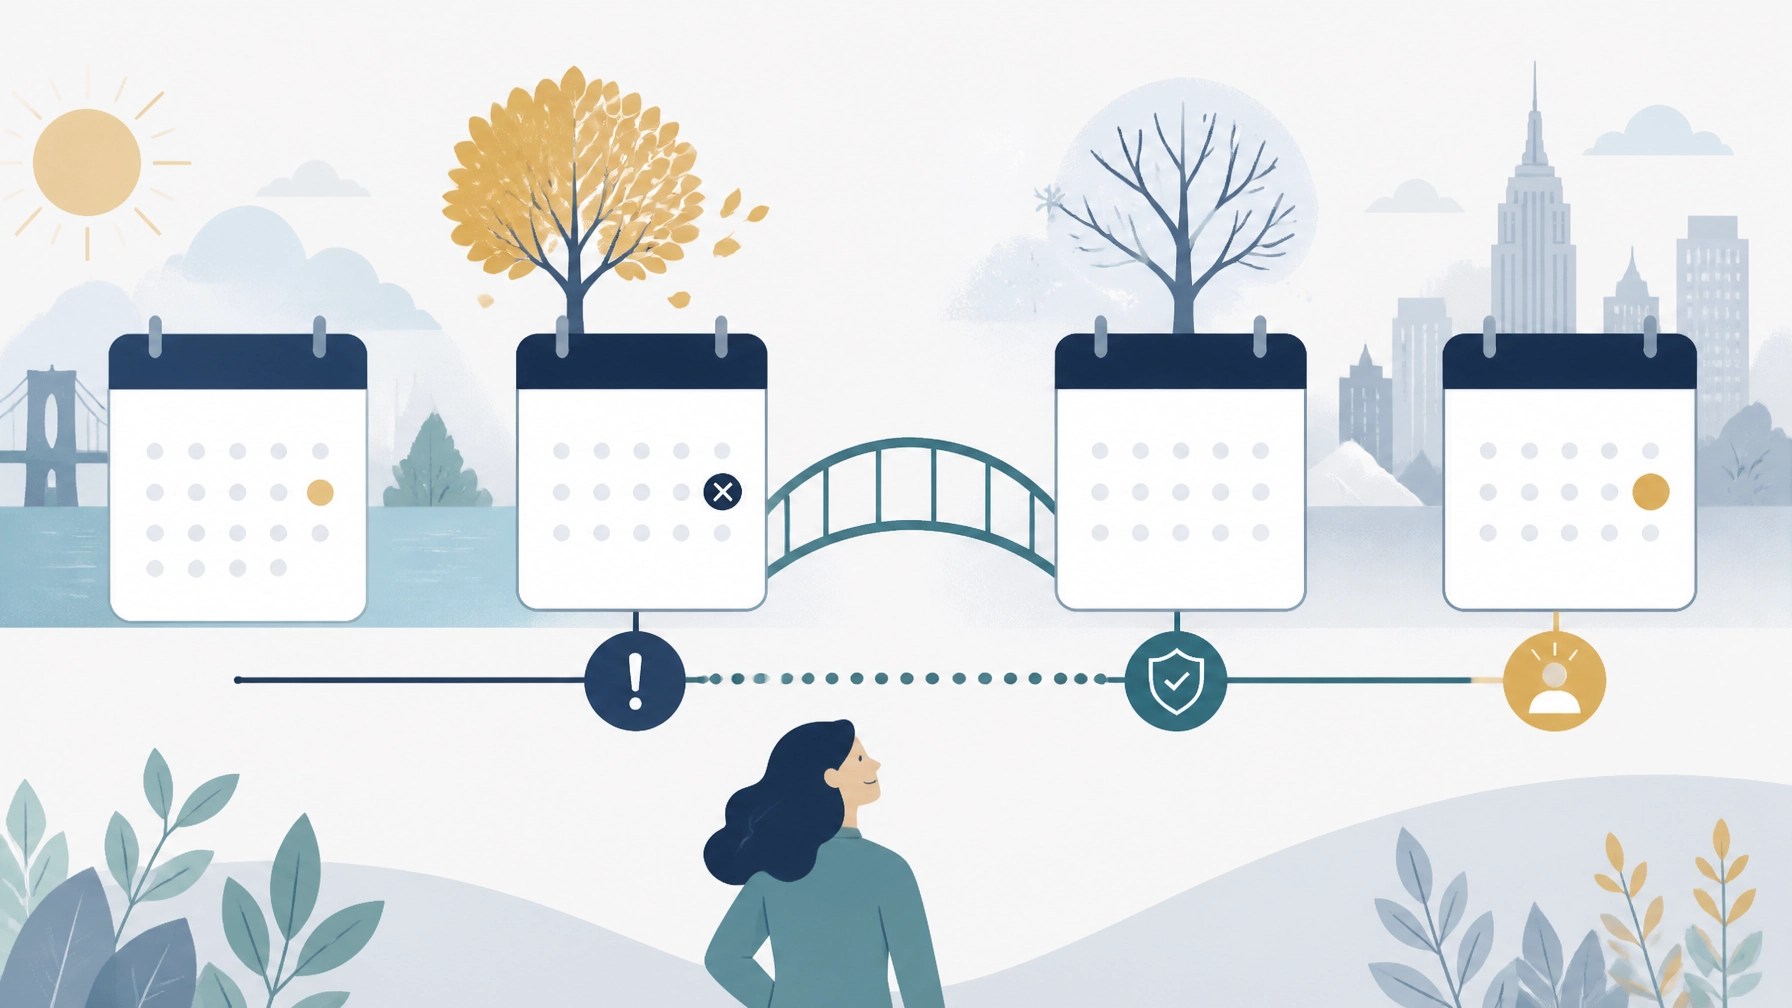
The next major opportunity to enroll in a QHP is the expected NY State of Health open enrollment period from November 1 through December 15, 2026, for coverage beginning January 1, 2027.
Mark these dates now:
- November 1, 2026: Begin comparing 2027 QHPs.
- December 15, 2026: Target deadline for January 1, 2027 coverage.
- January 1, 2027: Expected effective date if you enroll by the December deadline.
NY State of Health may provide additional enrollment details as the 2027 plan year approaches. Monitor the official NY State of Health website and review your account notifications.
Do not wait until December to compare plans. Provider networks, formularies, premiums, deductibles, and subsidy amounts can change each year. Reviewing your options early gives you time to ask questions and select coverage that fits your health needs and budget.
How Super Senior Services Can Help
The Essential Plan cliff has created real uncertainty for many New York residents. You do not have to sort through every QHP, premium estimate, provider directory, and formulary by yourself.
Super Senior Services provides personalized guidance for New Yorkers seeking individual health insurance. We can help you:
- Review your household income and expected 2027 earnings.
- Understand whether premium tax credits may lower your monthly cost.
- Compare Silver plans with potential cost-sharing reductions.
- Check doctors, hospitals, prescriptions, deductibles, and coinsurance.
- Prepare for NY State of Health open enrollment.
- Revisit your plan as your income, health needs, or household changes.
Our goal is simple: to make the process clearer, more affordable, and less overwhelming. A careful comparison today can support better health access and greater financial peace of mind tomorrow.
Compliance note: Individual NPN: Stephen Jackson, 20707378. Corporate NPN: Super Senior Services, 21536694.
Ready to review your next step? Contact Super Senior Services for personalized New York individual health insurance guidance.
Category: Individual Health