If you’ve been on the New York Essential Plan for a while, July 1, 2026, probably felt like a bit of a shock. For about 450,000 New Yorkers: specifically those of us in the 200% to 250% Federal Poverty Level (FPL) bracket: the “Essential Plan Cliff” became a reality. Because of federal funding shifts, the version of the Essential Plan we knew and loved was discontinued on that date.
But don’t panic! You aren’t being left without options. You have been moved into a Special Enrollment Period (SEP) that lasts until August 30, 2026. During this window, you can transition into a Qualified Health Plan (QHP).
While moving from a $0 or $20 monthly plan to a QHP can feel overwhelming, it’s also an opportunity to ensure your coverage actually fits your lifestyle for the second half of the year. Here at Super Senior Services, we believe in empowering you with the right info so you can make this jump with confidence.
Before you click "enroll," here are the five essential questions you need to ask yourself.
1. How Much of a "Premium Tax Credit" Do I Actually Qualify For?
When you move from the Essential Plan to a QHP, the biggest change is the monthly premium. However, since your income is between 200% and 250% FPL (roughly $31,300–$40,000 for an individual), you are likely eligible for significant Advance Premium Tax Credits (APTC).
Think of these credits as a direct discount on your monthly bill. You don't have to wait until you file your taxes to see the benefit; the marketplace applies them directly to your premium.
Ask yourself: "Based on my 2026 projected income, am I taking the full credit I'm entitled to?"
You can learn more about how these work on our What is the Premium Tax Credit? page. Getting this number right is the difference between a plan that feels like a burden and one that fits your budget.
2. High Premium or High Deductible: Which One Saves Me More?
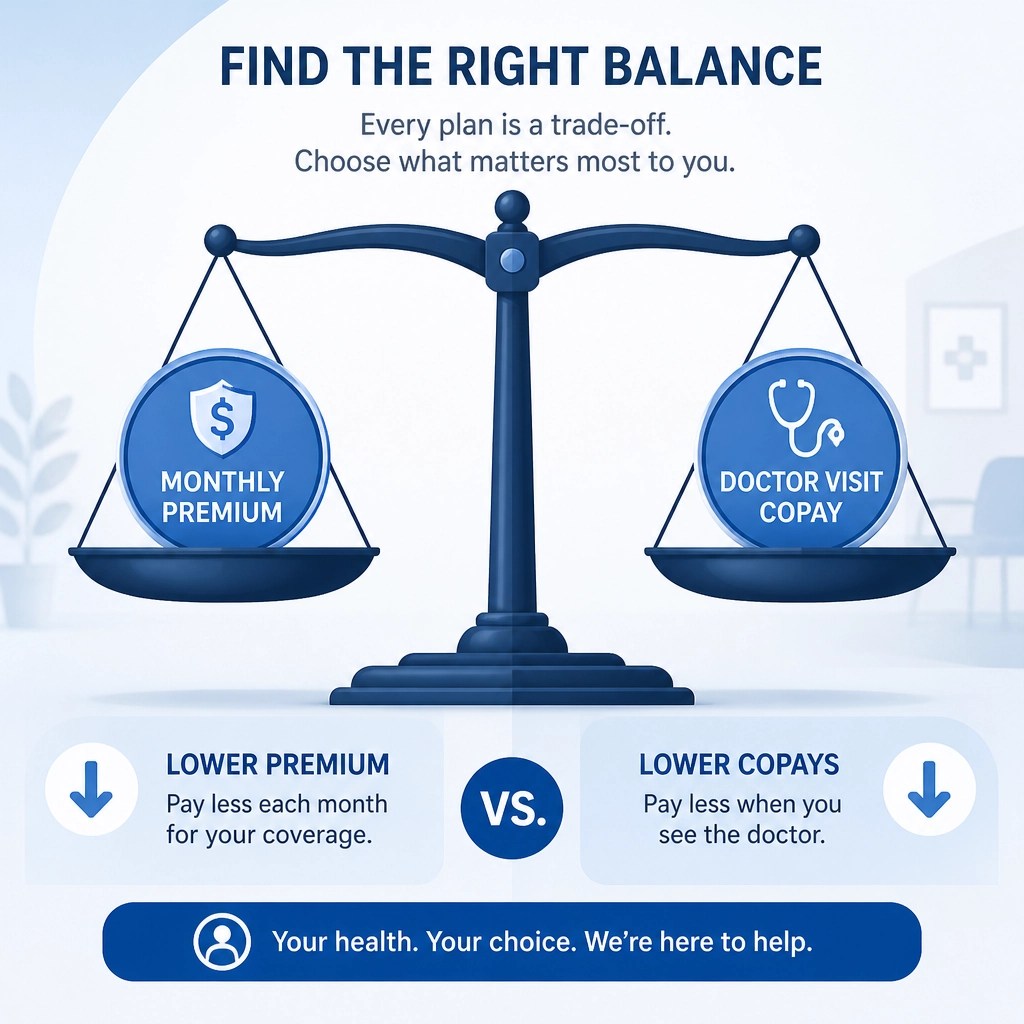
In the Essential Plan, your out-of-pocket costs were very low. In a QHP, you have to choose your "math."
- Gold/Platinum Plans: Higher monthly premiums, but lower costs when you see a doctor (low or no deductible).
- Silver/Bronze Plans: Lower monthly premiums, but you’ll pay more out-of-pocket before the insurance kicks in (higher deductibles).
The Good News: Since you are joining mid-year, your QHP deductibles and out-of-pocket maximums are often prorated for the remaining six months of 2026. This means you don’t have to hit a full year's worth of spending in just half a year! Additionally, if you stay with the same insurance carrier you had for your Essential Plan, they may carry over the money you’ve already spent this year toward your new deductible.
3. Is My Primary Care Doctor Actually in the New Network?
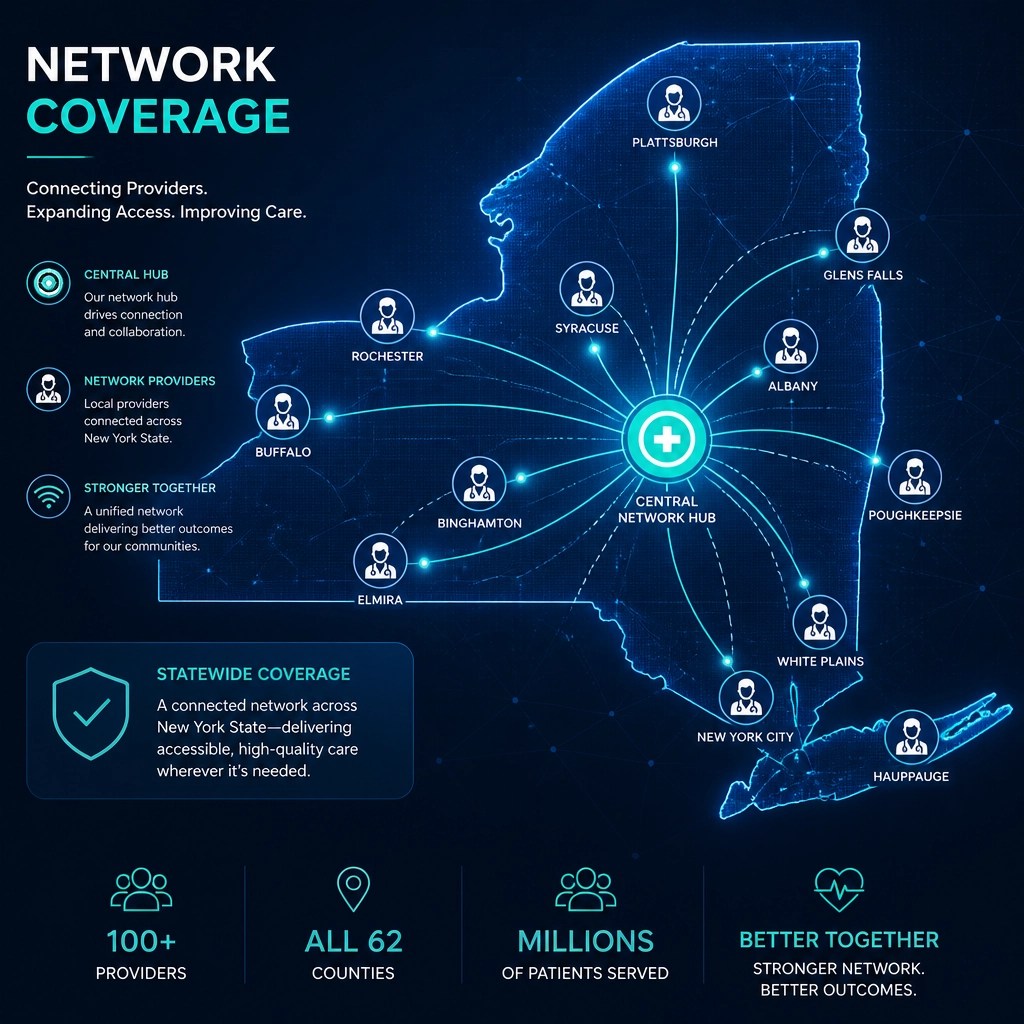
This is a big one. Just because an insurance company (like MetroPlus, Fidelis, or UnitedHealthcare) offered an Essential Plan doesn't mean their QHP uses the exact same network of doctors.
Before you commit, you must verify that your "must-have" doctors and specialists are in-network for the specific QHP you are looking at. Choosing an out-of-network plan could result in thousands of dollars in unexpected bills. We always recommend checking the provider directory on NY State of Health or asking us to do a comprehensive benefit review for you.
4. Should I Opt for Retroactive Coverage Back to July 1?
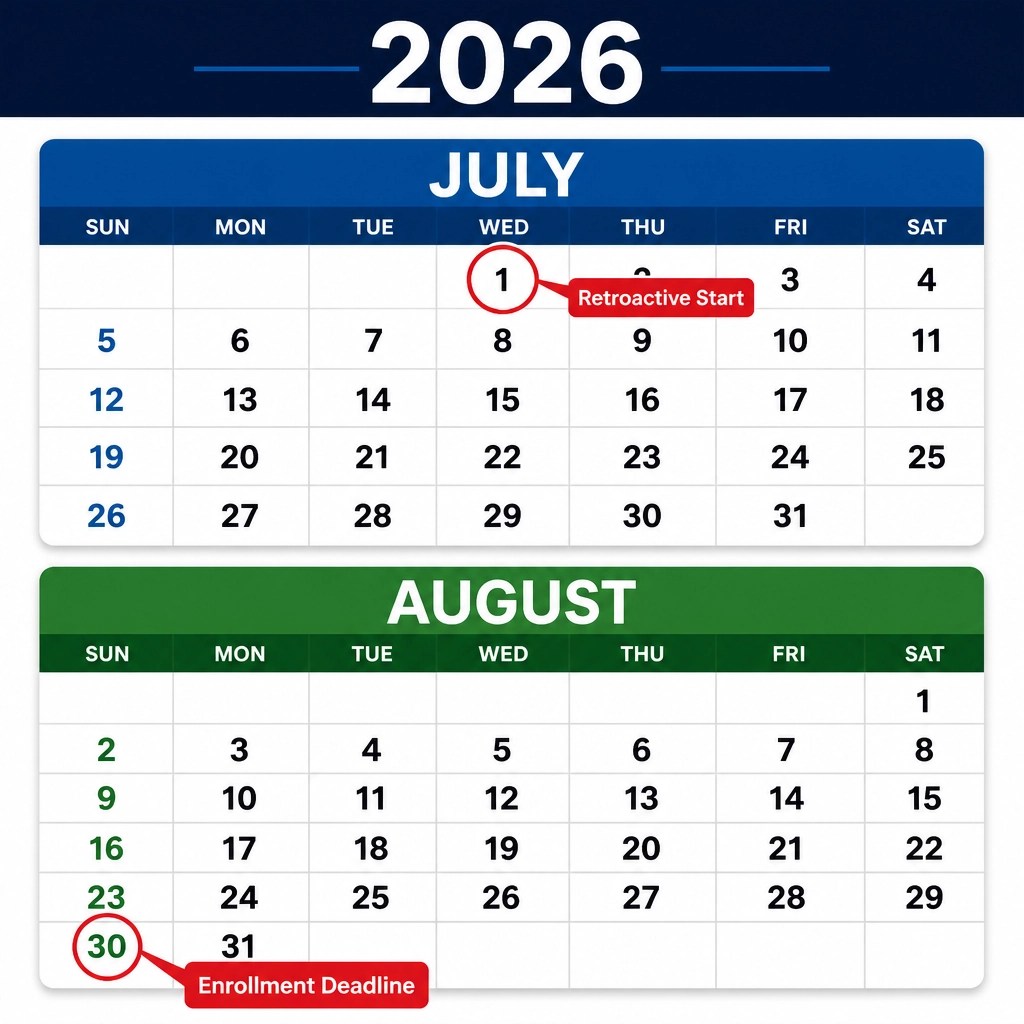
Because of the unique nature of this "cliff," New York is allowing residents to backdate their new coverage to July 1, 2026.
Why this matters: If you had a doctor’s visit or filled a prescription between July 1 and today, choosing the retroactive option means those costs can be covered by your new plan.
The Catch: You will owe the monthly premiums for July and August even if you sign up on August 29th.
If you didn’t have any medical needs in July, you might choose a September 1 start date to save on those two months of premiums. However, if you want "peace of mind" and no gaps in coverage, the retroactive option is your best friend.
5. How Does This Transition Prepare Me for Future Medicare Choices?
While you might be focused on individual health insurance right now, this transition is actually a great "practice run" for when you eventually qualify for Medicare. The research you're doing now on premiums, networks, and drug formularies is very similar to what you'll do during a Medicare enrollment guide process.
For instance, understanding the trade-offs between a QHP's monthly cost and its coverage is a lot like comparing Medicare Advantage 2026 updates versus Medicare Supplement plans 2026. If you are approaching age 65, navigating this "cliff" now will make you an expert when it's time to look at Medigap plans 2026 or other Medicare coverage options.
Why You Don’t Have to Do This Alone
Navigating the NY State of Health marketplace can feel like learning a second language. Between "coinsurance," "prorated deductibles," and "APTC eligibility," it’s easy to get a headache.
At Super Senior Services, we specialize in taking the "complex" and making it "simple." Whether you are looking for individual health insurance in New York or trying to decide between Medicare Advantage vs Medigap, we provide personalized guidance with transparency and trust.
Remember: The deadline to secure your QHP coverage is August 30, 2026.
Don't wait until the final hour to find out your doctor isn't in-network or that you could have saved $100 a month with a different plan. We’re here to help you find affordable coverage tailored to your lifestyle and budget.
Ready to bridge the cliff?
Let’s review your options together. We’ll help you compare plans, check your doctors, and ensure you’re getting every tax credit you deserve.
Click here to explore your plan options or reach out to Stephen Jackson today for a personalized review.
Expert guidance. Better outcomes. Peace of mind.
Compliance Information:
Stephen Jackson, Individual NPN: 20707378
Super Senior Services, Corporate NPN: 21536694
{“@type”:”BlogPosting”,”image”:”https://cdn.marblism.com/gzTG0KLPGaz.webp”,”author”:{“name”:”Stephen Jackson”,”@type”:”Person”},”@context”:”https://schema.org”,”headline”:”NY Essential Plan Cliff: 5 Questions to Ask Before Choosing Your QHP (Before the August 30 Deadline)”,”keywords”:”NY Essential Plan, QHP transition 2026, New York health insurance, Special Enrollment Period NY, Medicare Advantage 2026 updates, Medicare Supplement plans 2026″,”publisher”:{“logo”:{“url”:”https://cdn.marblism.com/C0g4dPNXBgP.jpg”,”@type”:”ImageObject”},”name”:”Super Senior Services”,”@type”:”Organization”},”description”:”Are you affected by the New York Essential Plan cliff? Learn the 5 vital questions to ask before the August 30 deadline to ensure you choose the best Qualified Health Plan (QHP) for your needs.”,”datePublished”:”2026-07-25″,”articleSection”:”Individual Health”}