If your New York small business health insurance plan renews on January 1, 2027, you may receive quotes labeled HMO, EPO, PPO, or HSA-eligible HDHP. These labels are more than insurance jargon. They determine where employees can receive care, whether referrals are required, how much they may pay at the doctor’s office, and how much financial risk they carry when something unexpected happens.
Compliance note: Individual NPN: Stephen Jackson: 20707378 | Corporate NPN: Super Senior Services: 21536694
WordPress category: businesshealth
The lowest premium is not always the lowest-cost plan. A better approach is to match the plan design to how your employees actually use doctors, hospitals, specialists, prescriptions, and preventive care.
Start with the network, not the premium
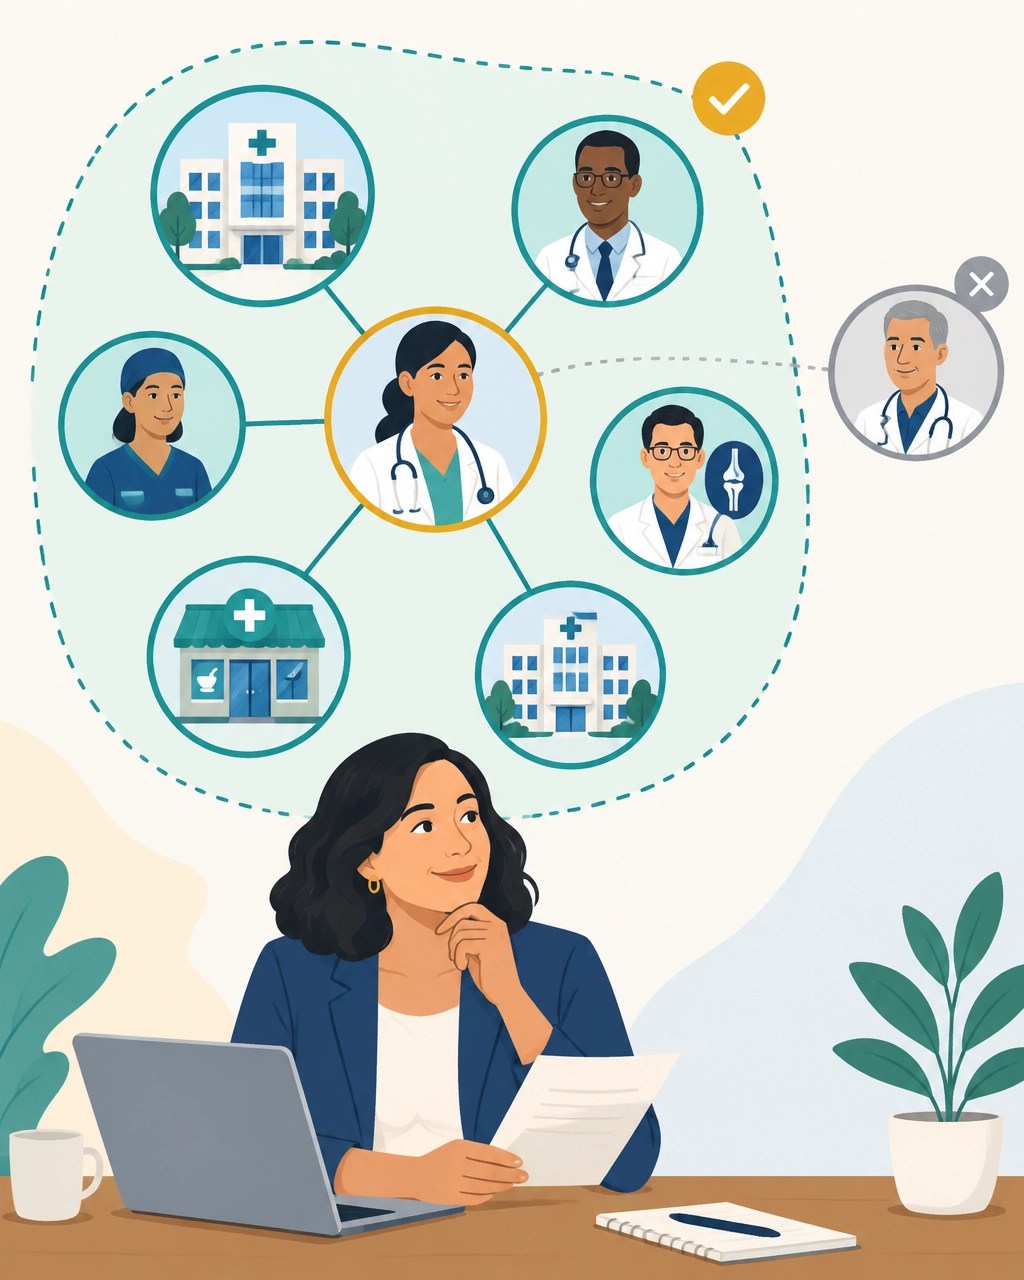
A provider network is the group of doctors, hospitals, pharmacies, and other healthcare professionals contracted with a health plan. HealthCare.gov explains:
“Some types of plans restrict your provider choices or encourage you to get care from the plan’s network… Others pay a greater share of costs for providers outside the plan’s network.”
HealthCare.gov
That distinction matters. Before you compare monthly rates, ask whether your employees’ preferred physicians and local hospitals participate in each quoted network.
Plan and carrier availability can vary by New York county. Consequently, two businesses with the same number of employees, but located in different counties, may receive different plan options, networks, and premiums.
HMO: Predictable costs with coordinated care
A Health Maintenance Organization (HMO) generally requires employees to use in-network providers except in emergencies. Many HMOs also assign each member a primary care provider who coordinates care and may issue referrals to specialists.
How it works
- Network: Usually in-network only, except for emergencies.
- Referrals: Often required before seeing certain specialists.
- Cost sharing: Frequently uses copayments for office visits and prescriptions, with a deductible and coinsurance for more significant services.
- Day-to-day experience: Employees typically pay a set amount when they visit a primary care doctor, specialist, or urgent care center.
- Best fit: Employees who value coordinated care, predictable copayments, and a strong local network.
For example, an HMO might charge a $30 primary care copay and a $60 specialist copay. An employee with several routine visits may appreciate knowing the approximate cost before the appointment.
The trade-off is less flexibility. If an employee wants to see a doctor outside the network, the plan may provide little or no coverage. That is why checking local hospitals and physicians is essential before selecting an HMO.
EPO: Broad in-network freedom without referrals
An Exclusive Provider Organization (EPO) also generally covers care only inside the plan’s network, except for emergencies. However, employees typically do not need a referral to see a specialist.
How it works
- Network: In-network providers only, except for emergencies.
- Referrals: Usually not required.
- Cost sharing: May include copayments, deductibles, and coinsurance.
- Day-to-day experience: Employees can often schedule directly with an in-network dermatologist, orthopedist, behavioral health provider, or other specialist.
- Best fit: Employees who want direct access to specialists but are comfortable staying within a defined network.
An EPO may be a useful middle ground. It can offer more direct access than a traditional HMO while avoiding the higher premiums sometimes associated with broad out-of-network coverage.
Still, “no referral required” does not mean “any doctor is covered.” Employees should confirm network participation before scheduling care.
PPO: More provider flexibility, usually at a higher price
A Preferred Provider Organization (PPO) gives employees financial incentives to use in-network providers, but it generally also offers coverage for out-of-network care. Referrals are usually not required.
How it works
- Network: In-network and out-of-network coverage may be available.
- Referrals: Usually not required.
- Cost sharing: In-network care may have a lower deductible and coinsurance. Out-of-network care usually costs more and may have a separate deductible and out-of-pocket maximum.
- Day-to-day experience: Employees have greater freedom to choose doctors and hospitals, but they must understand the financial consequences of leaving the network.
- Best fit: Employees with established specialists, employees who travel, or teams that prioritize provider choice.
For example, a PPO may pay 70% after the deductible for an out-of-network visit, leaving the employee responsible for the remaining 30%. In addition, the provider may bill above the plan’s allowed amount. That difference, sometimes called balance billing, may not count toward the plan’s out-of-pocket maximum.
A PPO can offer peace of mind for employees who need flexibility. However, the additional premium may not be worthwhile for a workforce that rarely uses out-of-network care.
HSA-eligible HDHP: Lower premiums paired with higher upfront costs
An HSA-eligible high-deductible health plan (HDHP) generally has a higher deductible and lower premium than a traditional copay plan. Employees can pair it with a Health Savings Account (HSA) if they meet federal eligibility requirements.
An HSA may receive tax-advantaged contributions from the employee, employer, or both. Employer contributions are especially valuable because they help employees manage the deductible.
For 2027 planning, the figures provided for an HSA-eligible HDHP are:
- Minimum self-only deductible: $1,750
- Minimum family deductible: $3,500
- Maximum self-only out-of-pocket limit: $8,700
- Maximum family out-of-pocket limit: $17,400
- HSA contribution limit: $4,500 self-only and $9,000 family
Employees age 55 or older may have an additional catch-up contribution opportunity, subject to federal rules. Review IRS Publication 969 and confirm the final figures and eligibility requirements before enrollment.
How it feels for employees
An HDHP may cover preventive services before the deductible, but employees often pay the negotiated cost of other care until they meet the deductible. The plan then begins applying coinsurance or copayments according to its benefits.
For a healthy single employee who has few medical expenses, the lower premium can be attractive. For an employee managing prescriptions, therapy, specialist appointments, or a planned procedure, the higher upfront exposure may be difficult without savings or employer HSA support.
A practical cost example: premium savings versus medical spending
Suppose an HSA-eligible HDHP has a $1,750 self-only deductible and your business contributes $750 to the employee’s HSA.
A competing plan has a $750 deductible, but its monthly premium is $120 higher. Over 12 months, that higher premium costs an additional $1,440.
For a healthy employee who rarely uses care:
- The lower-premium HDHP saves $1,440 in annual premium.
- The employer’s $750 HSA contribution helps cover eligible expenses.
- The employee may come out ahead if medical spending remains low.
Now consider a family with a planned surgery. A lower-deductible plan may cost more in premiums but have a lower out-of-pocket maximum and more predictable cost sharing. If the family reaches the HDHP’s higher out-of-pocket limit, the lower-premium design may no longer be the better financial choice.
The lesson is simple: compare annual premiums plus expected medical spending, not premiums alone. Every employee will not use the plan in the same way.
Where POS plans fit
A Point-of-Service (POS) plan may still appear in New York small-group quotes. POS plans typically offer lower costs for in-network care, provide some out-of-network coverage, and often require a primary care referral before seeing a specialist.
If a POS plan is quoted, ask:
- Is a referral required for every specialist?
- Is out-of-network coverage subject to a separate deductible?
- Do out-of-network charges count toward the out-of-pocket maximum?
- Which local hospitals and physicians participate?
The apples-to-apples comparison checklist
When reviewing your 2027 renewal, compare each quote using the same categories:
- Total annual premium: Include both the employer and employee portions.
- Individual and family deductible: Confirm whether deductibles are embedded or aggregate.
- Copayments: Review primary care, specialist, urgent care, emergency room, and prescription copays.
- Coinsurance: Identify the percentage employees pay after meeting the deductible.
- Out-of-pocket maximum: Check individual and family limits, including what expenses count.
- Network breadth: Verify local hospitals, physicians, urgent care centers, and behavioral health providers.
- Formulary and prescription tiers: Review generic, preferred brand, non-preferred brand, and specialty drug costs.
- Referral rules: Confirm whether employees need referrals for specialists or certain procedures.
- Out-of-network exposure: Look for separate deductibles, higher coinsurance, balance billing, and exclusions.
- Summary of Benefits and Coverage: Use the plan’s SBC materials to compare benefits in a standardized format.
A narrow-network Bronze plan and a broad-network Gold plan are not comparable simply because both are labeled “health insurance.” Metal levels describe the general share of covered costs the plan pays; network type describes how employees access care. You need to evaluate both.
New York premium context for 2027
New York’s prior-approval process requires insurers to submit proposed premium changes for review before using them. The New York Department of Financial Services reviews rate filings, including factors such as claims experience, utilization, administrative expenses, and projected healthcare costs.
New York also uses an 82% small-group medical loss ratio standard as part of its rate framework. In plain language, this means insurers are expected to spend at least 82 cents of each premium dollar on healthcare claims and quality-related expenses, subject to applicable rules.
For another comparison resource, visit the NY State of Health Small Business Marketplace. It allows eligible employers to compare Bronze, Silver, Gold, and Platinum options available in their area.
Ask employees before you choose
A short, anonymous survey can reveal concerns that are invisible on a rate sheet. Ask employees:
- Which doctors and hospitals do you want to keep?
- Do you take ongoing prescriptions?
- Do you regularly see a specialist?
- Would you prefer predictable copayments or a lower payroll deduction?
- Would you use an HSA if the business contributed money?
- Are you comfortable using a narrower network?
Offering two plan tiers can also help a mixed workforce. For example, you might offer a lower-premium HSA-eligible HDHP and a richer copay plan, while using a consistent employer contribution policy. Employees then have meaningful choice without requiring your business to manage unrelated plan designs.
Which plan type may fit your team?
- Young, healthy single employees: An HSA-eligible HDHP may be appealing if the premium savings and employer HSA contribution are meaningful.
- Families with ongoing care: An HMO or lower-deductible plan may provide more predictable costs.
- Employees with a specific specialist or hospital: A PPO may be worth considering, but confirm whether that provider is actually in-network.
- Teams that want predictable payroll deductions: An HMO or copay-focused EPO may be easier to understand and budget for.
- Mixed workforces: Two plan tiers may provide flexibility while keeping your employer contribution strategy consistent.
Your January 1, 2027 renewal checklist
Before making a final decision:
- Request complete quotes and SBC documents.
- Confirm county-specific availability.
- Verify doctors, hospitals, pharmacies, and formularies.
- Calculate total annual employer and employee premiums.
- Compare deductibles, coinsurance, copayments, and out-of-pocket maximums.
- Model a low-use employee, a family with regular care, and a high-use employee.
- Review HSA eligibility and employer contribution rules.
- Survey employees about provider and prescription needs.
- Explain the decision clearly before enrollment begins.
The right plan is the one that balances affordability, network access, employee satisfaction, and financial stability. Super Senior Services simplifies these comparisons with a personalized benefits review, practical guidance, and transparent support for your New York small business. Contact Stephen Jackson to begin preparing for your 2027 renewal.