If you’re running a business in the Empire State, you already know that New York does things a little differently. From the best bagels in the world to the unique rhythm of the subway, our state has its own set of rules. The same is true for health insurance.
Navigating the world of group health insurance can feel like trying to find a parking spot in Midtown at noon: confusing, stressful, and sometimes seemingly impossible. But providing great benefits isn’t just about checking a box; it’s about protecting your most valuable asset: your team.
At Super Senior Services, we spend our days helping New York business owners simplify this process. We’ve seen where the tripwires are hidden. To help you get ahead of the curve, we’ve rounded up the seven most common mistakes New York small business owners make with their group health insurance: and exactly how you can fix them before your next renewal.
1. Waiting for a "National" Open Enrollment Window
One of the most common myths we hear is that you can only start a group health insurance plan during the individual Open Enrollment Period (usually November through January).
The Reality: In New York, small business owners (groups with 1 to 100 employees) can actually apply for coverage at any time of the year. New York operates on a rolling enrollment basis for small groups.
The Fix: Don’t wait until the end of the year to start looking. If your current plan is eating into your margins or your employees are unhappy with their coverage, you can make a change now. However, most businesses choose to align their plan year with the calendar year for simplicity. If you want a January 1st start date, the best time to start comparing plans is right now.
"The best time to plant a tree was 20 years ago. The second best time is today." – Chinese Proverb (And the same goes for reviewing your benefits!)
2. Falling Short of Participation and Contribution Requirements
New York carriers have specific rules about how many people need to join the plan and how much you, the employer, must pay. This is often where small startups or very small businesses get stuck.
- Participation Rule: Most carriers in NY require at least 75% of your eligible employees to enroll in the plan. (Note: Employees who have coverage through a spouse, Medicare, or VA benefits usually count as "valid waivers" and won't count against your percentage.)
- Contribution Rule: Generally, you are required to contribute at least 50% of the premium for the employee-only (single) coverage.
The Fix: Before you get your heart set on a specific plan, do a quick "headcount check." If you have 10 employees and 5 of them want to stay on their spouse's plan, make sure you document those waivers correctly so you still meet the 75% threshold. If you're struggling to meet the 50% contribution, we can help you look at high-deductible options that lower the overall premium.
3. Chasing the Lowest Premium (The "Bronze" Trap)
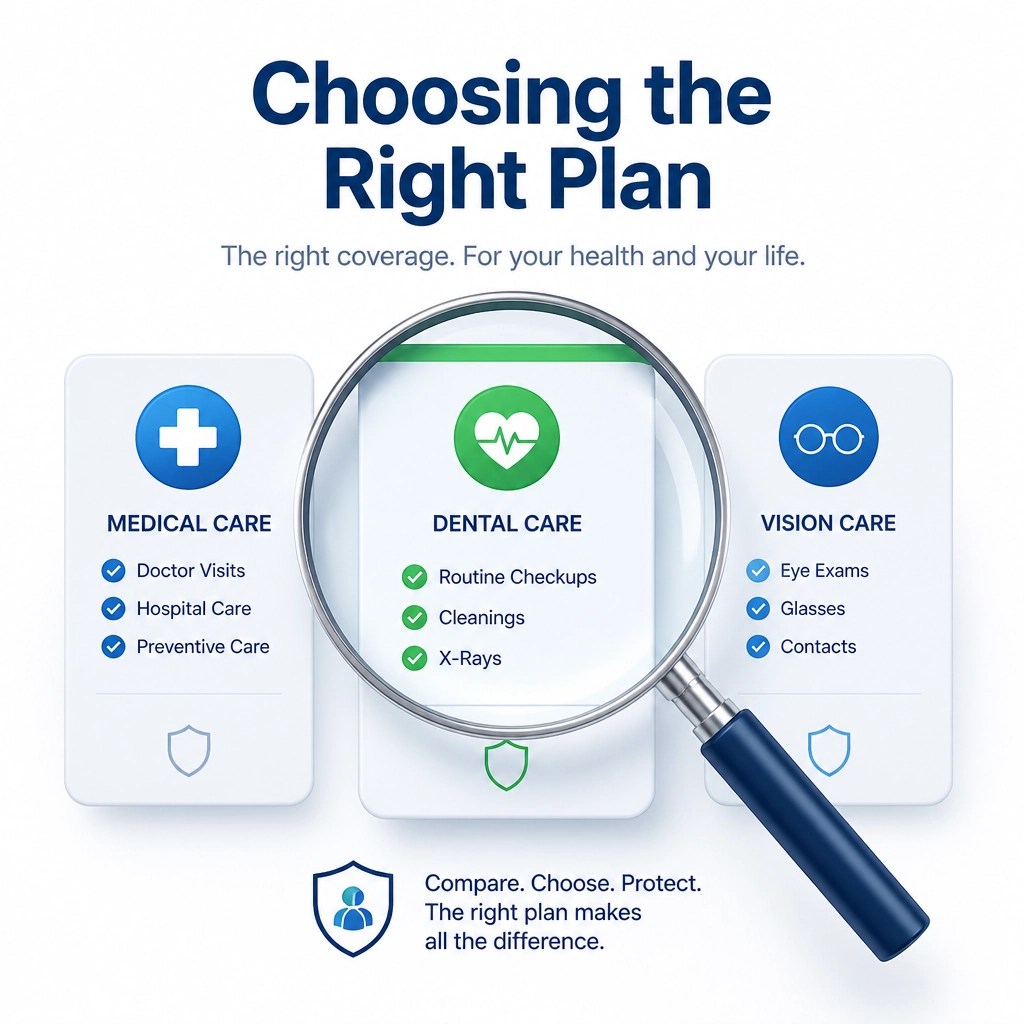
It’s tempting to look at a spreadsheet and circle the smallest number. In the insurance world, that’s usually a "Bronze" level plan. While these plans have the lowest monthly premiums, they often come with high deductibles: sometimes $6,000 or more per person.
The Reality: If your employees are young and healthy, a Bronze plan might work. But if you have a team with families or chronic health needs, a low-premium plan can actually become a financial burden for them. High out-of-pocket costs can lead to "benefit dissatisfaction," which defeats the purpose of offering insurance to keep your team happy.
The Fix: Look at the "Total Cost of Ownership." Sometimes, moving to a Silver or Gold plan costs the employer only $40–$50 more per month per employee but saves the employee thousands in deductibles. We recommend offering a "choice" model where you contribute a set dollar amount and let the employee pick the "Metal Level" that fits their family’s needs.
4. Leaving the SHOP Tax Credit on the Table
Did you know the federal government offers a tax credit specifically for small businesses that provide health insurance? It’s called the Small Business Health Care Tax Credit, and many New York owners don't even know they qualify.
To qualify, you generally need:
- Fewer than 25 full-time equivalent (FTE) employees.
- An average annual salary below a certain threshold (around $62,000, adjusted for inflation).
- To pay at least 50% of employee premium costs.
- To purchase your plan through the NY State of Health (NYSOH) Marketplace (SHOP).
The Fix: If you buy a plan "off-exchange" (directly from a carrier without going through the state marketplace), you might be disqualified from this credit. This credit can be worth up to 50% of your premium contributions. Talk to your broker about whether a SHOP-certified plan is right for your group.
5. Forgetting New York-Specific Mandates (DBL and PFL)
New York is one of the few states that requires employers to provide Statutory Disability (DBL) and Paid Family Leave (PFL). These are often managed alongside your health insurance, but they are separate requirements.
The Reality: If you set up health insurance but forget your DBL/PFL obligations, you could face significant fines from the NYS Workers' Compensation Board.
The Fix: Ensure your benefits package is "NY Compliant." When we set up a group plan at Super Senior Services, we don't just look at medical; we make sure your disability and family leave requirements are bundled or accounted for so you can sleep soundly knowing you’re fully compliant with state law.
6. Ignoring Provider Networks
New York has a massive healthcare system, but not every doctor is in every network. A plan that looks great on paper might not include the local hospital system that your employees actually use.
The Reality: Network "narrowing" is a trend where carriers offer lower premiums by restricting the list of doctors. If your office is in Westchester but the plan's best doctors are all in Manhattan, your employees are going to be frustrated.
The Fix: Before signing a contract, ask for a "Network Check." We can take a list of your employees' preferred doctors and hospitals and run them against the carrier databases to ensure there is a match. It’s a small step that prevents a massive headache later.
7. Trying to Do It All Yourself
You’re an expert at running your business. Whether you’re managing a restaurant in Brooklyn or a tech firm in Albany, your time is your most valuable resource. Trying to master the 2,000-page ACA handbook and New York state regulations is a full-time job in itself.
The Reality: Many business owners try to navigate the NY State of Health Marketplace on their own, only to get overwhelmed by the jargon.
The Fix: Partner with a specialist. In New York, using a broker like Super Senior Services costs you exactly $0 in extra premiums. Our commissions are already built into the insurance rates by the carriers. You get expert guidance, personalized plan recommendations, and a dedicated advocate for your employees at no additional cost to your business.
"Excellence is not a skill. It is an attitude." – Ralph Marston. We bring that attitude to every plan review we conduct for our New York clients.
How to Fix Your Plan Before the Next Quarter
If you're worried you've made one of these mistakes, don't panic. The beauty of the New York market is its flexibility. Here is your 3-step action plan:
- Gather Your Data: Get a current census of your employees (ages and zip codes) and a copy of your most recent renewal notice.
- Survey Your Team: Ask them what they value most: lower premiums, lower deductibles, or specific doctor networks.
- Schedule a Review: Don't wait for a crisis. A proactive review can often uncover savings of 10% to 15% just by switching carriers or adjusting your contribution strategy.
At Super Senior Services, we specialize in helping New York businesses find the "sweet spot" between affordability and high-quality care. We take the complexity of the NYS small business insurance rules and turn them into a clear, easy-to-follow strategy for your company.
Ready to Simplify Your Business Health Insurance?
Don't let another month of high premiums and confusing paperwork slow your business down. Whether you have 2 employees or 50, you deserve a plan that works as hard as you do.
Contact Stephen Jackson and the team at Super Senior Services today for a personalized Benefit Review. We’ll help you navigate the New York marketplace with transparency, trust, and expertise.
👉 Click here to schedule your New York Small Business Health Review
Compliance Information:
Stephen Jackson, Individual NPN: 20707378
Super Senior Services, Corporate NPN: 21536694
{“@type”:”BlogPosting”,”image”:”https://cdn.marblism.com/qbb5ex_pvwS.webp”,”author”:{“name”:”Penny”,”@type”:”Person”},”@context”:”https://schema.org”,”headline”:”7 Mistakes New York Small Business Owners Make With Group Health Insurance (And How to Fix Them Before Open Enrollment)”,”keywords”:”New York Small Business Health Insurance, Group Health Insurance NY, SHOP Marketplace, DBL PFL New York, Employee Benefits NY”,”publisher”:{“logo”:{“url”:”https://superseniorservices.com”,”@type”:”ImageObject”},”name”:”Super Senior Services”,”@type”:”Organization”},”description”:”Learn the 7 common mistakes New York small business owners make with group health insurance, including participation rules, tax credits, and NY-specific mandates.”,”datePublished”:”2026-07-24″,”articleSection”:”Business Health”}