Running a small business in New York is an incredible journey, but let’s be honest: one of the biggest line-item headaches you face every year is providing health insurance for your team. Between rising medical premiums, confusing state regulations, and the constant balancing act of keeping your business financially healthy while taking care of your employees, finding affordable coverage can feel like an uphill battle.
If you are a New York employer looking ahead to 2026, you don't have to choose between breaking your budget and offering zero benefits. There are powerful, cost-saving strategies available specifically for NY small businesses: from modern defined-contribution health reimbursement arrangements to state-backed programs and federal tax credits.
At Super Senior Services, we believe that simplifying your healthcare options is key to sustainable growth. Let’s break down the most effective ways you can lower your group health insurance costs this year without sacrificing the quality of coverage your team deserves.
1. Modern Alternatives: QSEHRA and ICHRA in New York
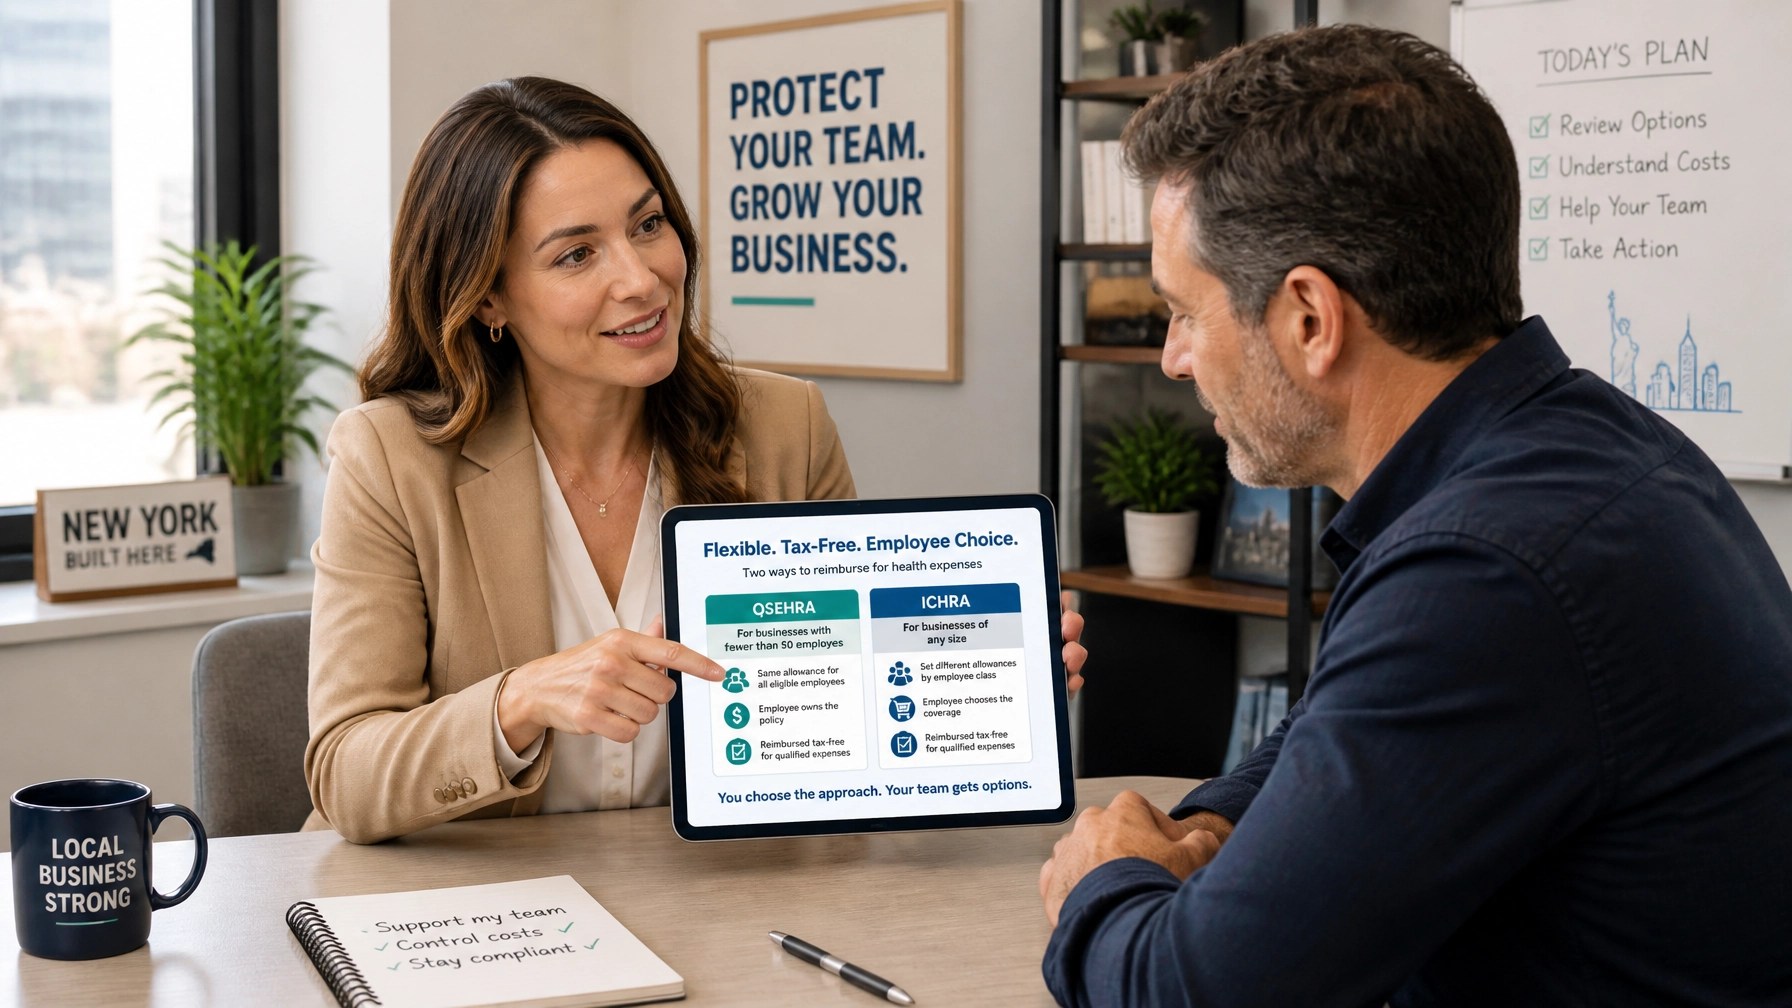
Traditional group health insurance plans require you to pick a single plan design and shoulder a massive chunk of the premium. But what if you could give your employees a fixed, predictable monthly allowance instead? That is where Health Reimbursement Arrangements (HRAs) come in.
Qualified Small Employer HRA (QSEHRA)
If you have fewer than 50 full-time employees and do not offer a traditional group health plan, a QSEHRA lets you reimburse your team tax-free for individual health insurance premiums and out-of-pocket medical expenses.
For 2026, the IRS-set maximum annual reimbursement limits are:
- Single coverage: Up to $6,450 per year (approximately $537.50 per month).
- Family coverage: Up to $13,100 per year (approximately $1,091.66 per month).
"QSEHRA completely transforms how small business owners budget for benefits. Instead of guessing how much premiums will spike next year, you set a fixed monthly contribution that fits your cash flow, while your employees get to choose the exact individual plan that fits their life."
Individual Coverage HRA (ICHRA)
An ICHRA is available to New York businesses of any size. Unlike QSEHRA, there are no annual IRS caps on contributions. Better yet, ICHRA allows you to divide your workforce into different "classes" (such as full-time, part-time, or salaried versus hourly) and offer different allowance amounts to each class. Employees use their ICHRA allowance to buy individual plans on or off the NY State of Health marketplace.
Note: Neither QSEHRA nor ICHRA are group plans, meaning they operate independently from traditional group insurance and do not qualify for the SHOP tax credit.
2. Maximizing the Federal Small Business Health Care Tax Credit via SHOP
If minimizing your tax liability is your top priority, you will want to look closely at the Small Business Health Care Tax Credit.
Available through the NY State of Health Small Business Marketplace, this federal credit is designed specifically for small employers who want to offer traditional group coverage. To qualify, your business generally must meet three core criteria:
- Have fewer than 25 full-time equivalent (FTE) employees.
- Pay average annual wages below the prevailing threshold (roughly $53,000 per worker, adjusted annually).
- Contribute at least 50% of the cost of employee-only premiums for the lowest-cost plan offered.
If you qualify, the financial payoff is substantial: the maximum federal tax credit covers up to 50% of the group premiums you pay (up to 35% for tax-exempt organizations) for two consecutive years.
As our team at Super Senior Services always reminds business owners: "The tax credit bridges the gap between what you can afford and what your employees need. Pairing a SHOP plan with expert guidance ensures you leave no money on the table."
3. Unlocking Hidden Savings with Section 125 Cafeteria Plans
If you currently offer a traditional group health plan, you might be missing out on a simple payroll mechanism that saves both you and your employees thousands of dollars: a Section 125 Cafeteria Plan.
A Section 125 plan allows your employees to pay their portion of health insurance premiums using pre-tax dollars through payroll deductions.
- How it helps your employees: Their taxable income is reduced by the amount they contribute toward health insurance, lowering their personal federal, state, and local income taxes.
- How it helps your business: Because employee premium contributions are deducted before payroll taxes are calculated, your business saves on its share of FICA taxes (Social Security and Medicare matching, which saves roughly 7.65% on every pre-tax dollar contributed).
Setting up a Section 125 plan is straightforward, and the payroll tax savings often offset the nominal administrative costs of maintaining the plan.
4. Leveraging Healthy NY for Lower-Wage Workforces
For New York small business owners who operate in industries with modest margins or lower-wage workforces: and who haven’t offered group health insurance in the past 12 months: the Healthy NY program remains a valuable option.
Healthy NY is a state-sponsored initiative designed to make comprehensive group coverage more accessible and affordable for smaller employers. It focuses on essential health benefits while keeping premiums lower than standard commercial group plans by streamlining administrative rules and focusing on cost-effective care delivery.
Reviewing whether your business qualifies for Healthy NY can instantly open the door to comprehensive coverage without straining your operating budget.
How Super Senior Services Guides Your NY Business
Navigating New York’s complex healthcare landscape doesn't have to be overwhelming. Whether you are weighing the flexibility of an ICHRA, trying to qualify for the federal small-business health care tax credit on the NY marketplace, or setting up a Section 125 plan, you deserve a partner who puts transparency and trust at the core.
At Super Senior Services, we specialize in helping businesses across New York find affordable coverage options tailored directly to your lifestyle, team size, and budget. We simplify the comparison of trusted carriers, provide comprehensive benefit reviews, and offer annual check-ins to ensure your health plan continues to support your evolving business goals.
Ready to lower your group health insurance costs in 2026? Contact our expert team today for a personalized consultation and let us help you secure the right plan for your business.
Compliance & Licensing Information:
- Individual NPN: 20707378 (Stephen Jackson)
- Corporate NPN: 21536694 (Super Senior Services)
- Authorized Service Area for Business Health Insurance: New York (NY)
{“@type”:”Article”,”author”:{“name”:”Stephen Jackson”,”@type”:”Person”},”@context”:”https://schema.org”,”headline”:”How NY Small Business Owners Can Save on Group Health Insurance in 2026″,”publisher”:{“logo”:{“url”:”https://superseniorservices.com/favicon.ico”,”@type”:”ImageObject”},”name”:”Super Senior Services”,”@type”:”Organization”},”description”:”Discover practical cost-saving strategies for New York small business owners offering group health insurance in 2026, including QSEHRA/ICHRA, Section 125 plans, and tax credits.”,”datePublished”:”2026-07-31″,”mainEntityOfPage”:{“@id”:”https://superseniorservices.com/business”,”@type”:”WebPage”}}