As we look toward 2026, the landscape of Medicare is undergoing some of its most significant shifts in years. If you are approaching 65 or already navigating the complexities of your healthcare coverage, you might feel a bit overwhelmed by the technical jargon and shifting regulations. We understand that your health insurance isn't just a monthly premium; it is the foundation of your financial stability and your peace of mind.
At Super Senior Services, we believe that understanding your options should be a conversation between friends, not a struggle with a manual. Whether you are living in the sunshine of Florida, the mountains of North Carolina, or the busy streets of New York, these 2026 updates will directly impact how you access care and how much you pay for it.
In this guide, we will break down the crucial changes to Medicare Advantage, the continuing evolution of Part D prescription drug coverage, and what to expect from Medicare Supplement (Medigap) plans in the coming year. Our goal is to empower you to make an informed decision that fits your unique lifestyle and budget.
Medicare Advantage 2026: Stronger Protections for Your Care
Medicare Advantage (Part C) plans continue to be a popular choice for many seniors due to their "all-in-one" nature, often including dental, vision, and hearing coverage. However, one of the biggest frustrations for many enrollees has been the issue of retroactive denials for inpatient hospital stays.
The Centers for Medicare & Medicaid Services (CMS) has issued a "Final Rule" for 2026 that introduces vital protections for you. Consequently, if your Medicare Advantage plan approves an inpatient admission through prior authorization, they generally cannot later deny coverage for that stay based on a lack of medical necessity.
No More Retroactive Denials
In the past, some patients were caught in a stressful loop where a plan would approve an admission, only to downgrade it to "observation status" or deny it entirely after the patient had already been discharged. Starting in 2026, plans may only reopen an approved admission for "obvious error or fraud." This means that once your stay is approved, you can focus on recovery rather than worrying about a surprise hospital bill.
Faster Prior Authorizations
We know that when you need a procedure, waiting weeks for an answer is anxiety-inducing. New federal regulations starting in January 2026 require health insurers to process prior authorization requests much more quickly:
- Standard requests: Decisions must be made within 7 days.
- Urgent requests: Decisions must be made within 72 hours.
These changes are designed to ensure that the "Advantage" in your plan actually results in faster, more reliable access to the care you need.
Prescription Drug Coverage: The $35 Insulin Cap and Beyond
Managing prescription costs is often the top priority for our clients. The Inflation Reduction Act continues to reshape Medicare Part D in 2026, making life-saving medications more affordable.
The $35 Insulin Cap is Now Formal
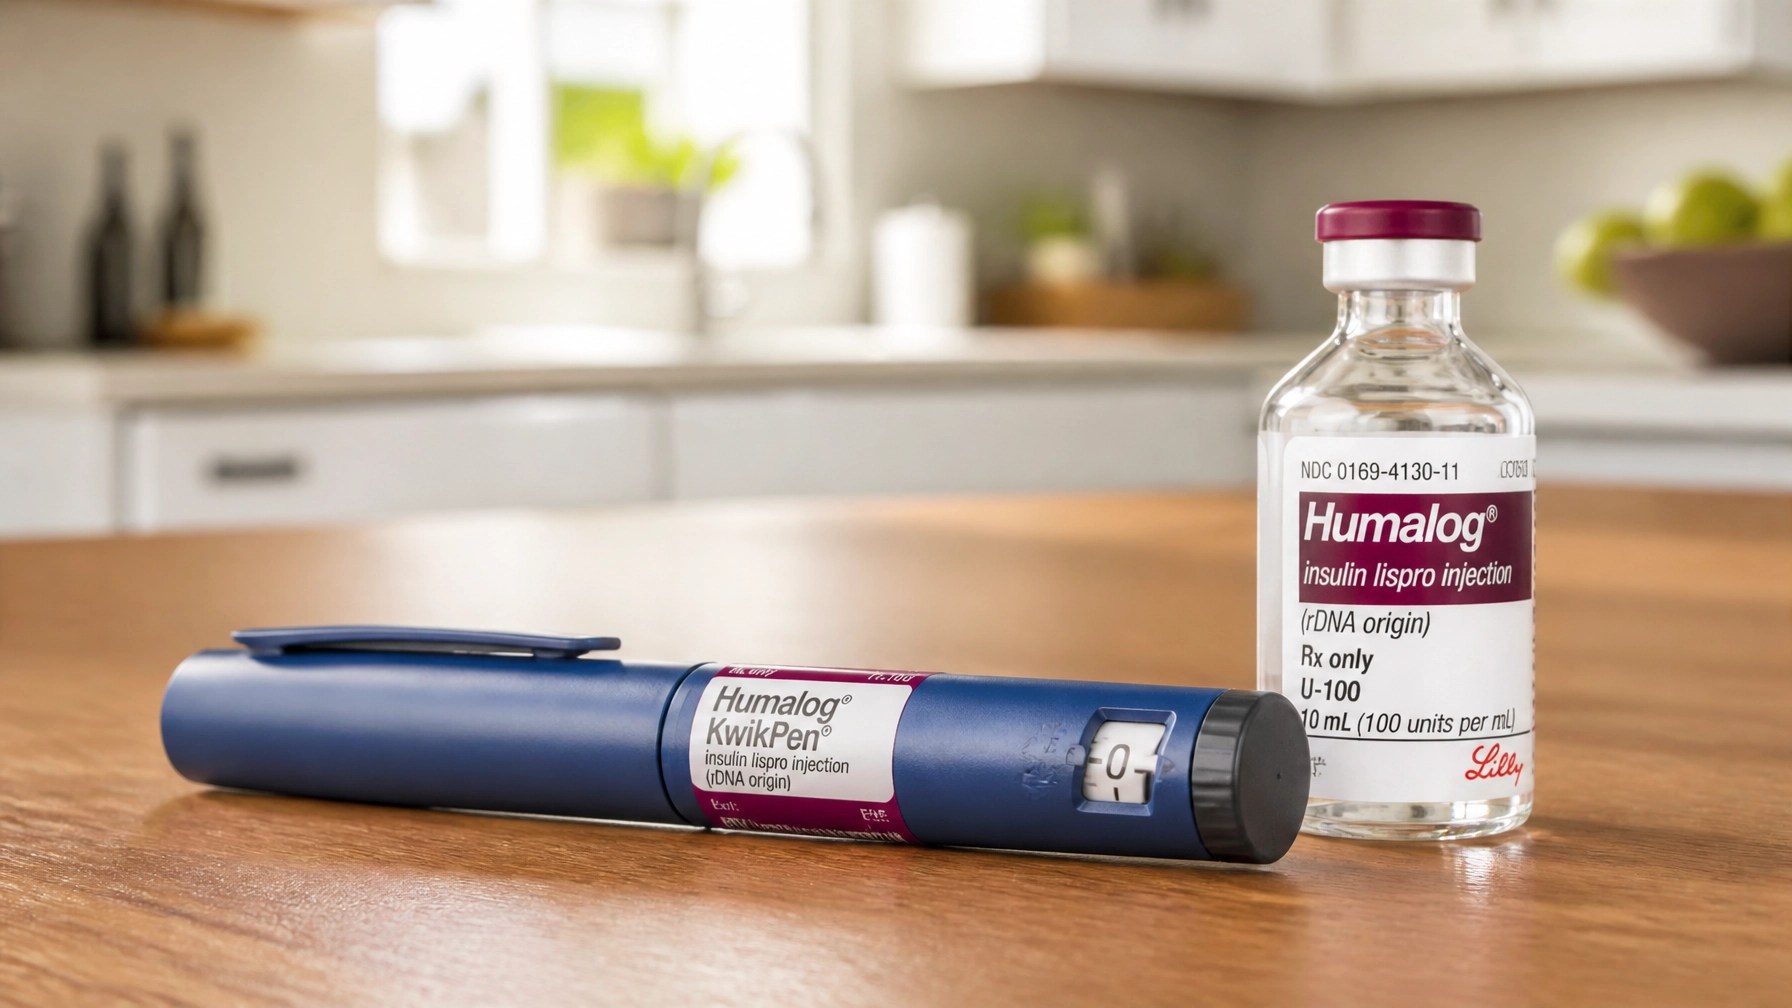
One of the most life-changing updates is the formal codification of the $35 monthly cap on insulin. For many years, seniors faced skyrocketing costs for insulin, sometimes forced to ration their doses. For 2026 and beyond, your Part D deductible does not apply to covered insulin products. Your monthly cost-sharing for each covered insulin product will be capped at the lesser of $35 or a percentage of the negotiated price.
The Medicare Prescription Payment Plan (M3P)
Additionally, 2026 will see further refinements to the Medicare Prescription Payment Plan. This program allows you to spread your out-of-pocket prescription costs into monthly installments throughout the year, rather than paying a large sum at the pharmacy counter in January or February. This "smoothing" of costs is a powerful tool for maintaining financial stability on a fixed income.
"Ensuring that seniors never have to choose between their groceries and their life-saving medication is at the heart of these new regulations." : Industry Expert
Medicare Supplement (Medigap) 2026: Stability and Predictability
If you prefer the freedom to see any doctor in the country who accepts Medicare, a Medicare Supplement (Medigap) plan might be the right fit for you. Unlike Medicare Advantage, Medigap works alongside Original Medicare to pay for your "gaps" in coverage, like deductibles and coinsurance.
Popular Plan Options
- Plan G: This remains the most popular choice for new enrollees. It covers nearly all out-of-pocket costs except for the Part B deductible. It provides the highest level of coverage and maximum peace of mind.
- Plan N: Often viewed as the "budget-friendly" alternative, Plan N offers lower premiums. In exchange, you pay small copayments (up to $20) for some office visits and up to $50 for emergency room visits that don't result in an inpatient stay.
2026 Financial Benchmarks
While Medigap premiums vary by carrier and location, the costs for Original Medicare deductibles are standardized. For 2026, you should be prepared for the following:
- Part A Deductible (Hospital): Projected at $1,736. This covers your first 60 days of inpatient hospital care in a benefit period.
- Part B Deductible (Medical): Projected at $283. This is the amount you pay for outpatient services (like doctor visits and lab tests) before Medicare starts to pay its share.
Because these deductibles tend to rise annually, many seniors find that the predictable monthly premium of a Medigap plan is easier to budget for than the potentially high out-of-pocket costs of Original Medicare alone.
Your Step-by-Step Enrollment Guide
Choosing the right time to enroll is just as important as choosing the right plan. Missing a deadline can result in lifelong late enrollment penalties.
1. Initial Enrollment Period (IEP)
This is your first chance to sign up for Medicare. It is a 7-month window that includes:
- The 3 months before you turn 65.
- The month you turn 65.
- The 3 months after you turn 65.
2. General Enrollment Period (GEP)
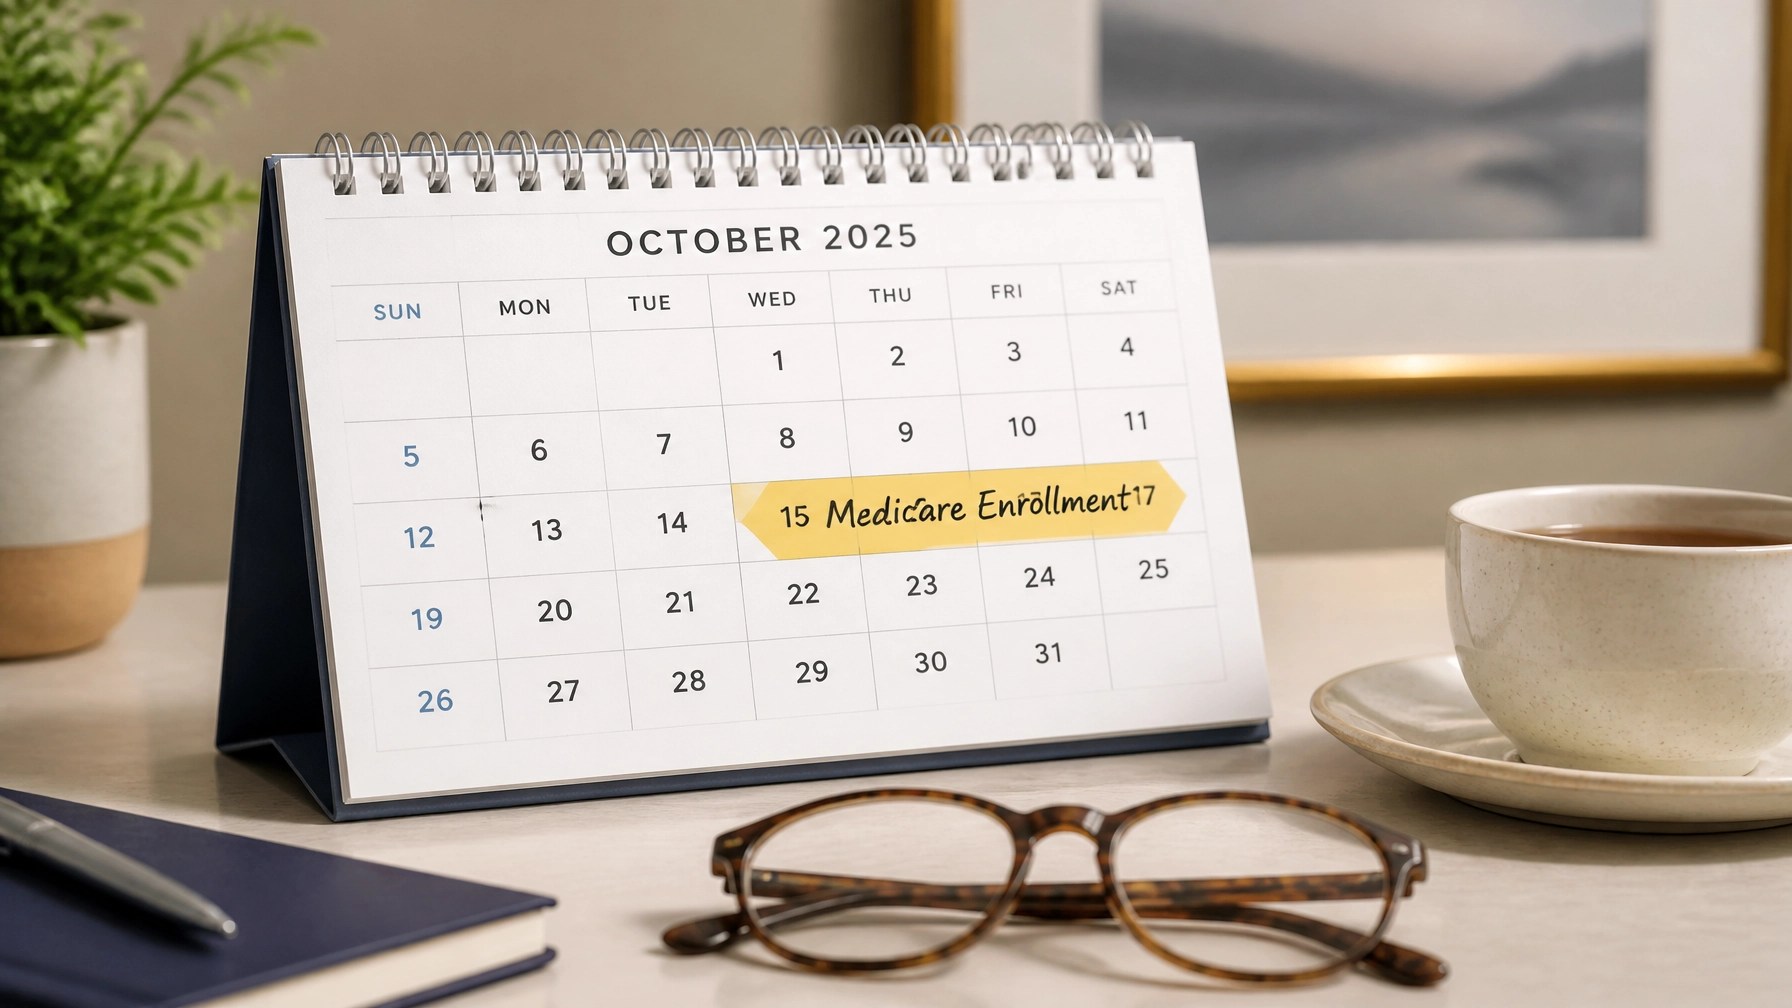
If you missed your IEP and don't qualify for a special window, you can sign up between January 1 and March 31 each year. Your coverage will then begin the first day of the month after you sign up.
3. Special Enrollment Period (SEP)
Life happens! If you are still working and have employer coverage, or if you move to a new state like New York or North Carolina, you may qualify for an SEP. This allows you to join or change plans outside of the standard windows without penalty.
Why Local Expertise Matters
Navigating healthcare is personal. A plan that works for someone in Texas might not be the best option for someone in Virginia or Georgia. Each state has different "trusted providers" and network strengths.
At Super Senior Services, we specialize in providing personalized plan recommendations for residents across:
- Florida (FL)
- Georgia (GA)
- Texas (TX)
- Tennessee (TN)
- North Carolina (NC)
- South Carolina (SC)
- Virginia (VA)
- New York (NY)
We don't just look at the premiums; we conduct comprehensive benefit reviews to ensure your doctors are in-network, your specific medications are on the formulary, and the plan aligns with your lifestyle. Whether you are looking for a $0 premium Medicare Advantage plan or a robust Plan G Medigap policy, we are here to guide you with transparency and trust.
Take the Next Step Toward Peace of Mind
The changes coming in 2026 are designed to make Medicare more reliable and affordable, but they also add new layers of complexity. You don't have to navigate this journey alone.
Are you ready to find the plan that fits your life and your budget? Let’s simplify the process together.
Contact us today for a personalized review of your 2026 options.
- Explore Plans: https://superseniorservices.com/medplans
- Talk to an Expert: Visit our Contact Page to schedule a consultation.
We look forward to helping you secure the healthcare coverage you deserve.
Compliance Information:
- Individual NPN (Stephen Jackson): 20707378
- Corporate NPN (Super Senior Services): 21536694
{“@type”:”BlogPosting”,”image”:”https://cdn.marblism.com/WFs5Oh_uTgs.webp”,”author”:{“name”:”Stephen Jackson”,”@type”:”Person”},”@context”:”https://schema.org”,”headline”:”Medicare 2026: What’s New, What’s Changed, and How to Choose the Right Plan for You”,”keywords”:”Medicare 2026, Medicare Advantage 2026, Part D 2026, Medigap Plan G, Medicare Enrollment Guide, Insulin Cap Medicare”,”publisher”:{“logo”:{“url”:”https://cdn.marblism.com/C0g4dPNXBgP.jpg”,”@type”:”ImageObject”},”name”:”Super Senior Services”,”@type”:”Organization”},”description”:”A comprehensive guide to 2026 Medicare changes, including Medicare Advantage protections, Part D insulin caps, and 2026 Medigap deductibles.”,”datePublished”:”2026-07-20″,”articleSection”:”Medicare”,”mainEntityOfPage”:{“@id”:”https://superseniorservices.com/medicare/medicare-2026-whats-new-whats-changed”,”@type”:”WebPage”}}