Choosing the right Medicare coverage can feel like learning a brand-new language. With annual updates to deductibles, premiums, and out-of-pocket limits, staying informed is essential for protecting both your health and your financial security. If you are approaching retirement or reviewing your current healthcare setup for 2026, you are likely weighing your options between Original Medicare, Medicare Advantage, and Medicare Supplement (Medigap) plans.
Among Medigap policies, two options consistently stand out for their exceptional popularity and value: Plan G and Plan N.
As industry experts at Super Senior Services, we help residents across Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, and New York navigate these exact decisions every day. In this comprehensive guide, we will break down the key differences between Plan G and Plan N, highlight the crucial 2026 cost adjustments, and help you determine which strategy delivers the best peace of mind for your lifestyle and budget.
Understanding Your 2026 Medicare Baseline: What Has Changed?
Before comparing specific Medigap plans, it is vital to understand the foundational numbers set by Medicare for 2026. Because Medicare Supplement plans are designed to fill the "gaps" left by Original Medicare (Parts A and B), any shift in Medicare's base deductibles directly impacts your overall healthcare budget.
For 2026, the key federal benchmarks include:
- Part B Annual Deductible: Increased to $283 (up from $257 in 2025). You must pay this amount out of pocket before your Part B coinsurance benefits begin.
- Part A Hospital Deductible: Increased to $1,736 per benefit period (up from $1,676 in 2025). Both Plan G and Plan N cover this inpatient deductible in full.
- Standard Part B Monthly Premium: Approximately $202.90 for most beneficiaries, reflecting a standard annual adjustment in healthcare costs.
As health insurance expert Dr. Robert Vance notes, "Navigating Medicare isn't just about picking a plan: it's about matching your anticipated healthcare utilization with a financial structure that protects you from unforeseen medical events."
To explore how these figures apply to your local area, you can review official resources on Medicare.gov and CMS.gov.
Plan G vs. Plan N: Core Benefit Structures at a Glance
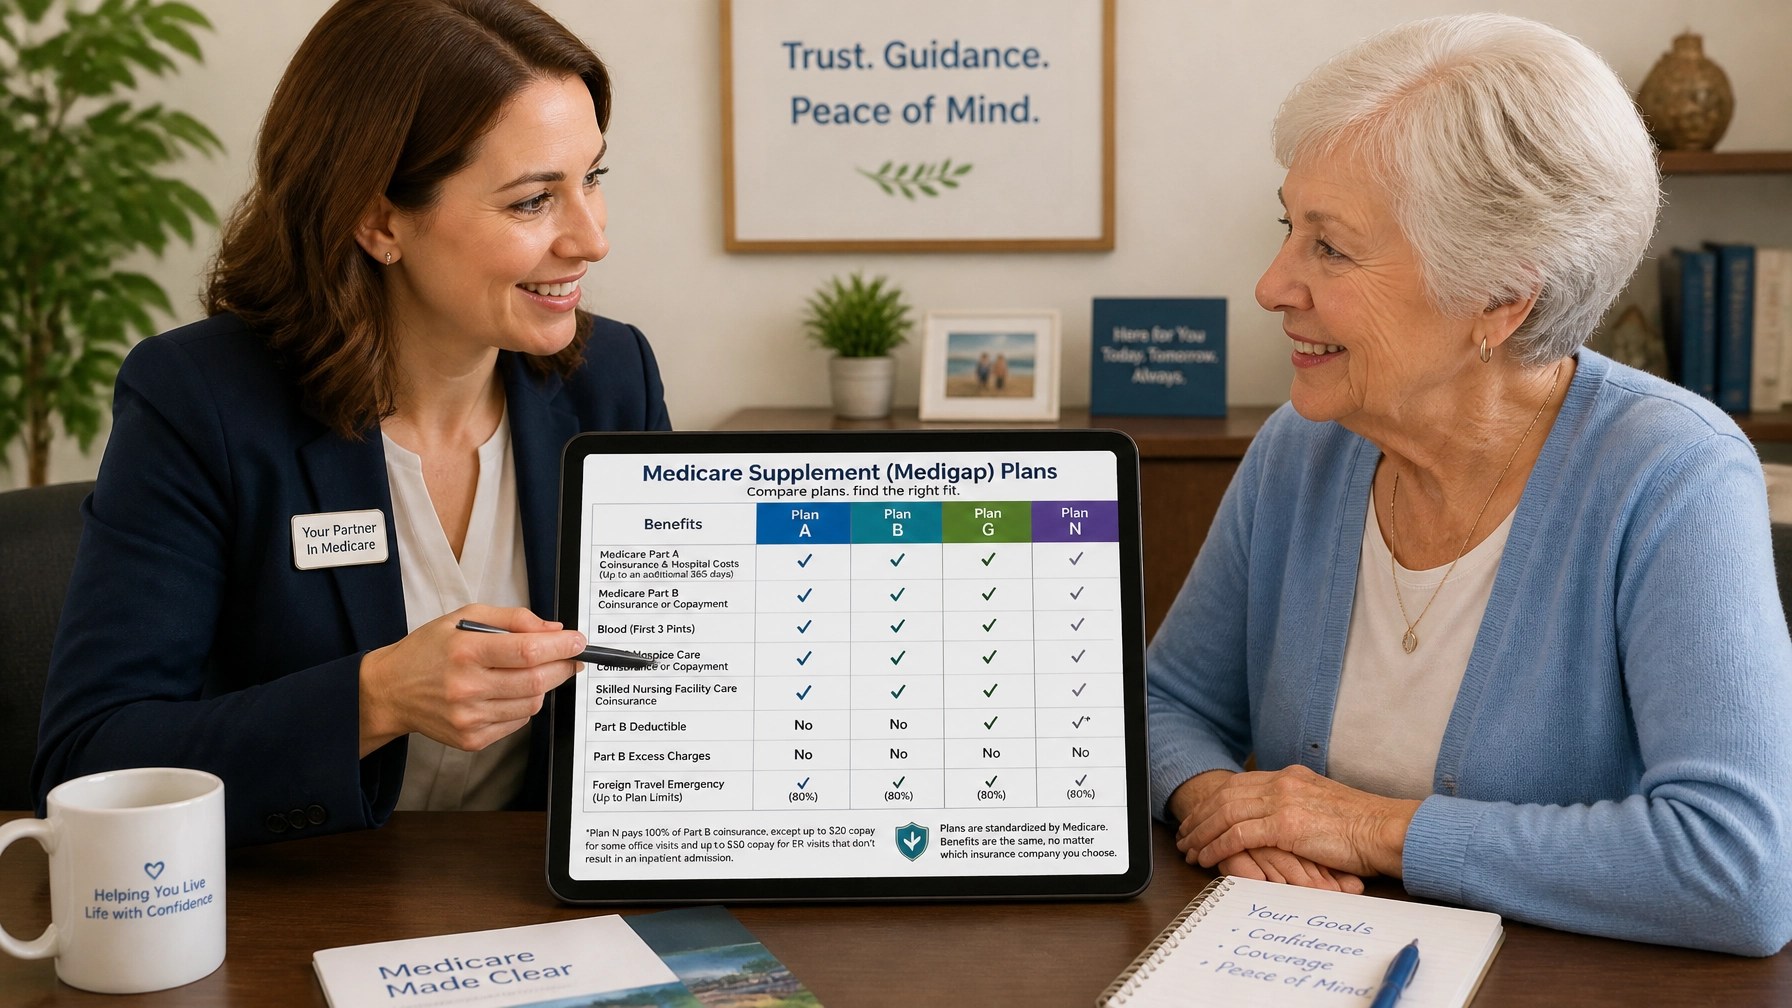
Both Plan G and Plan N are standardized Medigap policies regulated by the federal government. This means that whether you purchase Plan G from Carrier A or Carrier B, the core benefits are identical by law. However, how they handle out-of-pocket expenses creates a distinct choice between predictability and monthly savings.
What Plan G Offers in 2026
Plan G is widely regarded as the gold standard for comprehensive, predictable healthcare coverage.
- Zero Copays: Once you satisfy the annual Part B deductible ($283), Plan G covers 100% of all remaining Medicare-approved Part B coinsurance and excess charges. When you visit a doctor, specialist, or outpatient facility, you will owe nothing out of pocket (e.g., $0 copay for routine doctor visits).
- Part B Excess Charge Protection: If a healthcare provider does not accept Medicare assignment, they are legally permitted to charge up to 15% above the Medicare-approved amount. Plan G covers these excess charges entirely, shielding you from surprise medical bills.
- Cost Predictability: For seniors who visit doctors frequently, manage chronic conditions, or simply want complete peace of mind with zero out-of-pocket surprises, Plan G offers unmatched financial stability.
What Plan N Offers in 2026
Plan N is designed for proactive seniors who want robust Medigap protection while enjoying lower monthly premiums in exchange for modest cost-sharing at the point of service.
- Office and ER Copays: Under Plan N, you may have a copay of up to $20 for routine office visits and up to $50 for emergency room visits (if you are not admitted as an inpatient).
- Part B Excess Charges Not Covered: Plan N does not cover Part B excess charges. If you see a provider who does not accept Medicare assignment, you are responsible for paying that extra 15% charge. Fortunately, the vast majority of physicians nationwide accept Medicare assignment.
- Lower Monthly Premiums: Because of these small cost-sharing requirements, Plan N typically features monthly premiums that are $20 to $50 lower than Plan G (saving you roughly $240 to $600 per year in fixed premium costs).
Detailed Comparison Table: Plan G vs. Plan N (2026)
| Feature / Benefit | Medicare Supplement Plan G | Medicare Supplement Plan N |
|---|---|---|
| Part A Hospital Deductible ($1,736 in 2026) | 100% Covered | 100% Covered |
| Part B Annual Deductible ($283 in 2026) | Not Covered (You pay $283 once) | Not Covered (You pay $283 once) |
| Part B Coinsurance (Standard 20%) | 100% Covered after deductible | Covered (subject to office/ER copays) |
| Doctor Office Visit Copays | $0 per visit | Up to $20 per visit |
| Emergency Room Copays (if not admitted) | $0 per visit | Up to $50 per visit |
| Part B Excess Charges | 100% Covered | Not Covered (You may owe up to 15%) |
| Foreign Travel Emergency (80%) | Covered up to plan limits | Covered up to plan limits |
| Typical Monthly Premium Range | Higher ($140 – $300+/mo) | Moderate ($120 – $220+/mo) |
Which Strategy is Best for Your Health and Budget?
Selecting between Plan G and Plan N comes down to balancing your monthly cash flow with your expected healthcare utilization. At Super Senior Services, we believe in personalized guidance because no two retirees have the exact same medical needs.
Choose Plan G If:
- You value maximum financial predictability and want to walk out of every medical appointment knowing your bill is completely covered.
- You visit specialists, undergo regular physical therapy, or manage ongoing health conditions that require frequent physician interaction.
- You prefer the security of knowing that Part B excess charges are fully taken care of, regardless of which doctor you see.
Choose Plan N If:
- You are generally healthy, maintain an active lifestyle, and only visit the doctor a few times a year.
- You want to pocket meaningful monthly savings (e.g., $30 less per month translates to $360 saved annually) and are comfortable paying a small $20 copay when you do see a physician.
- You verify that your preferred doctors accept Medicare assignment, minimizing any risk of excess charges.
As healthcare advocate Sarah Jenkins points out, "The smartest insurance strategy isn't buying the most expensive plan on the market; it's selecting the coverage level that aligns with your actual lifestyle and protects your retirement savings from unexpected shocks."
To explore tailored rate comparisons across trusted carriers in your local area, visit our dedicated Medicare Plans Page.
Step-by-Step Enrollment Guidance and Annual Reviews
Navigating enrollment deadlines and carrier underwriting can feel daunting, but you do not have to do it alone. Whether you are turning 65 and enrolling in Medicare for the first time or looking to switch Medigap policies during your open enrollment window, having an expert partner makes all the difference.
Here is how Super Senior Services simplifies your journey:
- Comprehensive Benefit Review: We analyze your current medical needs, prescription drugs, and preferred doctors to identify potential cost-saving opportunities.
- Simplified Comparison: We compare trusted, top-rated insurance carriers in your state to find the most competitive rates for Plan G or Plan N.
- Expert Guidance: We walk you through every step of the paperwork, ensuring a seamless transition with total transparency and trust at our core.
- Annual Reviews: Healthcare needs evolve year after year. We conduct proactive annual check-ins to ensure your plan continues to serve you best.
We are proud to serve residents and businesses across eight states: Florida, Georgia, Texas, Tennessee, North Carolina, South Carolina, Virginia, and New York. For additional guidance on Social Security benefits and eligibility timelines, you can also consult the official Social Security Administration website.
Take the Next Step Toward Coverage Confidence
Your healthcare coverage should give you confidence, not confusion. Whether you lean toward the total predictability of Plan G or the smart savings of Plan N, our licensed professionals are here to provide tailored recommendations that honor your budget and lifestyle.
Ready to find the ideal Medicare solution for 2026? Visit our Medicare Plans Page today or reach out to our expert team for a personalized, no-obligation consultation. Let Super Senior Services guide you toward clarity, affordability, and lasting peace of mind.

{“@type”:”BlogPosting”,”author”:{“name”:”Super Senior Services”,”@type”:”Organization”},”@context”:”https://schema.org”,”headline”:”Navigating Medicare in 2026: Plan G vs. Plan N and Your Best Strategy for Coverage”,”keywords”:[“Medicare 2026″,”Plan G vs Plan N”,”Medicare Supplement”,”Medigap”,”Super Senior Services”],”publisher”:{“url”:”https://superseniorservices.com”,”name”:”Super Senior Services”,”@type”:”Organization”},”description”:”Compare Medicare Supplement Plan G and Plan N for 2026. Learn about Part B deductibles, copays, premiums, and expert strategies for your healthcare coverage across FL, GA, TX, TN, NC, SC, VA, and NY.”,”mainEntityOfPage”:{“@id”:”https://superseniorservices.com/medicare/navigating-medicare-in-2026-plan-g-vs-plan-n”,”@type”:”WebPage”}}