Category: individualhealth
If you were enrolled in New York’s Essential Plan with household income between 200% and 250% of the federal poverty level (FPL), your coverage likely ended on June 30, 2026. Beginning July 1, 2026, that income bracket was removed from the Essential Plan.
That change created a coverage cliff for approximately 450,000 New Yorkers.
The good news is that you may have a path into a Qualified Health Plan (QHP) through NY State of Health. Losing your Essential Plan coverage is a qualifying life event, which generally gives you a Special Enrollment Period (SEP) outside the usual open enrollment calendar.
Because July 1 has already passed, the most important thing now is to act quickly: review your notice, update your household information, compare QHPs, and ask about retroactive coverage.
Who Is Affected by the Essential Plan Change?
The Essential Plan 200–250% FPL income category ended effective July 1, 2026. The affected income ranges include:
| Household size | Approximate 2026 annual income range |
|---|---|
| One person | $31,920–$39,900 |
| Two people | $43,280–$54,100 |
| Three people | $54,640–$68,300 |
| Four people | $66,000–$82,500 |
These figures are examples for 2026 and may not reflect every household’s eligibility determination. Your eligibility can depend on household size, Modified Adjusted Gross Income (MAGI), immigration status, access to other coverage, and information verified by NY State of Health.
The change may affect you if your notice says your Essential Plan eligibility ended because your income is now above 200% FPL. It may not affect you in the same way if your household circumstances have changed or if NY State of Health determined that you qualify for another program.
Your notice matters. Read it carefully before making assumptions.
What You Should Do Now
1. Review every notice and your NY State of Health account
Start by checking your mail, email, and NY State of Health account. Look for:
- The date your Essential Plan coverage ended
- The reason for the change
- Your household income and household size
- Instructions for choosing a new plan
- Your Special Enrollment Period deadline
- Any request for documents or verification
If something appears incorrect, do not ignore it. A missing pay stub, outdated income estimate, or household-status error can affect your eligibility and financial assistance.
NY State of Health also offers phone support at 1-855-355-5777. You can ask whether your case is eligible for a QHP SEP and what documentation is needed.
2. Update your household income
Your Marketplace application should reflect your best estimate of your 2026 household income, not simply last year’s income. Include expected wages, self-employment income, bonuses, unemployment income, taxable retirement income, and other applicable household income.
For example, if you recently began working more hours or changed jobs, your current estimate may be different from the income shown on an older application. On the other hand, if your income dropped, updating it may help you qualify for more financial assistance.
This step can directly affect your monthly premium and your eligibility for cost-sharing reductions. Accuracy protects both your coverage and your financial stability.
3. Use the Special Enrollment Period
The loss of Essential Plan coverage is a qualifying life event. That means you can generally enroll in a QHP through NY State of Health without waiting for the next open enrollment period.
New York guidance describes the affected residents’ enrollment window as running until August 30, 2026, or before September 1, 2026, depending on how the deadline is stated in the guidance or notice.
Here is the practical way to think about it:
- August 30, 2026: Treat this as the critical deadline to select and enroll in a QHP if you want to request coverage retroactive to July 1.
- Before September 1, 2026: Some state guidance describes this as the outer limit for using the SEP to enroll in replacement coverage.
- After August 30: Your ability to request July 1 retroactive coverage may be limited or unavailable, even if a prospective SEP option remains.
Do not wait until the final day. If your application needs documents, your income requires clarification, or a plan’s provider directory needs review, extra time is valuable.
Can Your New Coverage Be Retroactive to July 1?
If you are eligible and enroll in a QHP during the applicable SEP, you may request a retroactive effective date back to July 1, 2026.
Retroactive coverage is not necessarily automatic. Ask NY State of Health directly, or ask your enrollment professional to confirm:
- Whether you qualify for the affected Essential Plan transition SEP
- Whether your selected QHP can be made effective July 1
- How to formally request the retroactive date
- Whether you must pay premiums for the retroactive months
- How providers and pharmacies should resubmit claims once coverage is active
If your coverage is backdated, you may need to pay premiums for July and August before the plan processes claims from those months. Keep receipts, medical bills, pharmacy records, and explanations of benefits.
If you already received care after July 1, contact the provider’s billing office after your QHP is active. Ask whether the claim can be resubmitted using your new member identification number.
Attorney General Letitia James summarized the situation clearly:
“Losing health insurance can be stressful and confusing, and New Yorkers deserve clear, reliable information as they make decisions about their care.”
That is especially true when a plan change affects your prescriptions, doctors, and household budget all at once.
How QHP Costs Differ from the Essential Plan
The Essential Plan generally offered $0 monthly premiums, no deductible, and very low copays. A QHP may cost more, but financial assistance can make a significant difference.
Premiums
Your premium is the amount you pay each month to keep your plan active. A plan might list a premium of $450 per month, but a premium tax credit could reduce that amount (for example, from $450 to $175 per month).
Premium tax credits are based on household income, household size, location, and other eligibility factors. They are generally available only through NY State of Health.
Deductibles
A deductible is what you pay for certain covered services before the plan begins sharing costs. For example, with a $2,000 deductible, you may pay the first $2,000 of applicable covered care before coinsurance begins.
Some services, such as preventive care or certain primary-care visits, may be covered before the deductible. Review the plan details carefully.
Copays
A copay is a fixed amount for a covered service (for example, $25 for a primary-care visit or $50 for urgent care). Copays make some expenses easier to predict.
Coinsurance
Coinsurance is a percentage of the allowed cost that you pay after meeting the deductible. If a plan has 20% coinsurance and the allowed amount is $1,000, your share may be $200 while the plan pays $800.
Out-of-pocket maximum
Your out-of-pocket maximum is the most you generally pay during the plan year for covered, in-network services through deductibles, copays, and coinsurance. It does not usually include monthly premiums, noncovered services, or balance-billed charges.
Consequently, the plan with the lowest premium is not always the least expensive option overall.
Which QHP Should You Consider?
QHPs are ACA-compliant plans certified by a Marketplace, covering essential health benefits and following limits on cost-sharing. You can review the official definition in the HealthCare.gov Qualified Health Plan glossary.
When comparing plans through NY State of Health, pay attention to five areas.
Provider networks
A network is the group of doctors, hospitals, clinics, and other providers contracted with a plan. Confirm that your primary-care doctor, specialists, preferred hospital, and nearby urgent-care locations are in-network.
An HMO or EPO may provide little or no coverage for routine out-of-network care. A PPO may offer more flexibility but often costs more.
Formularies
A formulary is the plan’s list of covered prescription drugs. Check each medication by exact name, dosage, and quantity. A drug may be covered but placed on a higher tier, meaning you pay more (for example, a $10 copay versus 30% coinsurance).
Also check whether prior authorization, step therapy, or mail-order requirements apply.
Metal tiers
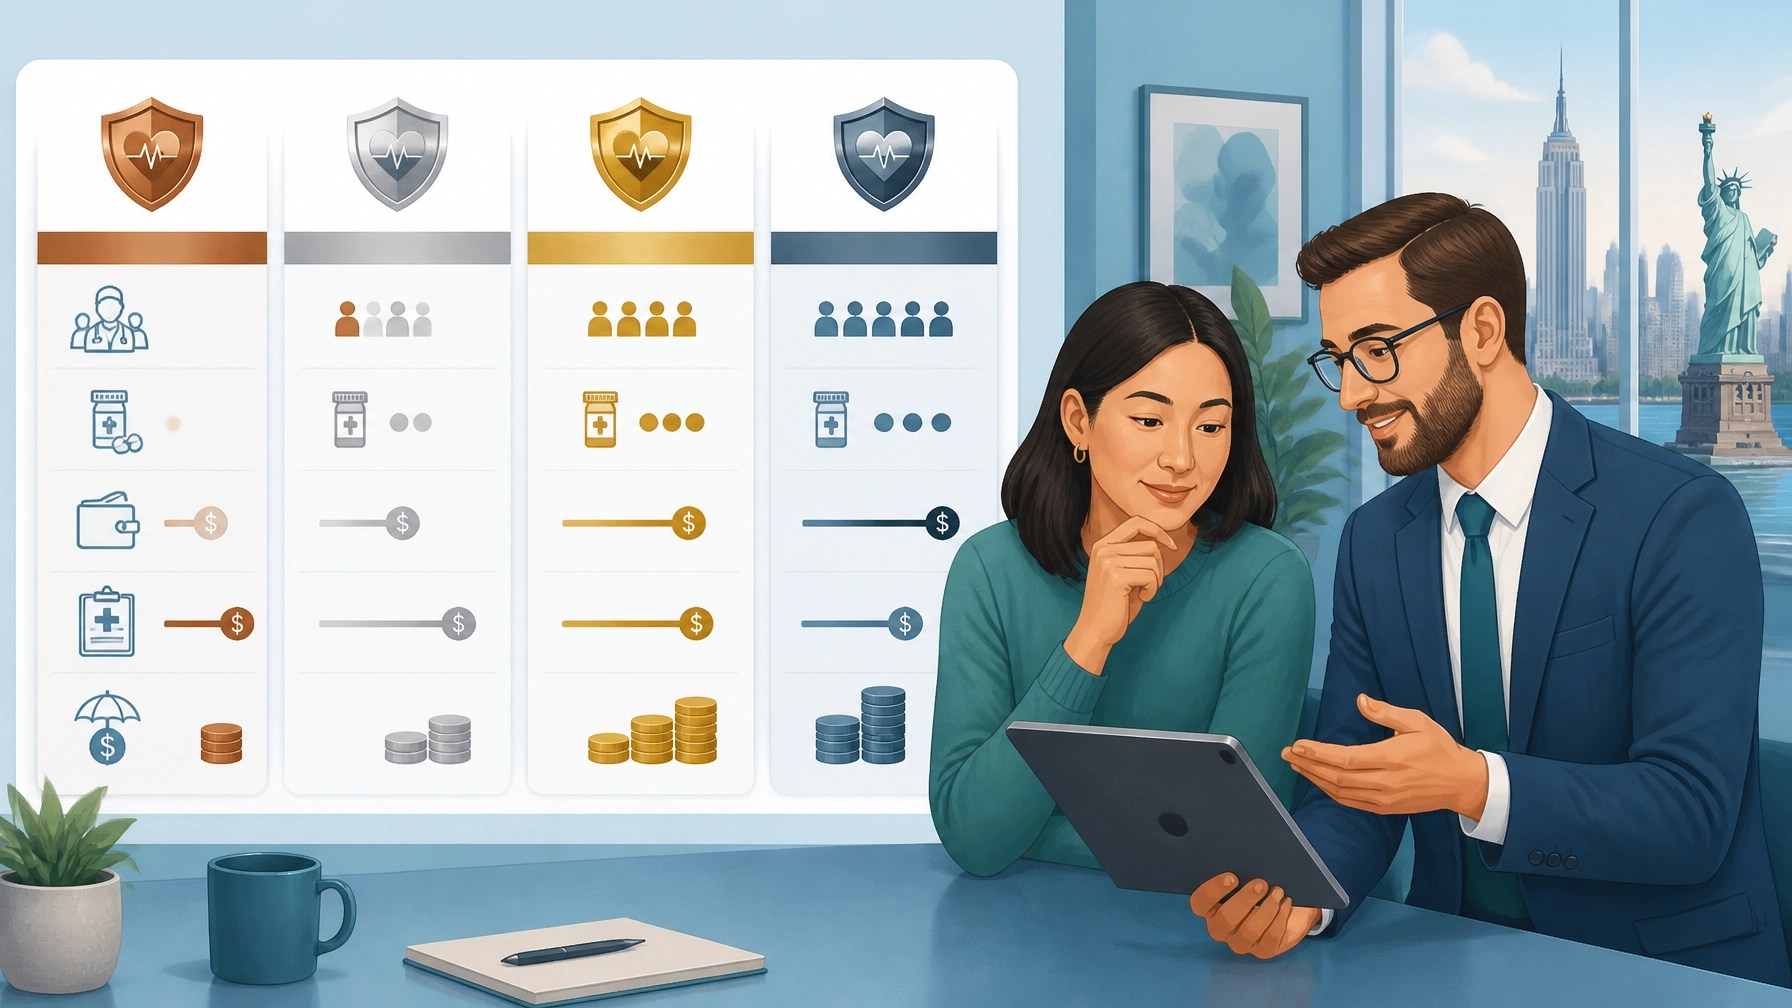
Metal tiers describe how you and the plan generally divide covered healthcare costs:
- Bronze: Lower premiums, higher deductibles, and the plan pays about 60% of covered costs.
- Silver: Moderate premiums and deductibles; the plan pays about 70%.
- Silver with cost-sharing reductions: Additional savings may lower deductibles, copays, coinsurance, and the out-of-pocket maximum. Depending on income, the plan may pay approximately 73%–96% of covered costs.
- Gold: Higher premiums, lower deductibles, and the plan pays about 80%.
- Platinum: Highest premiums, lowest deductibles, and the plan pays about 90%.
If you qualify for cost-sharing reductions, you generally must choose a Silver plan to receive them. That choice can significantly lower your total healthcare spending.
Total annual cost
Compare more than the monthly premium. Estimate:
Annual premiums + expected medical costs + prescription costs
For example, a plan costing $150 per month may appear affordable, but a $6,000 deductible and high coinsurance could make it costly if you expect regular treatment. A $250-per-month plan with lower copays and a $2,500 deductible may provide better financial protection.
Quality and member experience
Review available star ratings, plan documents, customer-service information, and claims procedures. A plan that fits your doctors and medications is more useful than one that looks inexpensive but creates barriers to care.
How Super Senior Services Can Help
Super Senior Services provides personalized individual health insurance guidance exclusively for New York residents. We help simplify the transition from the Essential Plan to a QHP by reviewing your:
- Doctors and hospitals
- Prescription medications
- Household income
- Preferred monthly budget
- Deductible and copay preferences
- Estimated total annual healthcare cost
- Network and formulary needs
Our goal is not simply to help you enroll. It is to help you understand what you are choosing, avoid unexpected expenses, and protect your access to care.
If your Essential Plan ended July 1, review your notice and act now. Contact Super Senior Services for personalized guidance, or learn more about available plan support.
Compliance information: Individual NPN : Stephen Jackson: 20707378. Corporate NPN : Super Senior Services: 21536694.
Take the Next Step Before the Deadline
The coverage cliff is real, but you still have options. Update your information, use your Special Enrollment Period, compare QHPs carefully, and ask whether you can request retroactive coverage back to July 1, 2026.
You do not have to sort through premiums, deductibles, formularies, provider networks, and tax credits alone. Contact Super Senior Services today for clear, personalized help choosing New York individual health coverage that supports your health, budget, and peace of mind.