If you’ve been feeling a bit of "insurance vertigo" lately, you aren’t alone. On July 1, 2026, the landscape shifted for nearly 450,000 New Yorkers. We’ve been calling it the "Essential Plan Cliff," and if your income falls between 200% and 250% of the Federal Poverty Level (FPL), your $0 premium Essential Plan coverage officially ended at the start of this month.
It’s now July 22nd, and if you haven’t selected a new Qualified Health Plan (QHP) yet, you might be worried about a gap in coverage. Here is the good news: you are still in a special "safety net" window. You have until August 30, 2026, to enroll in a new plan and secure retroactive coverage all the way back to July 1.
But let’s be real: August 30 will be here before you know it. If you miss that date, you could be left without coverage until the next Open Enrollment period begins on November 1. At Super Senior Services, we don't want to see that happen to our New York neighbors.
Take a deep breath. We’ve put together a simple, 5-step action plan to help you navigate the cliff and land safely on a plan that fits your life and your budget.
Step 1: Confirm Your "Cliff" Status
The first step is knowing exactly where you stand. The New York State of Health (NYSOH) marketplace determines eligibility based on your Modified Adjusted Gross Income (MAGI).
If you were previously on the Essential Plan but your income is in the 200–250% FPL range, you are the one affected by this change. For 2026, those income limits generally look like this:
- Individual: Between $31,920 and $39,900 annually.
- Couple: Between $43,280 and $54,100 annually.
- Family of Four: Between $66,000 and $82,500 annually.
If your income is below those numbers, you likely stayed on the Essential Plan without a hitch. If you’re in that specific bracket, though, the state has transitioned you into a "Special Enrollment Period." You should have received a notice in your NY State of Health account or via mail. Check there first to verify your status.
Step 2: Explore Subsidized Silver Plans
While the $0 premium Essential Plan might be a thing of the past for this income bracket, the "cliff" doesn't mean you're being thrown into high-cost insurance without help. In fact, most people moving off the Essential Plan qualify for significant Advanced Premium Tax Credits (APTC).
These credits act like an immediate discount on your monthly bill. When you shop the marketplace, look specifically for Silver Plans. Why Silver? Because that’s where "Cost-Sharing Reductions" (CSRs) live.
"The goal of the marketplace transition isn't just to find 'a' plan, but to find the 'right' plan that balances your monthly premium with what you pay when you actually see a doctor."
By selecting a Silver-level plan, you not only get the tax credit to lower your premium, but you also get lower deductibles and co-pays. This helps maintain that financial stability you were used to with the Essential Plan. You can learn more about how these credits work on our page about the Premium Tax Credit.
Step 3: Check Your Doctors and Formularies
Don't let the rush of the deadline make you skip the fine print. One of the biggest mistakes we see is people picking the plan with the lowest monthly premium, only to realize their favorite doctor isn't in the network or their maintenance medication isn't on the "formulary" (the list of covered drugs).
Before you click "enroll," do a quick check:
- Provider Search: Is your primary care physician or specialist in-network?
- Prescription Check: Does the plan cover your specific medications, and what is the tier (e.g., $10 vs. $50 per prescription)?
- Facility Access: Are the hospitals near you covered?
At Super Senior Services, we specialize in these comprehensive benefit reviews. We don't just look at the price tag; we look at the doctors you actually visit to ensure your transition is seamless.
Step 4: Secure Retroactive Coverage (The August 30 Deadline)
This is the most critical part of the plan. Because we are in late July, the clock is ticking.
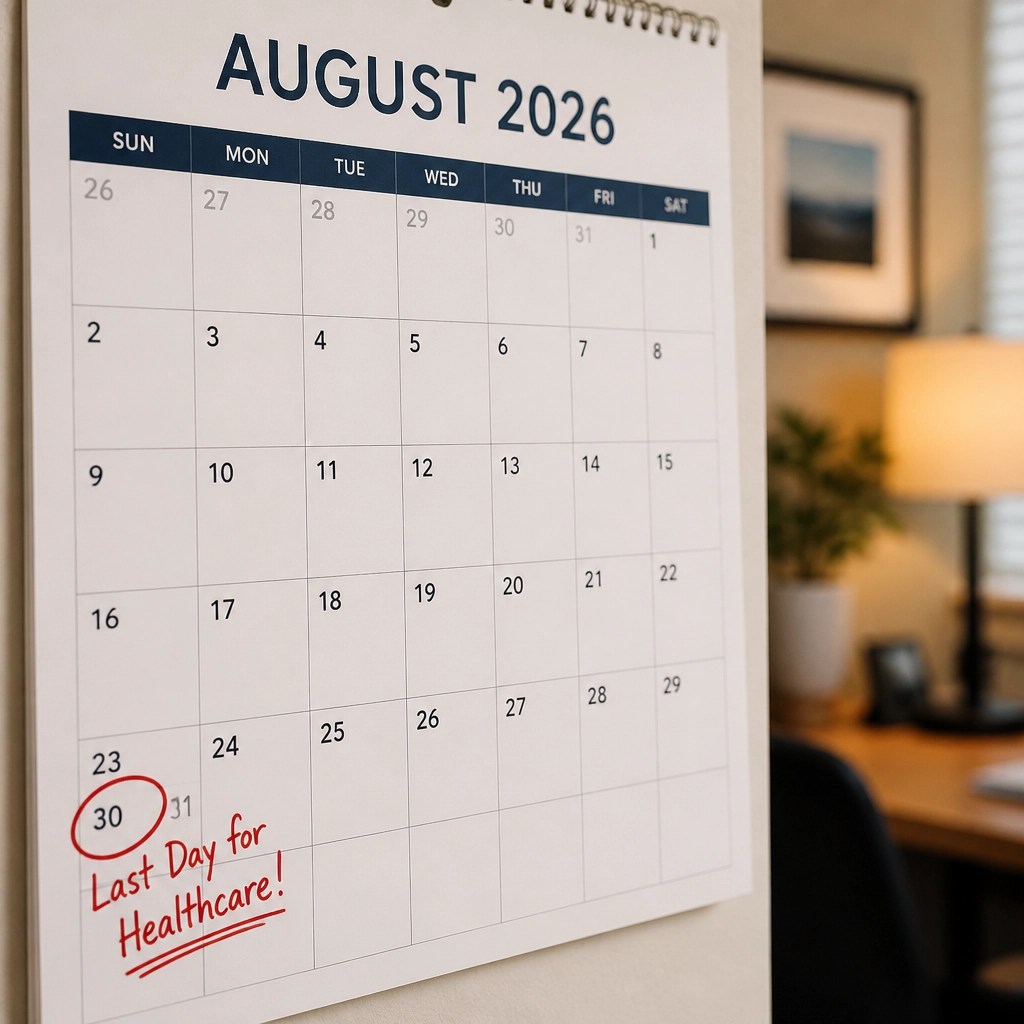
New York has granted a special rule for this transition: If you enroll by August 30, 2026, your coverage will be retroactive to July 1, 2026.
This is a huge deal. It means if you had a doctor's appointment or a prescription fill earlier this month, you can actually get those costs covered once your new plan is active. However, if you wait until August 31, that "retroactive" window slams shut. Consequently, you could be left with a multi-month gap in coverage, which is a risk no one should have to take.
Remember, the next standard Open Enrollment doesn't start until November. Don't leave your health to chance: mark August 30 on your calendar in bright red ink!
Step 5: Get Professional, Personalized Guidance
You don't have to do this alone. Navigating NY State of Health marketplace can feel like learning a second language. Between premiums, coinsurance, and out-of-pocket maximums, it’s a lot to digest.
Super Senior Services was built on the foundation of transparency and trust. We act as your guide through the entire selection process. Our USPs are centered around you:
- Personalized Plan Recommendations: We don't believe in one-size-fits-all.
- Simplified Comparisons: We break down the trusted providers in New York so you can see the differences clearly.
- Expert Oversight: We ensure your plan meets your evolving needs, even after you've enrolled.
Whether you're a pre-retiree looking at individual health options or a small business owner in New York trying to help your employees through this transition, we are here to help.
Final Thoughts: Peace of Mind is Only a Call Away
The "Essential Plan Cliff" was a sudden change, but it doesn't have to be a disaster. By taking these five steps, you can move from uncertainty to excellence. You deserve affordable coverage that doesn't sacrifice the quality of your care.
Once you’re in a plan that works for you, you’ll regain that peace of mind that comes with knowing you’re protected. But remember: the August 30 deadline is firm. Let's get you enrolled before the summer ends!
Ready to find your perfect plan?
Don’t wait for the deadline to loom even closer. Reach out to Stephen Jackson and the team at Super Senior Services today. We’ll review your options and make sure you’re covered.
- Visit our enrollment page: superseniorservices.com/medplans
- Contact us directly: superseniorservices.com/contact
Compliance Information:
Stephen Jackson, Individual NPN: 20707378
Super Senior Services, Corporate NPN: 21536694
{“name”:”5-Step Action Plan for the NY Essential Plan Cliff”,”step”:[{“name”:”Confirm Your Income Bracket”,”text”:”Check if your income falls between 200% and 250% of the Federal Poverty Level ($31,920–$39,900 for individuals) to see if you are affected by the coverage end.”,”@type”:”HowToStep”},{“name”:”Explore Subsidized Silver Plans”,”text”:”Look for Silver-level plans on the NY State of Health marketplace to take advantage of Premium Tax Credits and Cost-Sharing Reductions.”,”@type”:”HowToStep”},{“name”:”Check Your Doctors and Meds”,”text”:”Verify that your preferred healthcare providers and necessary prescriptions are included in the new plan’s network and formulary.”,”@type”:”HowToStep”},{“name”:”Secure Retroactive Coverage”,”text”:”Enroll by the August 30, 2026 deadline to ensure your health coverage is retroactive to July 1, 2026.”,”@type”:”HowToStep”},{“name”:”Get Professional Guidance”,”text”:”Contact Super Senior Services for a personalized benefit review to ensure you select the most affordable and effective plan for your needs.”,”@type”:”HowToStep”}],”tool”:[{“name”:”NY State of Health Marketplace Account”,”@type”:”HowToTool”}],”@type”:”HowTo”,”supply”:[{“name”:”Income Verification”,”@type”:”HowToSupply”}],”@context”:”https://schema.org”,”totalTime”:”P30D”,”description”:”A guide for New Yorkers in the 200-250% FPL income bracket to transition from the Essential Plan to a Qualified Health Plan before the August 30, 2026 deadline.”}